


EN
Dell (DELL) Stock Looks Reasonable After Its 446% Five Year Run
Dell Technologies has seen its stock price swing sharply in recent months after a long stretch of very strong gains. This puts fresh focus on whether today’s valuation can still be explained by its earnings power. With investor attention pulled between AI-related projects, data center exposure and a volatile share chart, the key issue is how the current share price lines up against what the business earns.
- Over the past 5 years the stock has returned about 4.5x, which raises the question of how much of that move can be grounded in Dell’s earnings profile rather than sentiment alone.
- Recent AI and data infrastructure partnerships, including work with NVIDIA and large research institutions, can influence expectations for future profit streams, capital intensity and how quickly earnings might be realized.
- There is a second opinion on Dell Technologies worth weighing. See what analysts think Dell Technologies's shares could be worth.
The issue now is whether Dell Technologies’ current share price is adequately supported by its earnings when judged against the Fair Ratio benchmark.
If you want to test the same earnings question across a broader slice of AI infrastructure and data center hardware players, line Dell up against the companies in the 52 AI infrastructure stocks.
Is Dell Technologies a Bargain on Earnings?
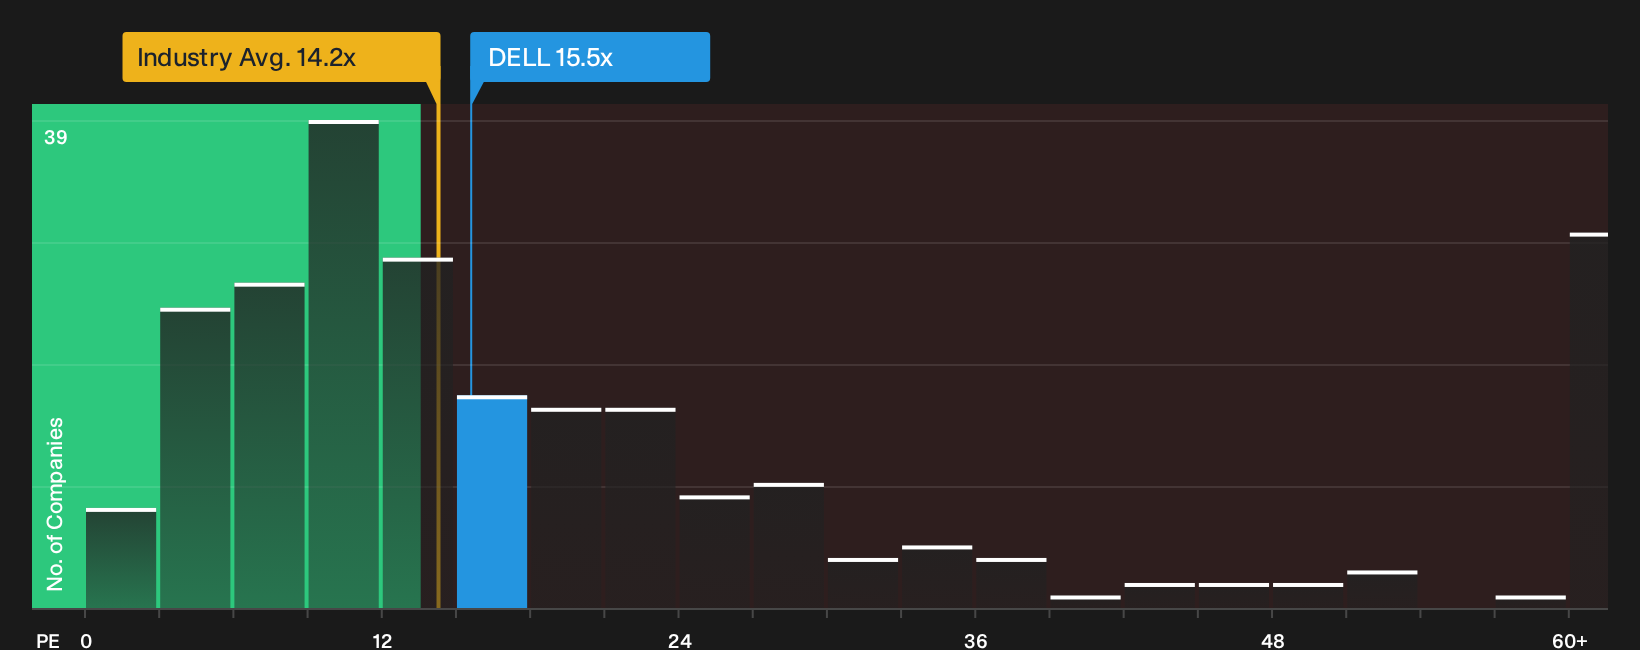
The P/E ratio suits Dell Technologies because investors are focused squarely on what its AI and infrastructure push means for future earnings power. Right now the stock trades at about 15.5x earnings, slightly above the broader tech sector on roughly 14.2x and close to peers around 14.7x, which points to a modest premium for the business.
Because Dell screens below the Fair Ratio level that would typically be expected for its mix of growth opportunities, margins, size and risk profile, the current P/E suggests the stock is undervalued on this framework rather than priced for perfection. Despite the recent run of AI infrastructure announcements with NVIDIA and others lifting attention on the story, the multiple still sits at a discount to what the tailored Fair Ratio indicates might be appropriate for Dell’s earnings. Explore the numbers behind Dell Technologies's P/E valuation.
The Dell Technologies Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Dell Technologies valuation question leaves off by spelling out which paths for growth, margins and earnings would need to play out for the stock to be worth materially more or less than today’s price on the Community page. Rather than rely on a single P/E or model output, each narrative lays out the specific assumptions behind its view of fair value so you can compare those expectations with future results.
One of the top narratives on Dell Technologies: 52% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The numbers imply that Dell Technologies' current share price already reflects a bullish view on its AI driven growth and operating leverage, so the stock is fairly valued on this narrative…"
Discover why this Narrative puts Dell Technologies at 52% undervalued.
One more Dell Technologies check that belongs beside the price tag
Before you file Dell Technologies under fairly priced or not, it is worth seeing what the broader fundamental checks have flagged, because some of those red flags can matter more than the headline P/E. Take a closer look at 3 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com