


EN
Is Harbour Energy (LSE:HBR) Already Priced Right After Its Cash Flow Upgrade?
Harbour Energy has delivered a 39.7% gain over the past three years, yet the share price has recently slipped, which puts fresh focus on whether the current market value lines up with what its earnings can support. With investors weighing upbeat headlines on cash generation against a weaker recent share price, the question now is how much of those profits are already baked into Harbour Energy's valuation.
- A 39.7% return over three years puts real weight on the earnings story because a lot of long term holders now rely on those profits to justify staying invested.
- Recent commentary that Harbour Energy may generate higher free cash flow and has room for debt reduction and buybacks can support the idea that its earnings power might carry more value than the latest share price drop suggests.
- The analysts covering Harbour Energy have run their own numbers. See what analysts think Harbour Energy's shares could be worth.
The issue now is whether Harbour Energy's current share price is appropriately supported by the earnings it is generating today and is expected to deliver over time.
If you are weighing Harbour Energy's earnings story against its recent share price drop, it can help to compare that setup with 18 high quality undervalued stocks.
Where Does Harbour Energy Sit on Earnings?
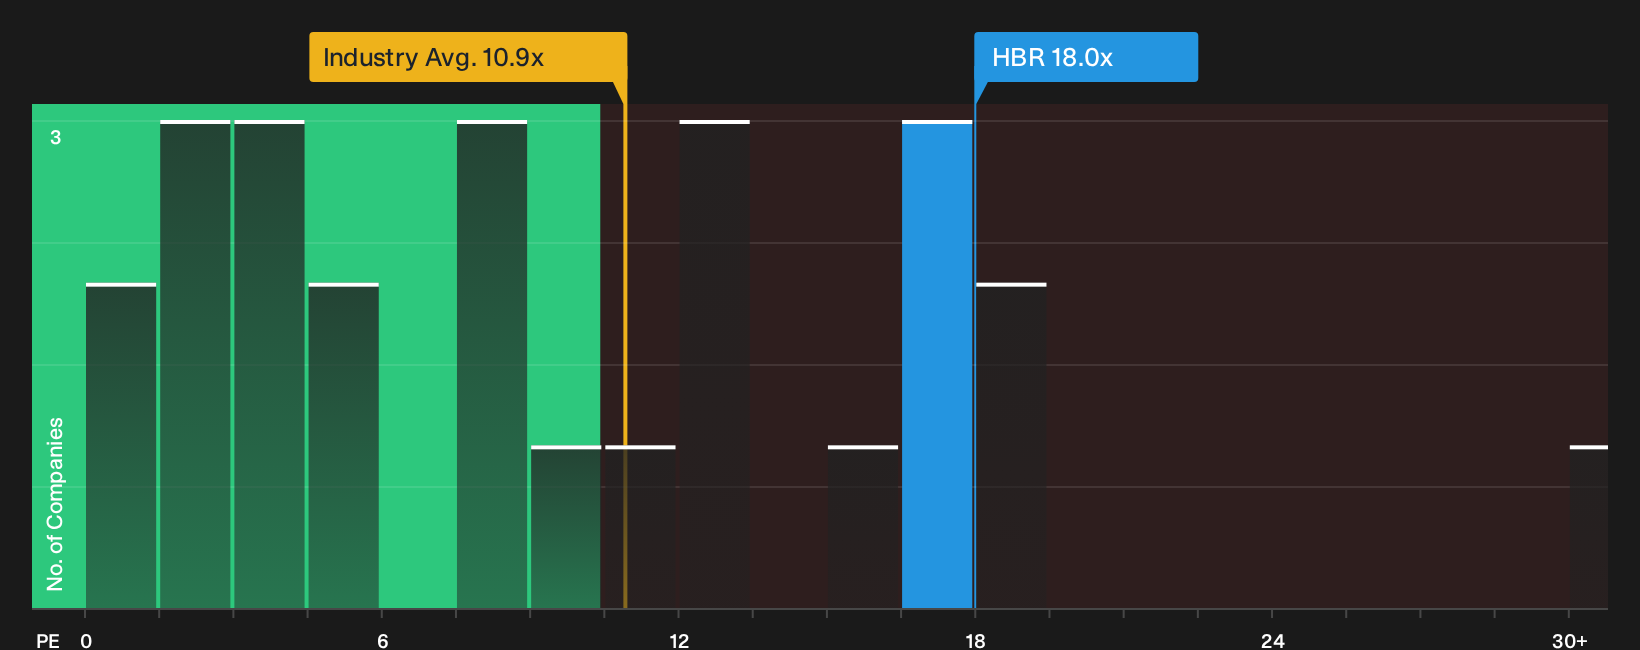
P/E works well for Harbour Energy because earnings currently provide a clear anchor for what you are paying per pound of profit. On this measure, the shares trade on roughly 18.0x earnings, compared with an Oil and Gas sector average of about 10.7x and a peer group near 13.8x. That marks a premium both to the wider industry and to closer comparables.
Given the higher P/E, the key question is whether Harbour Energy’s cash generation, balance sheet position and tax profile justify paying more for each unit of earnings. The Fair Ratio model, which blends factors like growth expectations, profitability and risk for this specific business, points to a level close to where the shares change hands today, so the current multiple looks about right rather than clearly cheap or expensive. Because management has talked about stronger free cash flow and increased returns to shareholders, the market already prices in a fair amount of that story at this valuation. Explore the numbers behind Harbour Energy's P/E valuation.
The Harbour Energy Narrative: What Would Justify Today's Price?
Narratives for Harbour Energy pick up where the P/E puzzle leaves off, by explaining what future growth, margins and earnings would need to look like for the shares to be priced meaningfully higher or lower than they are today. Rather than relying on a single ratio or model output, they outline the future path that number depends on so you can track how Harbour Energy's actual progress compares with those underlying assumptions. These are available on Simply Wall St's Community page.
One of the top narratives on Harbour Energy: 29% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The integration of the Wintershall Dea acquisition has significantly increased Harbour Energy's production scale and asset diversification, substantially reducing reliance on mature UK North Sea assets..."
Discover why this Narrative puts Harbour Energy at 29% undervalued.
The share price is only one piece of the Harbour Energy puzzle
Harbour Energy's current valuation tells you what the market thinks today, but the analyst outlook a few years from now can reshape how you view those earnings and the risk you are taking. Explore where analysts expect Harbour Energy to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com