


EN
Why ASM International Rose Even Though Profit Fell
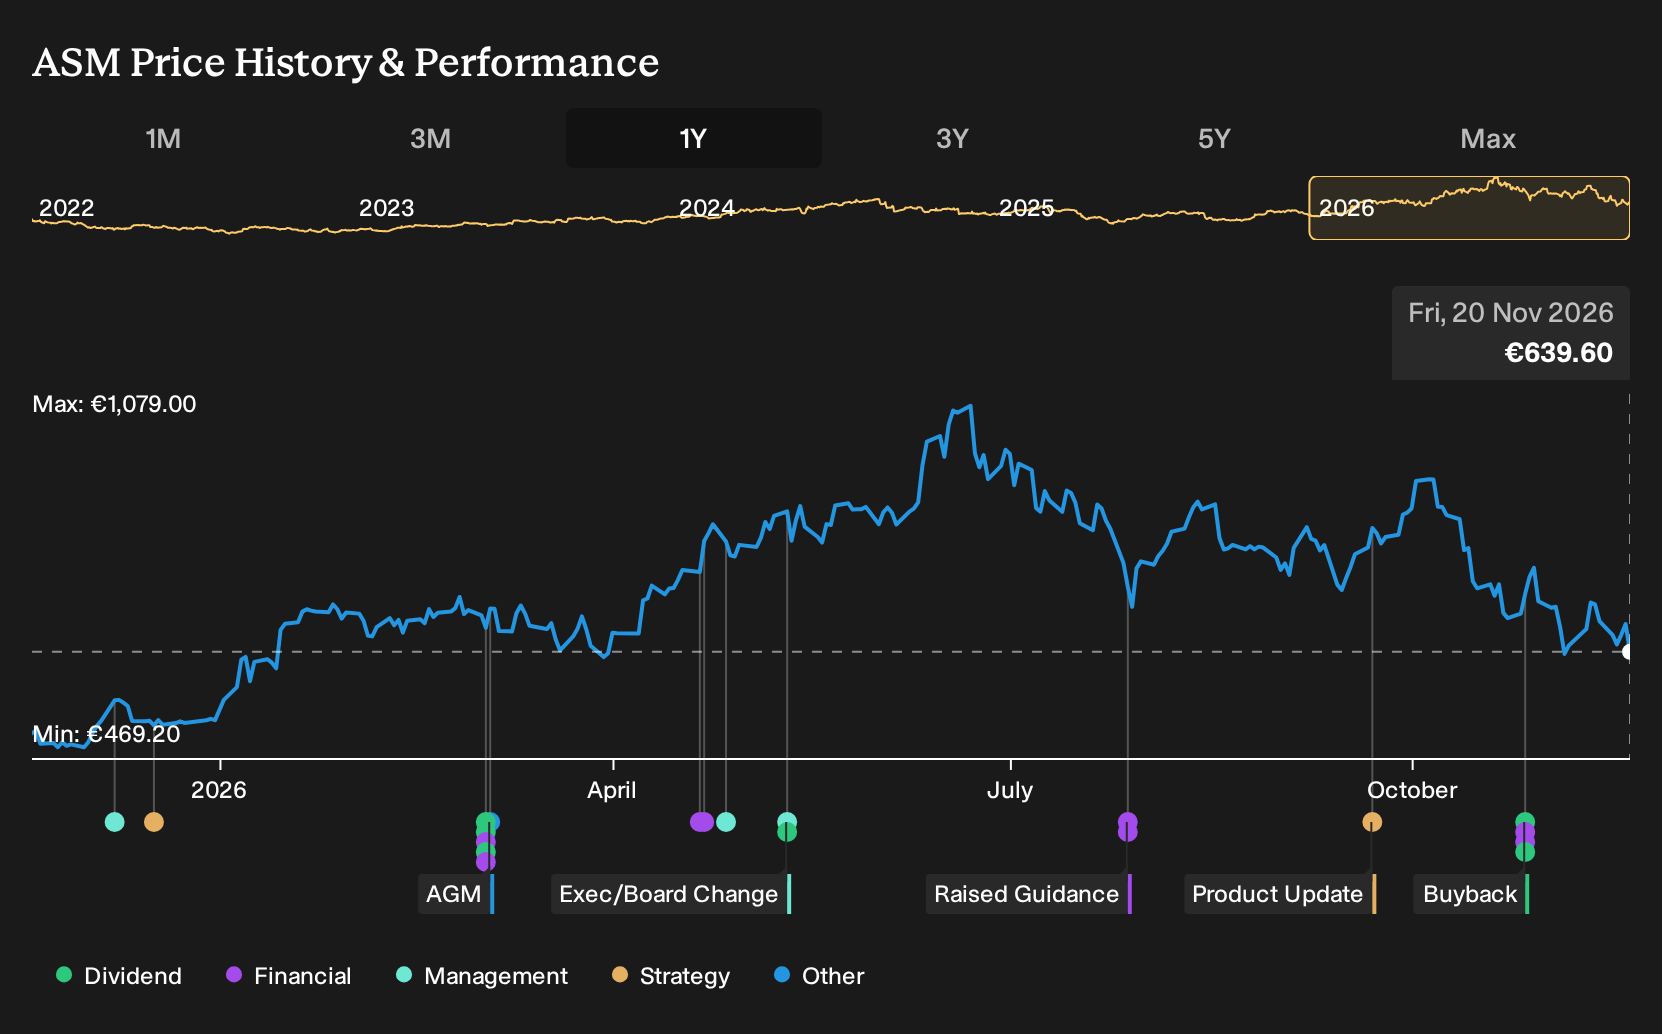
If ASM International sat on your watchlist instead of in your account over the last year, the outcome may sting. Investors who held ASM International over the past year are up 35.1%, including dividends. That move sits between analysts in late 2025 arguing over how fast revenue could compound and what P/E might be reasonable. If you rewind to that debate, which business call really mattered, the 12.0% growth path or the assumption that margins could climb above 24%?
ASM International has already moved. Pinpoint other ways to investigate the theme among 53 AI infrastructure stocks.
The Two ASM International Stories Investors Had In Front Of Them
The shares cost €498 at the start of the period, so every view on ASM International hinged on whether that entry point already captured the next phase of semiconductor spending.
The bullish narrative saw fair value at €571, a notional price implied by assumptions such as 12.0% annual revenue growth and profit margins reaching 24.3%, supported by confidence in advanced deposition tools and services.
The more cautious view put fair value at €440, based on concerns that heavier compliance costs and export controls could pressure earnings despite solid demand for high end equipment.
What The 2026 Results Really Tested For ASM International
The clearest new fact was ASM International’s 2026 update that Q3 revenue reached €1.159b, well above the €800m in Q3 2025, which supported the bulls’ focus on AI linked tools and advanced nodes. The catch was earnings. Net income excluding extra items moved to €308.1m from €384.2m and net margin fell from 48.0% to 26.6%. The evidence cut both ways.
The key lesson is simple. When a story hinges on high future profitability, do not just track sales headlines. Watch whether net income and net margin actually move toward the profile analysts pencilled in at the decision date.
What ASM International's Price Already Assumes Today
ASM International now trades at €640 after a 35.1% gain over the past year. The bearish analyst Narrative on Simply Wall St places its Fair Value above that price, built on cautious forecasts rather than a blanket endorsement.
The Narrative leans on AI driven tooling, memory transitions and services to carry a heavy load. The question for anyone paying €640 is whether robust AI led node migrations and high margin service contracts can keep supporting that view.
"The main thing that has to go right is that AI driven node transitions, DRAM roadmaps and adjacent process and packaging products generate enough high margin tool and services revenue to offset a double digit decline in China and a prolonged downturn in power and analog markets. The numbers imply that ASM International’s share price already reflects strong AI and memory growth, record €1.0b quarterly revenue, higher long term margin targets and expectations for 2027 revenue above the prior €3.7 to €4.6b range, leaving limited room for disappointment if any of these pillars soften."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
One Step Beyond ASM International
ASM International puts capital equipment at the center of your attention. You could also look at who shapes the underlying computing blueprints.
Instead of selling hardware, this other business licenses processor designs and earns royalties when customers ship chips.
Those designs sit inside phones, laptops, cars, cloud servers and AI infrastructure, giving it reach across very different spending cycles.
As more devices and data centers need efficient compute, that royalty model may behave differently from a pure equipment maker like ASM International.
The case is written up, with the assumptions it depends on. → Discover the robotics company one Narrative values 183% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com