


EN
Did Half Year Earnings Miss Just Shift Jet2's (AIM:JET2) Investment Narrative?
- Jet2 reported half year 2026 sales of £5,632.6 million, net income of £489.2 million, and kept its interim dividend at 4.5 pence per share, while also ending Rick Green’s directorship on 18 November 2026.
- The combination of higher sales alongside lower earnings and an unchanged interim dividend highlights pressure on Jet2’s profitability even as customer demand supports revenue.
- We will now look at how Jet2’s investment narrative is affected by the past half year earnings miss versus net income and EPS.
Compare Jet2's profitability squeeze with other travel and leisure stocks facing similar margin pressure by scanning our hand picked list of solid balance sheet and fundamentals (7 results).
Jet2 Investment Narrative Recap
To own Jet2, you need to be comfortable with a simple idea. The traveller demand story is intact, while the harder work is happening in costs and execution. Sales for the half year reached £5,632.6 million, but net income of £489.2 million and lower earnings per share show that hotel inflation, fuel commitments and Gatwick ramp up are all compressing profitability.
The analyst consensus narrative on Simply Wall St focuses on fleet efficiencies, southern UK growth and strong package holiday engagement as the key near term catalysts. The biggest risk right now is that accommodation and fuel costs keep outpacing pricing, so the pressure on margins seen in this half year lingers even if volumes stay healthy.
The dividend affirmation to 4.5 pence per share for the half year is likely to be the announcement that investors focus on most. It points to management keeping capital returns steady despite the profit squeeze, supported by what has been robust cash generation and more than £2b of net cash in recent years.
For you as a shareholder, that payout decision sits on the fault line between opportunity and risk. It relies on the same catalysts that analysts highlight, such as the Airbus A321neo roll out and Gatwick build out, to support future cash flows, while also testing how much margin compression Jet2 can absorb before the current balance between investment and distributions needs to be revisited.
Jet2's outlook projects £9.6b revenue and £403.4 million earnings by 2029. That profile implies 8.7% yearly revenue growth and an earnings decrease of about £7.1 million from current earnings of £410.5 million.
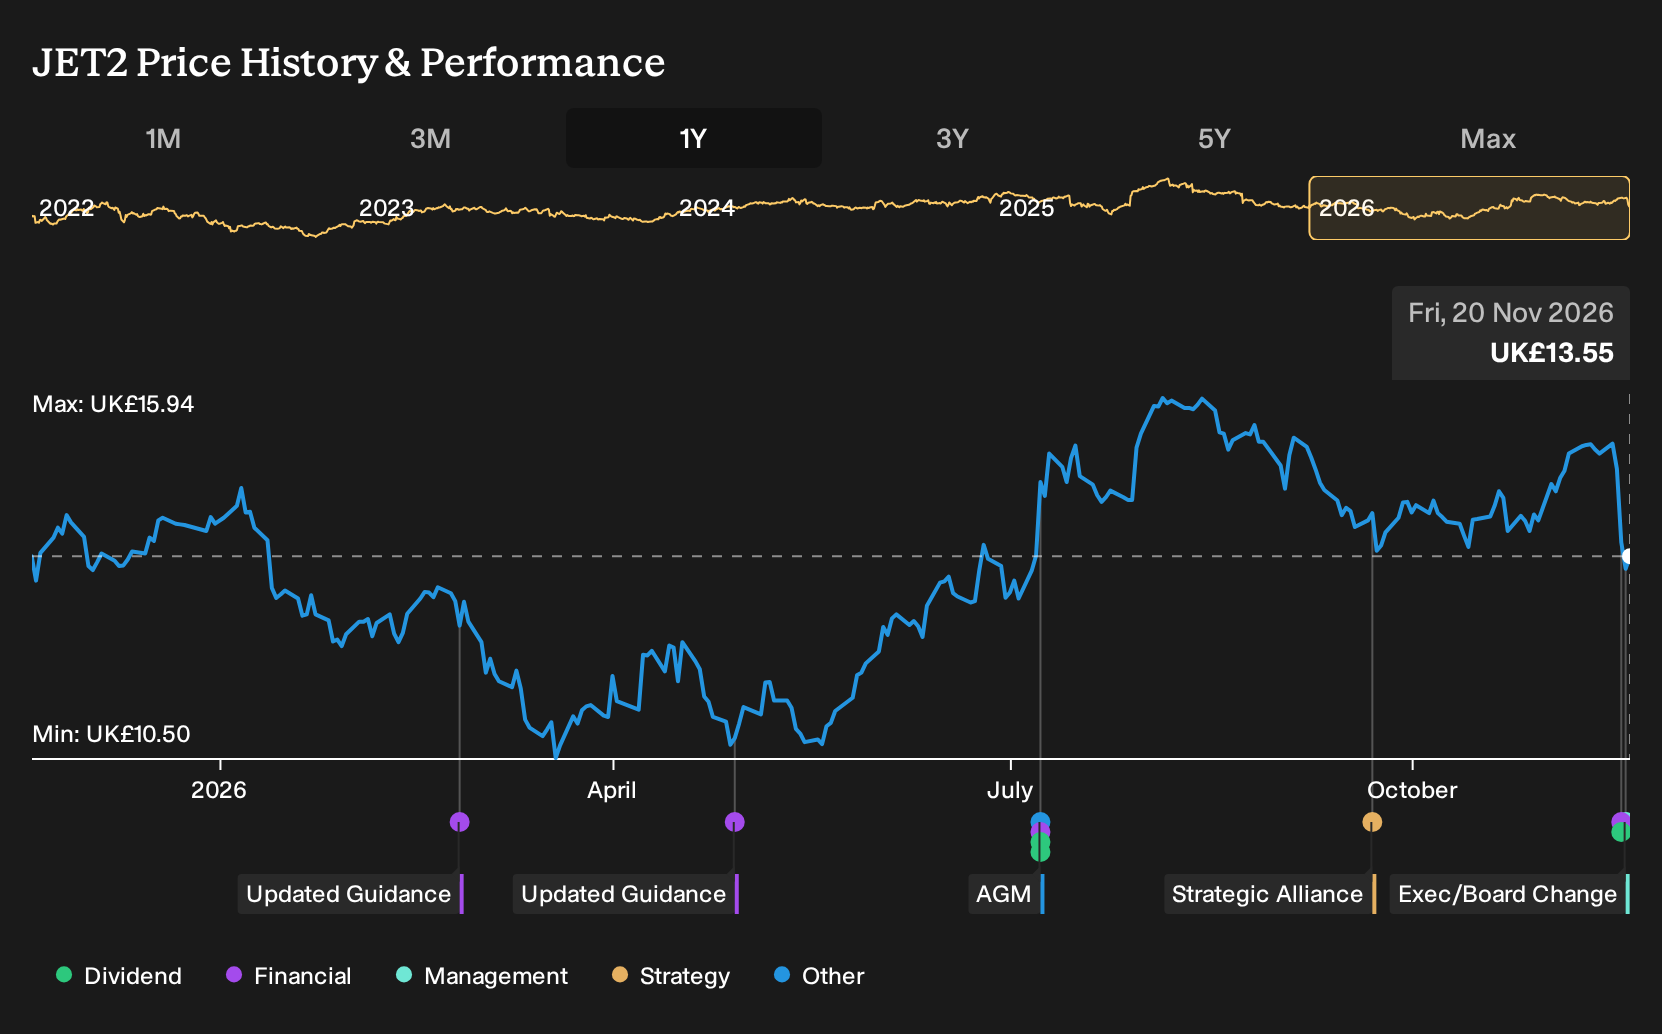
Uncover why Jet2's fair value indicates a 21% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts lean hard into Jet2’s Airbus A321neo fleet roll out. Before this profit squeeze and the Rick Green board exit, they were pencilling in about £10.4b of revenue and £549.5 million of earnings by 2029. You can compare that upbeat view with your own read of today’s board and dividend signals.
Explore 4 other Jet2 fair value estimates, including one that suggests as much as 48% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Jet2 research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Jet2. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Jet2's overall financial health at a glance.
Looking for more Jet2 style investment ideas?
If the Jet2 story has you thinking about where else strong fundamentals and clear trade offs are visible, the Simply Wall St Screener can help you filter the wider market into a focused shortlist that actually matches your risk and income preferences.
- If capital preservation ranks high for you, start with sturdier balance sheets and lower perceived risk by reviewing the 7 resilient stocks with low risk scores.
- If you want income to play a bigger role alongside any Jet2 holding, weigh up stable cash payers using the 6 dividend fortresses.
- If you are hunting for companies where the numbers look solid but attention is limited, widen your search with the 5 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com