


EN
3 Asset Manager Stocks With Recurring Fees As Private Markets Face A Liquidity Test
Private markets promised smoother returns and exclusivity. Now aging buyout portfolios, a looming $300b debt wall and fresh questions about liquidity are forcing a rethink of where investors keep their money. That tension can shift attention back to listed asset managers and low cost ETF providers exposed to this news. This article walks through three stocks from the screener that could benefit and what their business mix means for your portfolio risk.
The three stocks below are just a sample from this theme. The full screen surfaced 12 more publicly listed asset managers and ETF providers with equally compelling narratives that are not covered in this article. To go broader and identify your own highest conviction ideas, head straight into the Traditional Public Asset Managers and Low-Cost ETF Providers screener.
Azimut Holding (BIT:AZM)
Azimut Holding is one of the clearer fits for this screen, with a fee based asset management and advisory model that leans on liquid mutual funds, pensions and insurance wrappers, and the analyst consensus Narrative on Simply Wall St frames that mix as central to its outlook.
"Growing retirement savings needs and an aging population, especially in core markets, continue to align with Azimut Holding’s rising proportion of revenues from recurring management and other fees that now account for over 90% of total revenues."
What happens if one quiet pressure in that fee engine shifts course will matter a lot for how investors judge Azimut Holding’s resilience.
That quiet pressure point is exactly where Azimut Holding’s story starts to get interesting, and the full narrative for Azimut Holding lays out how that engine could accelerate or stall next.

Hamilton Lane (HLNE)
Hamilton Lane matters for this asset manager and ETF screen because it lets public investors tap private equity and venture-style exposure through a listed vehicle, and according to John_Eric, a Simply Wall St Community investor who wrote about the stock, the way its fee engine works is the real story.
"Hamilton Lane operates on two very different financial clocks. The first measures management and advisory fees, which are recurring, comparatively stable, and tied to the capital the firm manages or advises."
What happens if that quieter clock keeps compounding while the lumpier one swings around it could reshape how investors think about Hamilton Lane’s earnings resilience.
Hamilton Lane is a listed private markets specialist that runs private equity and venture strategies for institutions, fitting the screener as an asset manager rather than an ETF provider, earning about $872 million from asset management and carrying a market value near US$4.5b.
If that second fee clock keeps decoupling, the full narrative for Hamilton Lane explains how Hamilton Lane’s structure could help turn volatility into a more durable earnings story.

ICG (LSE:ICG)
ICG gives you listed-market access to private equity and private credit, which fits the screener’s focus on sizable, liquid asset managers while tilting more toward alternative strategies than low cost ETFs.
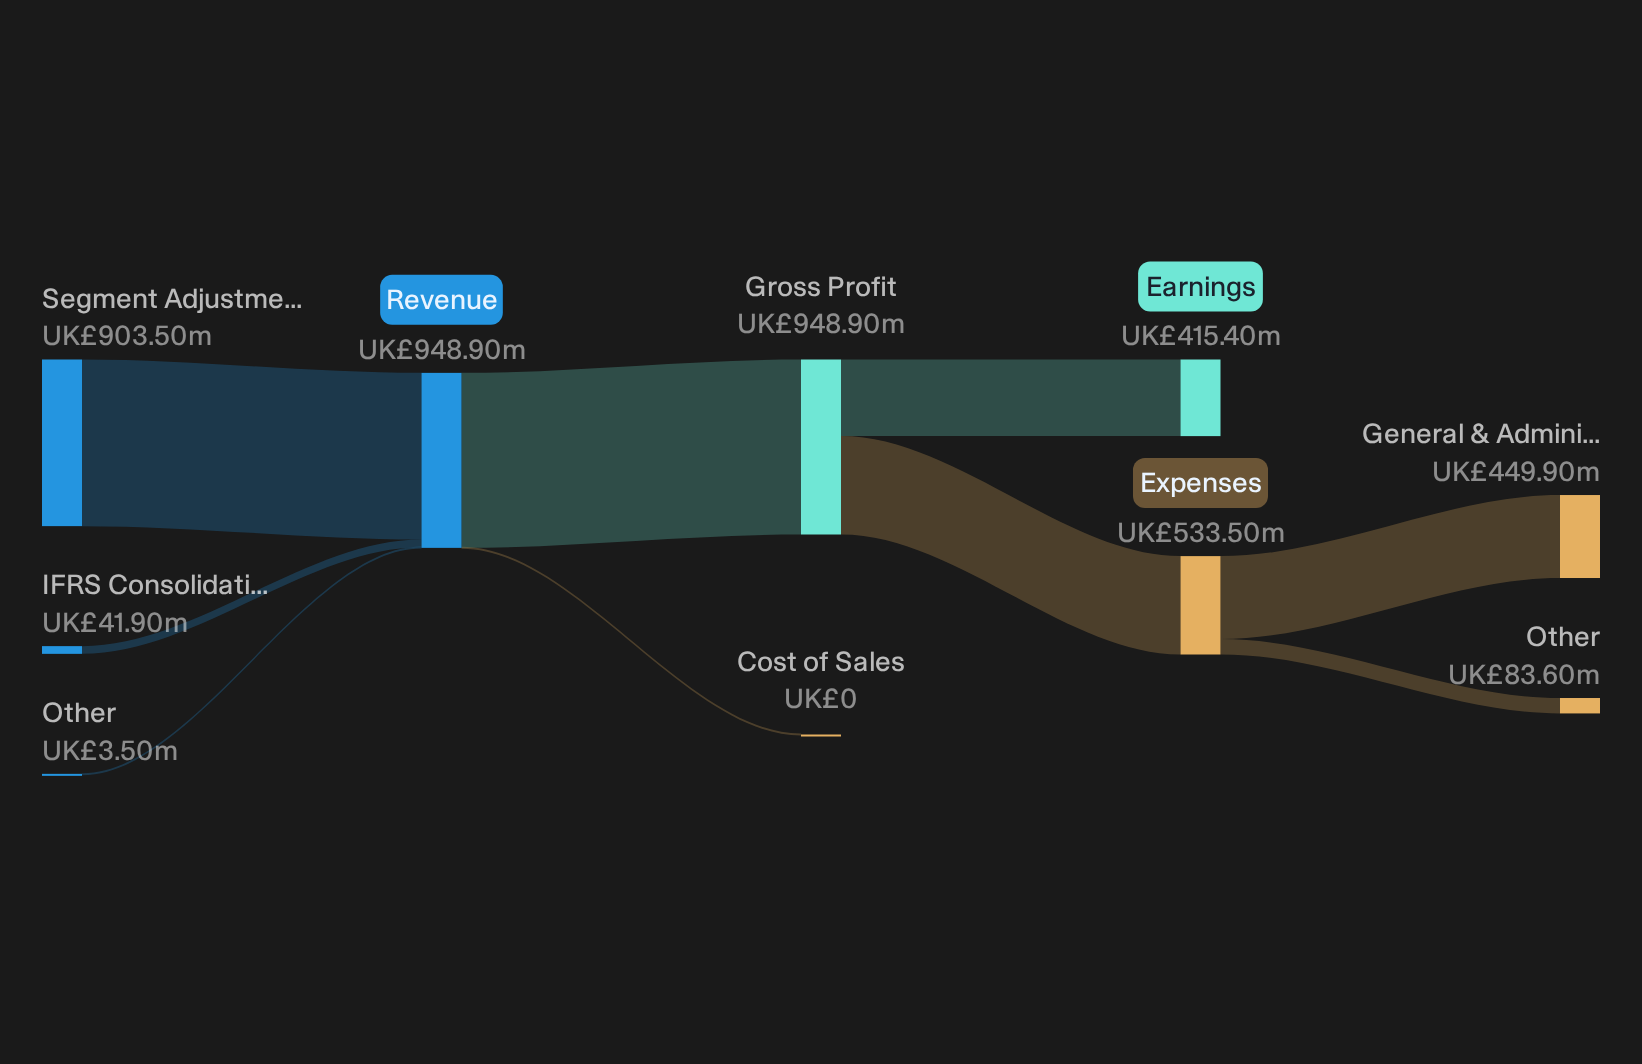
ICG manages private equity and private credit portfolios for institutions, earning fee income from a complex mix of direct and fund of funds strategies, with reported segment adjustments of about £903 million feeding into that model, and the stock carries a market value near £5.0b.
The bearish analyst Narrative on Simply Wall St frames the trade off like this.
"Although the tilt towards higher returning strategies in structured capital, secondaries and real assets has lifted the weighted average management fee rate to 98 basis points and fee related earnings to £350m with a 47% margin excluding catch up fees, the move into more complex, higher barrier products increases execution risk."
What happens if that complexity interacts with one unresolved pressure in private markets could end up steering where ICG’s margins settle.
That unresolved pressure is exactly where ICG’s story could start to pivot, and the full narrative for ICG maps how current complexity might be masking future fee power.
Curious About What You Might Be Missing?
Fresh ideas move first. While attention clusters on today’s headlines, under the radar stocks can build breakout momentum before the crowd even looks. Do not get caught flat footed, act now.
- Target resilient cash generators with the list of solid balance sheet and fundamentals (189 results) so you can focus on businesses where strong finances may help keep opportunities available while it still matters.
- Hunt for income potential using the 245 dividend fortresses and concentrate on higher yielding payout opportunities that others may overlook.
- Focus on AI suppliers through the 53 AI infrastructure stocks and track the companies providing key inputs to data center build outs.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com