


EN
What Comes Next For AeroVironment After A 68% Slide
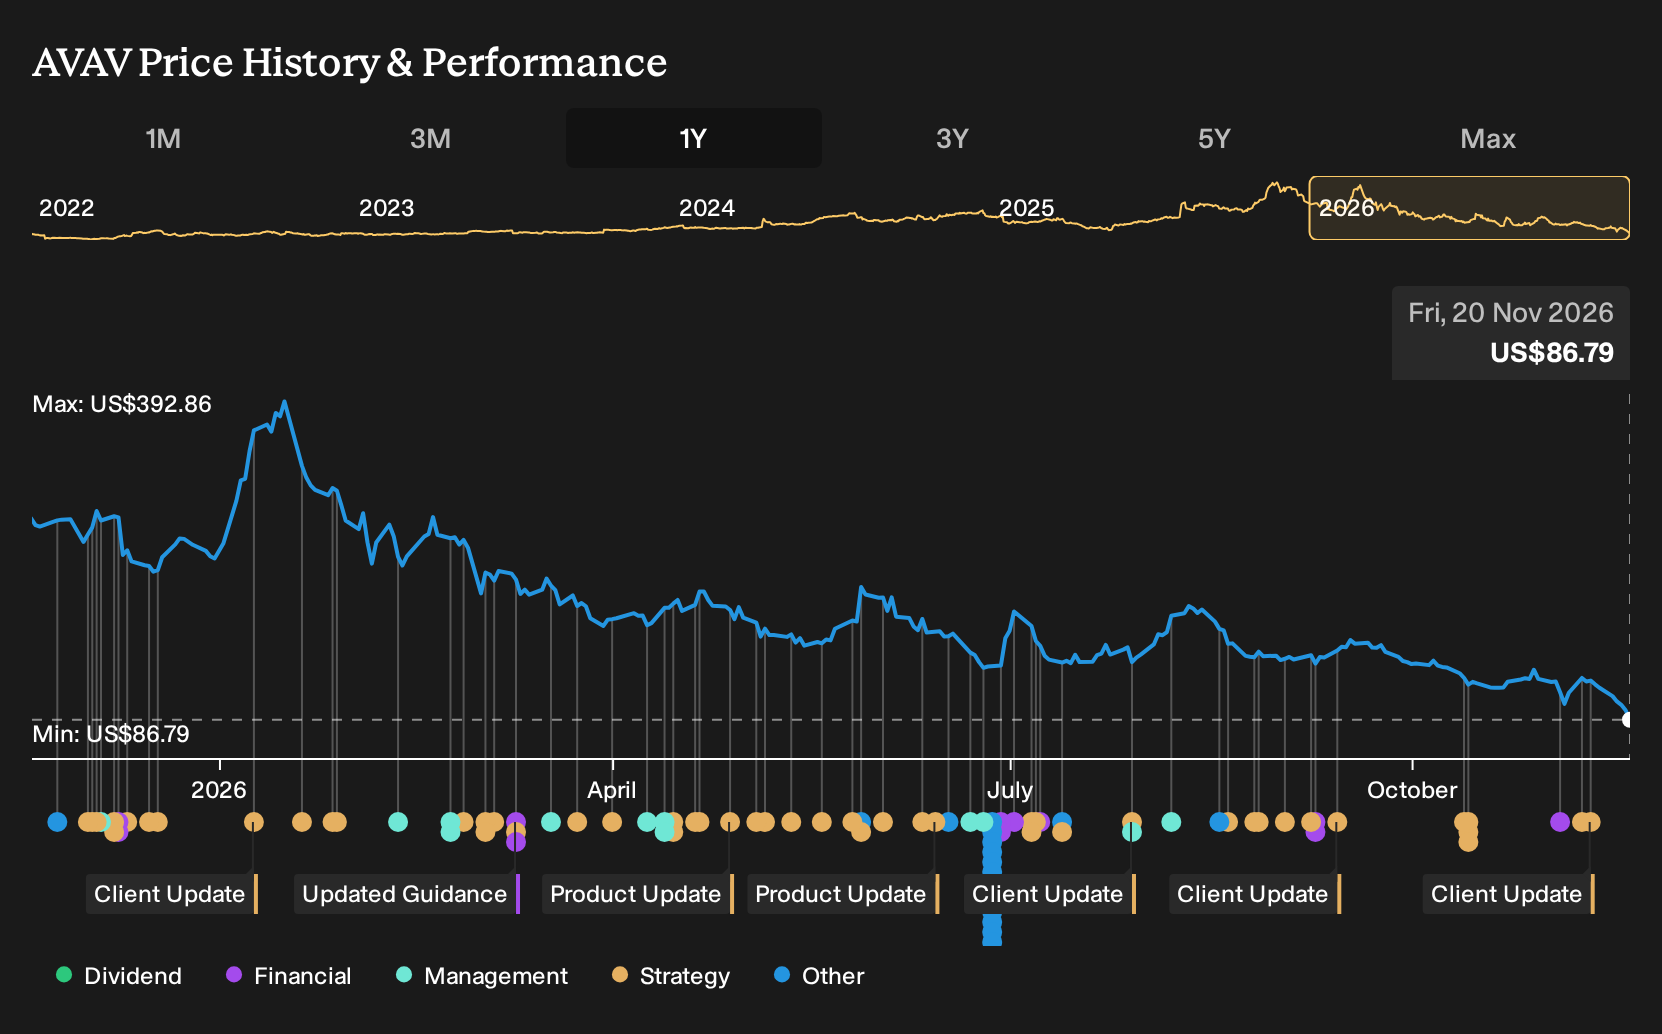
For AeroVironment shareholders, the loss over the past year was 68.2%, including dividends. If you had backed the upbeat November 2025 thesis that expanding defense programs, AV Halo software and the BlueHalo deal would justify a rich future P/E and rapid revenue growth, this outcome hurts. The SCAR contract fallout and lawsuits are now in full view, but what did that original investment case miss about contract concentration, integration risk and accounting controls?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
AeroVironment is not the only name tied to this theme. Zero in on 90 robotics and automation stocks and compare how each one is priced.
The Argument AeroVironment Investors Were Weighing Up
At the start of the period, AeroVironment shares cost US$274, so anyone buying in had to choose between two sharply different stories.
The bullish Narrative saw a Fair Value of US$306, built on assumptions of 36.8% revenue growth, a 9.9% profit margin and a future P/E of 85.1x, all resting on expanding defense programs and successful BlueHalo integration.
The bearish case put Fair Value at US$157 and focused on contract dependence, tighter regulation and export limits, plus the risk that rising competition could pressure margins and make earnings more unpredictable.
What The Evidence Did To The AeroVironment Argument
The SCAR stop work order, contract termination and $89 million goodwill impairment directly challenged the bullish AeroVironment story that downplayed contract and accounting risks. At the same time, Q1 2027 results showed higher revenue of US$480.49 million and a smaller loss, with net margin improving from -14.8% to -1.1%.
For any defence contractor, this episode underlines how much hinges on contract concentration and control quality. When assessing another stock, track how much revenue depends on a single program and compare goodwill, impairments and control findings with earlier claims of durable growth and clean books.
AeroVironment: What You Would Be Paying For Today
AeroVironment now trades at US$86.79, after a 68.2% loss over the past year. The current bullish Narrative’s Fair Value sits above this price, according to LunaRodas, a Simply Wall St Community investor who wrote the Narrative.
The case hinges on achieved contract inflection, not just hope. A buyer today would need to believe current flagship awards can sustain meaningful backlog and revenue contributions beyond the next few quarters.
"The quarter arrived loaded with confirming data (EHEL awarded, LOCUST international sale announced, Titan contract wins stacking). Yet the call’s analytical interest lies less in the headlines than in what shifted underneath them: a narrative architecture built previously around anticipated inflection has now converted to one anchored in achieved inflection, and the pressure to explain why guidance wasn’t raised has become the new center of gravity."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Which Company Could Surprise You Next?
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 43% below our estimate - uses silicon photonics to bridge existing copper connections and future optical links.
- Company 2 - 48% below our estimate - scales a technology-focused small business bank while managing credit costs conservatively.
- Company 3 - 24% below our estimate - expands a money management platform as balances and interest sharing reshape revenue streams.
Those are three of them. See every one of the 40 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com