


EN
TMC The Metals (TMC) Stock Stays Hard To Value After Permit Update
TMC the metals has seen its share price fall sharply this year, which puts a bright spotlight on whether the current market value still lines up with what its balance sheet can support. For anyone tracking the critical minerals story, the immediate question is how that drop squares with what the company’s book value suggests the stock might be worth.
- The share price is down 77.6% year to date, which raises the stakes for judging whether the remaining market value is adequately backed by the company’s net assets.
- Recent updates around its Commercial Recovery Permit process and capital light plans with Allseas may influence how investors think about future project funding needs and the resilience of its asset base.
- Your read on TMC the metals is one view; the desks covering it have another. See what analysts think TMC the metals's shares could be worth.
The stock’s next move may depend on whether TMC the metals’ current price can be squared with what its book value signals about the strength of its underlying equity.
If you are weighing TMC the metals against other critical materials opportunities, it can help to see how it compares with 30 best rare earth metal stocks.
Where Does TMC the metals Sit on Book Value?
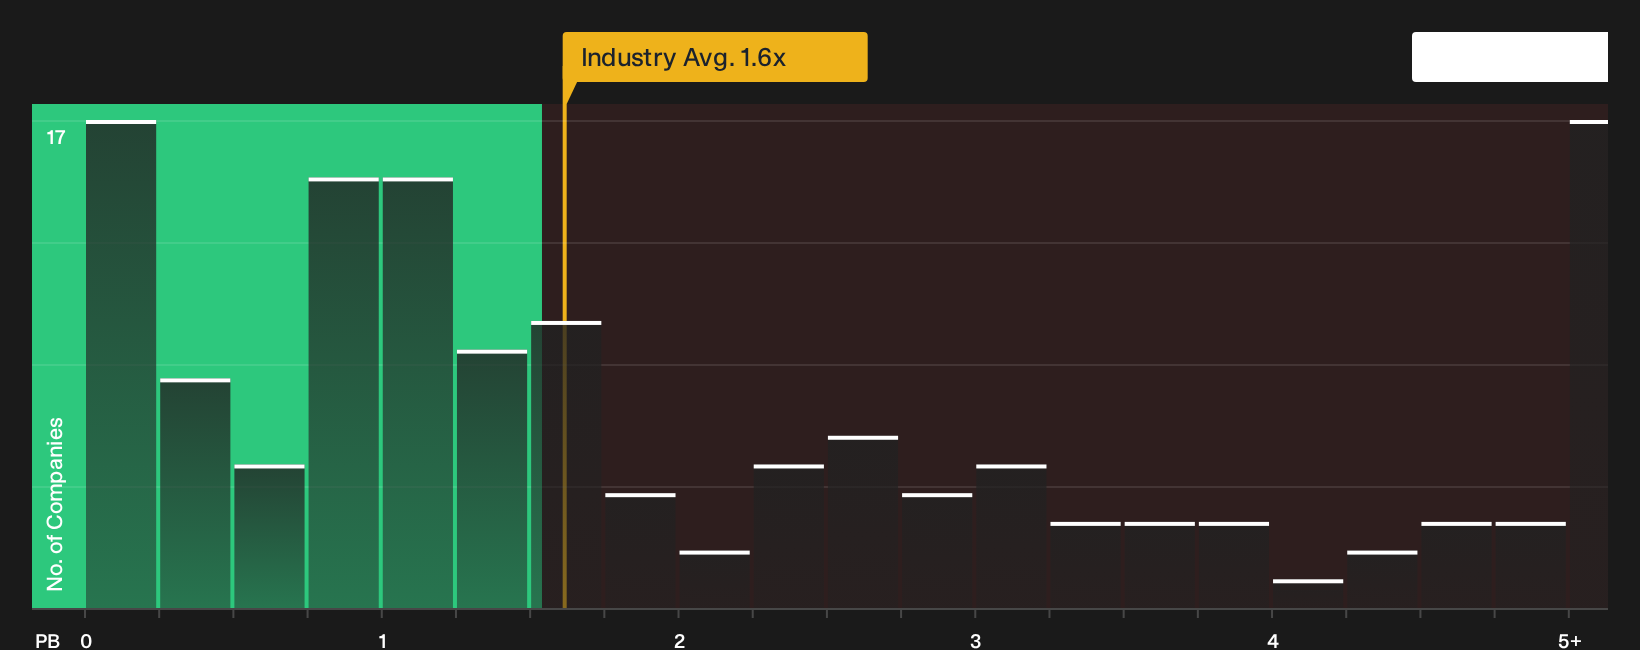
P/B fits TMC the metals because investors are effectively paying for a pool of seabed resource rights and related assets rather than established earnings. The current P/B sits at 15.3x, but the figure is negative because shareholder equity is negative, so the ratio flips sign and stops being a clean “price versus net assets” yardstick. There is no positive book value to anchor the share price to, so the headline multiple no longer tells you whether the market is paying a premium or discount to the balance sheet.
Because the latest corporate update highlights efforts to reduce upfront capital needs with Allseas, you need to judge TMC the metals mainly on future funding, project execution and regulatory progress rather than this distorted P/B. The negative equity position means balance sheet risk and dilution potential sit at the center of the story, and the quoted P/B ratio cannot by itself answer whether today’s valuation is demanding or conservative for that risk profile. With this multiple ruled out, take a closer look at what TMC the metals's balance sheet and debt position show instead.
The TMC the metals Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/B puzzle leaves off for TMC the metals' shares by spelling out which expectations on future growth, margins and earnings would need to hold for the current price to look materially high or low. Each scenario links its number to a clear view on how TMC the metals' potential growth, profitability and project risks might evolve, which gives you something concrete to revisit as fresh information becomes available on the Community page.
One of the top narratives on TMC the metals: 84% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The pre feasibility study and initial assessment outline a large resource with an estimated combined NPV of US$23.6b, targeted steady state revenue of about US$600 per dry ton…"
Discover why this Narrative puts TMC the metals at 84% undervalued.
Before You Decide On TMC the metals, There Is One More Angle To Check
Balance sheets and project stories only go so far, because professional estimates for where this business might be a few years from now give you a separate reference point to weigh against today's price. Explore where analysts expect TMC the metals to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com