


EN
Is Datadog (DDOG) Undervalued Following Its Cautious Outlook On AI Customer Spending?
Why Datadog’s cautious tone matters for investors now
Datadog (DDOG) has become a talking point after pairing strong quarterly revenue growth with a more cautious outlook tied to its largest AI customer and renewal discounts. This has shifted how some investors frame the stock’s risk profile.
The cautious tone has landed hard in the chart. Datadog’s share price has fallen 38.94% over the past 30 days and 33.21% over 90 days, even though the year-to-date share price return is still up 17.64%. The 3-year total shareholder return of 39.43% contrasts with a slightly negative 1-year total shareholder return of 0.11%. This pattern may hint at fading momentum as investors reassess growth against customer concentration risk.
Compare Datadog’s reset expectations with other AI infrastructure players by scanning our hand picked 53 AI infrastructure stocks that are also exposed to big spending shifts from major customers.
Datadog now trades after a sharp reset rather than a clean victory lap. For investors weighing upside, how much of the story is still reflected in the valuation, and how much is already in the rear view mirror?
Most Popular Narrative: 42% Undervalued
Datadog’s last close at $157.37 sits well below the analyst consensus Narrative fair value of $271.71, which is built using a discount rate of 8.45% and long term revenue and earnings forecasts from the analyst consensus Narrative on Simply Wall St.
Expanding AI workloads, with over 750 AI customers including all 10 of the top AI leaders and growing use cases such as GPU monitoring, Agent Observability, AI Guard and Bits AI, can support higher observability and security spend per customer and feed Datadog revenue growth over time.
See why 184 investors see Datadog as 42% undervalued.
Result: Fair Value of $271.71 (UNDERVALUED)
Still, if Datadog’s largest AI customer trims usage further or insider selling remains heavy, that could quickly challenge the current view that the stock is 42% undervalued.
Find out about the key risks to this Datadog narrative.
Another View: What Datadog’s P/S Multiple Is Telling You
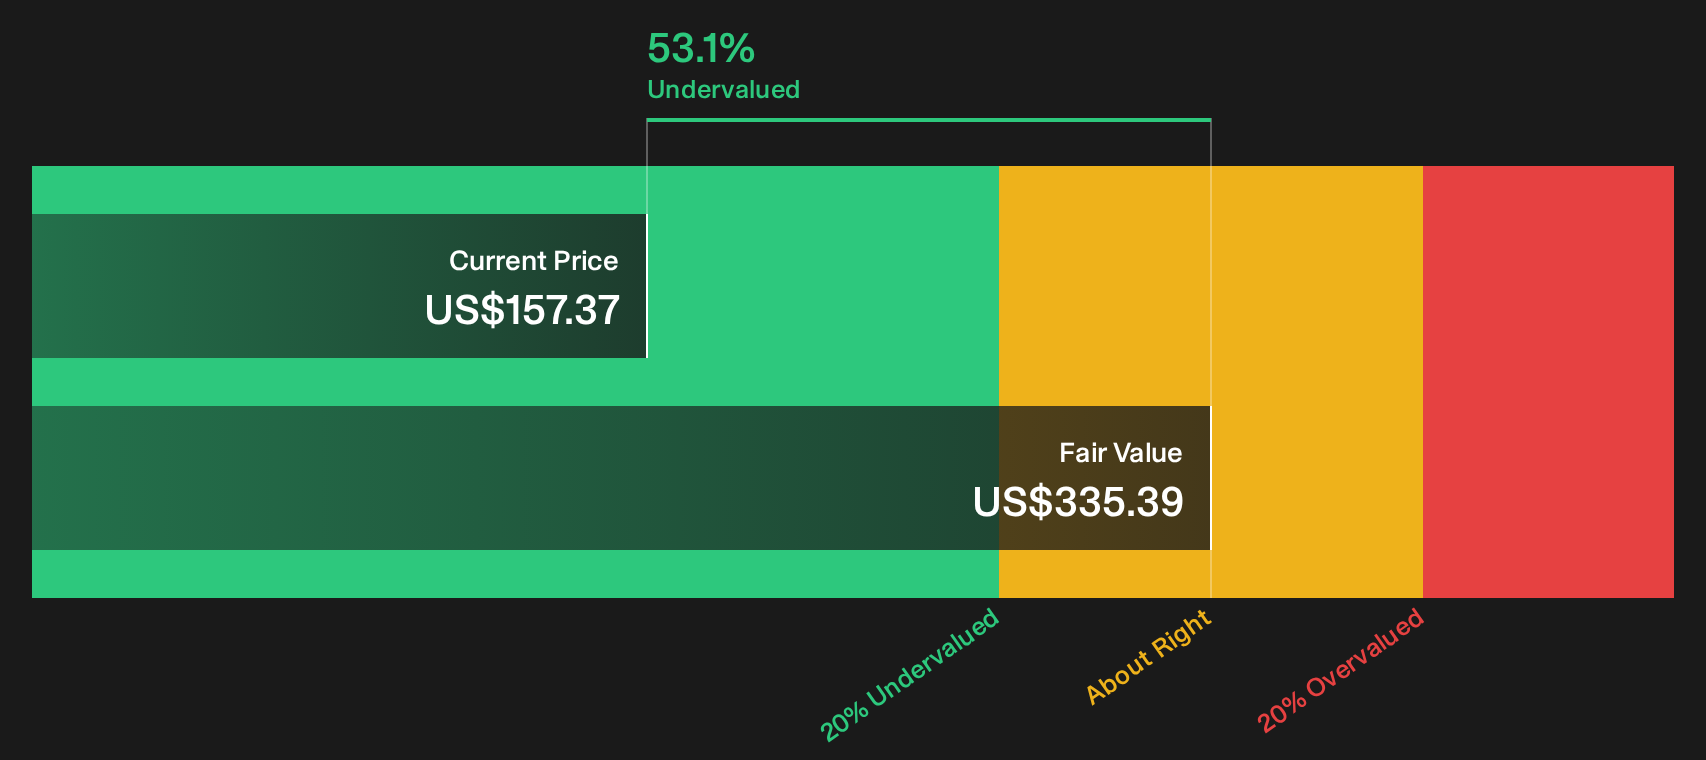
The DCF workup points to Datadog trading 53.1% below an estimated future cash flow value of $335.39, yet the market is already charging a rich P/S of 13.3x. That compares with 7.6x for peers and 3.2x for the wider US Software group, and even sits above a fair ratio of 12.8x. Is this a discount to cash flows, or a premium headline multiple that needs a lot to go right?
To see how this cash flow view is built and where the pressure points sit, Look into how the SWS DCF model arrives at its fair value.
Next Steps
There are mixed views about the tone of Datadog so far. Move quickly from the headline takes to your own view by weighing both the risks and the upside case in 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Datadog?
If Datadog has sharpened your focus on quality, broaden your opportunity set and let data driven filters surface stocks that better fit your risk and return goals.
- Target potential bargains by scanning a curated 40 high quality undervalued stocks that screens for quality businesses priced below their assessed worth.
- Prioritize resilience by reviewing a 32 resilient stocks with low risk scores that highlights companies with lower risk scores for steadier portfolio anchors.
- Strengthen your core holdings by using the list of solid balance sheet and fundamentals (24 results) to spot financially robust companies with fundamentals designed to handle tougher conditions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com