


EN
Companies Like Thesis Gold & Silver (CVE:TAU) Are In A Position To Invest In Growth
Just because a business does not make any money, does not mean that the stock will go down. For example, although Amazon.com made losses for many years after listing, if you had bought and held the shares since 1999, you would have made a fortune. Nonetheless, only a fool would ignore the risk that a loss making company burns through its cash too quickly.
So should Thesis Gold & Silver (CVE:TAU) shareholders be worried about its cash burn? For the purpose of this article, we'll define cash burn as the amount of cash the company is spending each year to fund its growth (also called its negative free cash flow). The first step is to compare its cash burn with its cash reserves, to give us its 'cash runway'.
How Long Is Thesis Gold & Silver's Cash Runway?
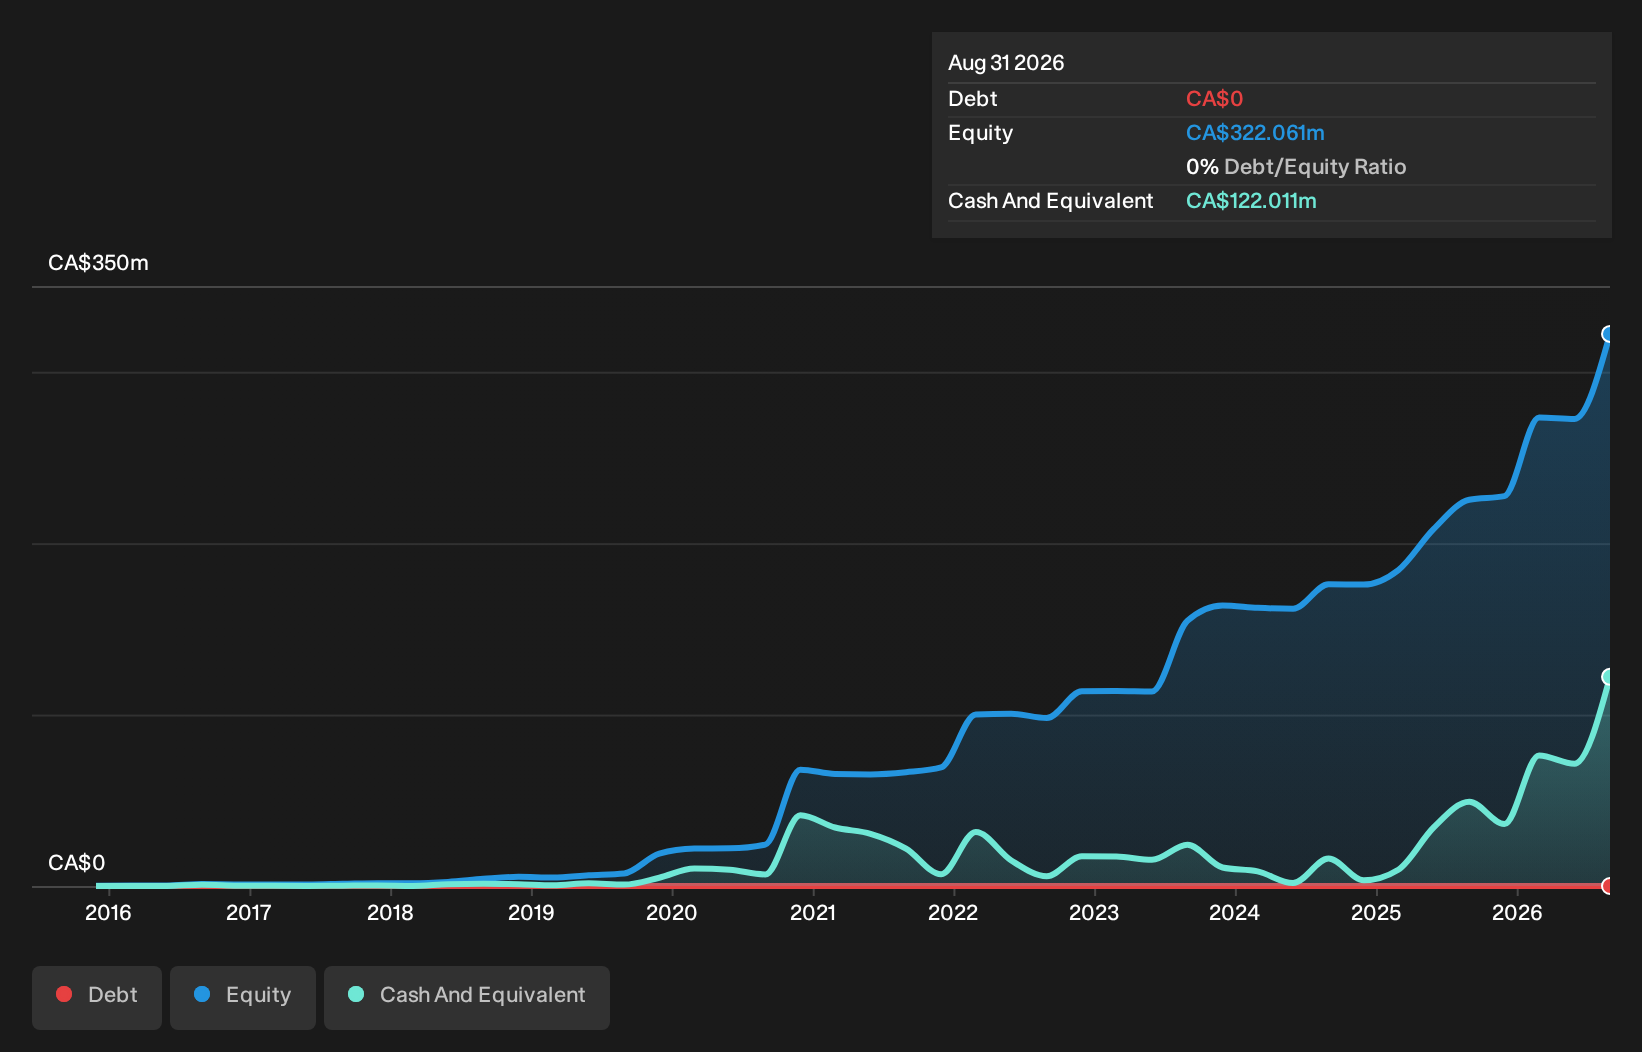
A company's cash runway is calculated by dividing its cash hoard by its cash burn. In August 2026, Thesis Gold & Silver had CA$122m in cash, and was debt-free. In the last year, its cash burn was CA$39m. That means it had a cash runway of about 3.2 years as of August 2026. Notably, analysts forecast that Thesis Gold & Silver will break even (at a free cash flow level) in about 4 years. Essentially, that means the company will either reduce its cash burn, or else require more cash. You can see how its cash balance has changed over time in the image below.
View our latest analysis for Thesis Gold & Silver
How Is Thesis Gold & Silver's Cash Burn Changing Over Time?
Thesis Gold & Silver didn't record any revenue over the last year, indicating that it's an early stage company still developing its business. Nonetheless, we can still examine its cash burn trajectory as part of our assessment of its cash burn situation. With the cash burn rate up 28% in the last year, it seems that the company is ratcheting up investment in the business over time. However, the company's true cash runway will therefore be shorter than suggested above, if spending continues to increase. Clearly, however, the crucial factor is whether the company will grow its business going forward. So you might want to take a peek at how much the company is expected to grow in the next few years.
How Easily Can Thesis Gold & Silver Raise Cash?
Given its cash burn trajectory, Thesis Gold & Silver shareholders may wish to consider how easily it could raise more cash, despite its solid cash runway. Companies can raise capital through either debt or equity. Many companies end up issuing new shares to fund future growth. We can compare a company's cash burn to its market capitalisation to get a sense for how many new shares a company would have to issue to fund one year's operations.
Thesis Gold & Silver has a market capitalisation of CA$551m and burnt through CA$39m last year, which is 7.0% of the company's market value. That's a low proportion, so we figure the company would be able to raise more cash to fund growth, with a little dilution, or even to simply borrow some money.
So, Should We Worry About Thesis Gold & Silver's Cash Burn?
As you can probably tell by now, we're not too worried about Thesis Gold & Silver's cash burn. For example, we think its cash runway suggests that the company is on a good path. While its increasing cash burn wasn't great, the other factors mentioned in this article more than make up for weakness on that measure. One real positive is that analysts are forecasting that the company will reach breakeven. Looking at all the measures in this article, together, we're not worried about its rate of cash burn; the company seems well on top of its medium-term spending needs. On another note, Thesis Gold & Silver has 3 warning signs (and 2 which make us uncomfortable) we think you should know about.
If you would prefer to check out another company with better fundamentals, then do not miss this free list of interesting companies, that have HIGH return on equity and low debt or this list of stocks which are all forecast to grow.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.