


EN
KKR (KKR) Expands In Offshore Wind, Is The Stock Still A Bargain?
KKR’s offshore wind joint venture puts renewables in focus
KKR (KKR) has moved deeper into renewable infrastructure through a 50:50 joint venture with RWE AG on the Vanguard West and Vanguard East offshore wind projects in the British North Sea.
Despite the renewable push, KKR’s recent share price performance has been weak, with the stock down 3.9% on the day and the 90 day share price return falling 18.4%, even though the 3 year total shareholder return is still positive at 30.5%.
That loss of momentum comes after a busy few weeks, including stronger third quarter earnings, a fresh dividend declaration, new renewable investments in India and now a large offshore wind joint venture in the UK. Taken together, these developments indicate that investors are reassessing both growth prospects and risk around the current US$88.54 share price.
Spot opportunities beyond KKR’s recent pullback and offshore wind push by scanning a curated 40 high quality undervalued stocks that may be primed for their own next leg higher.The pullback leaves KKR at US$88.54 while analyst targets and intrinsic estimates point much higher. Is this simply pessimism overshooting, or are those valuation anchors too optimistic?
Most Popular Narrative: 27% Undervalued
On the analyst consensus Narrative on Simply Wall St, KKR’s fair value sits at $120.57 compared with the current $88.54 share price. This frames the recent weakness as a sizeable discount while still tying everything back to revenue and earnings forecasts built into that model.
Strong and accelerating fundraising momentum across asset classes, especially with institutional investors and the fast-growing private wealth/retail segment, are expanding fee-paying AUM and supporting double-digit management fee growth, with further upside from new distribution initiatives (e.g., partnership with Capital Group and insurance third-party capital). This is likely to positively impact future revenue and management fees.
See why 53 investors see KKR as 27% undervalued.
Analysts using that framework arrive at a discount rate of 9.22%, which is the hurdle rate applied to KKR’s projected cash flows and earnings path. Those same assumptions incorporate expectations for declining reported revenue but materially higher modeled profit margins and earnings over time. This is why the valuation outcome can still point to a higher fair value even as top line forecasts soften.
The same Narrative acknowledges that this is not a one way story. It highlights risks around asset based finance exposure, competition in alternatives, reliance on carried interest, and expansion into more volatile regions. All of these factors could make realized outcomes diverge from the modeled fair value of $120.57.
Result: Fair Value of $120.57 (UNDERVALUED)
Still, if fundraising slows or asset based finance exposures sour, then the KKR narrative built around fee stability and higher modeled margins could crack quickly.
Find out about the key risks to this KKR narrative.
Another View: KKR Through A Cash Flow Lens
The analyst Narrative frames KKR as 27% undervalued at $120.57, yet our DCF model lands in a very different place. On future cash flows, KKR at $88.54 trades above an estimated value of $72.43, which points to the shares looking expensive rather than cheap. Which lens do you trust more when the story splits like this?
Look into how the SWS DCF model arrives at its fair value.
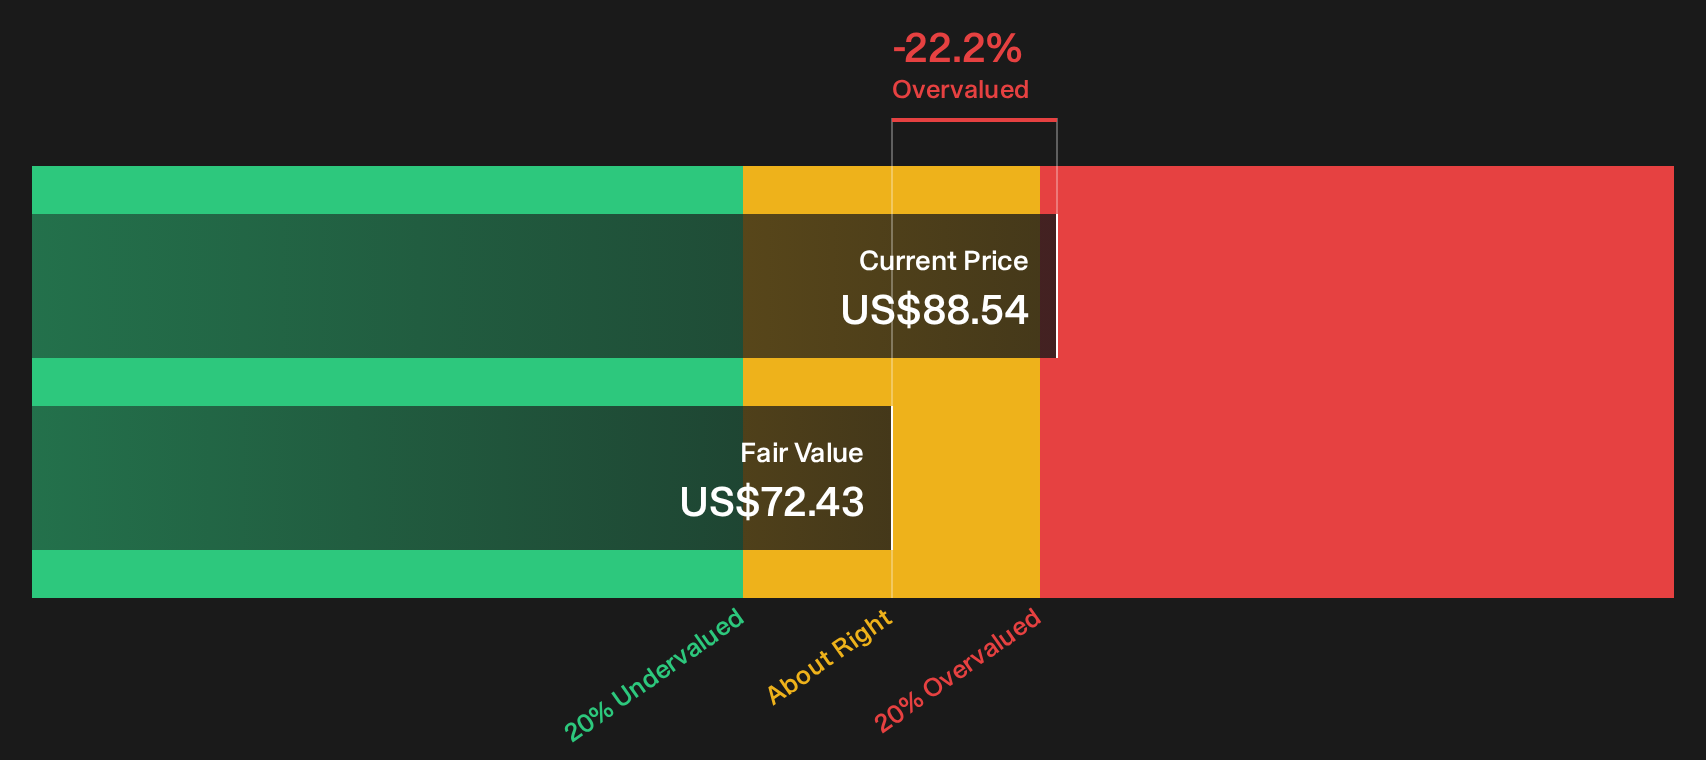
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out KKR for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 40 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicted by the mixed signals around KKR and its valuation tug of war today. Consider acting promptly to test the assumptions yourself and weigh the potential upside case in the context of 4 key rewards.
Looking for more investment ideas beyond KKR?
If KKR’s mixed signals have you thinking more broadly, widen your opportunity set now and let a focused screener surface candidates that better fit your plan.
- Target potential mispricing by reviewing a curated 40 high quality undervalued stocks that filters for quality businesses trading below their estimated worth.
- Prioritize resilience by scanning a list of solid balance sheet and fundamentals (24 results) that highlights companies with stronger financial footing.
- Hunt for early-stage potential with a 11 elite penny stocks with strong financials that zeroes in on smaller stocks backed by healthier fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com