


EN
How Investors May Respond To Clorox (CLX) Thin Dividend Coverage
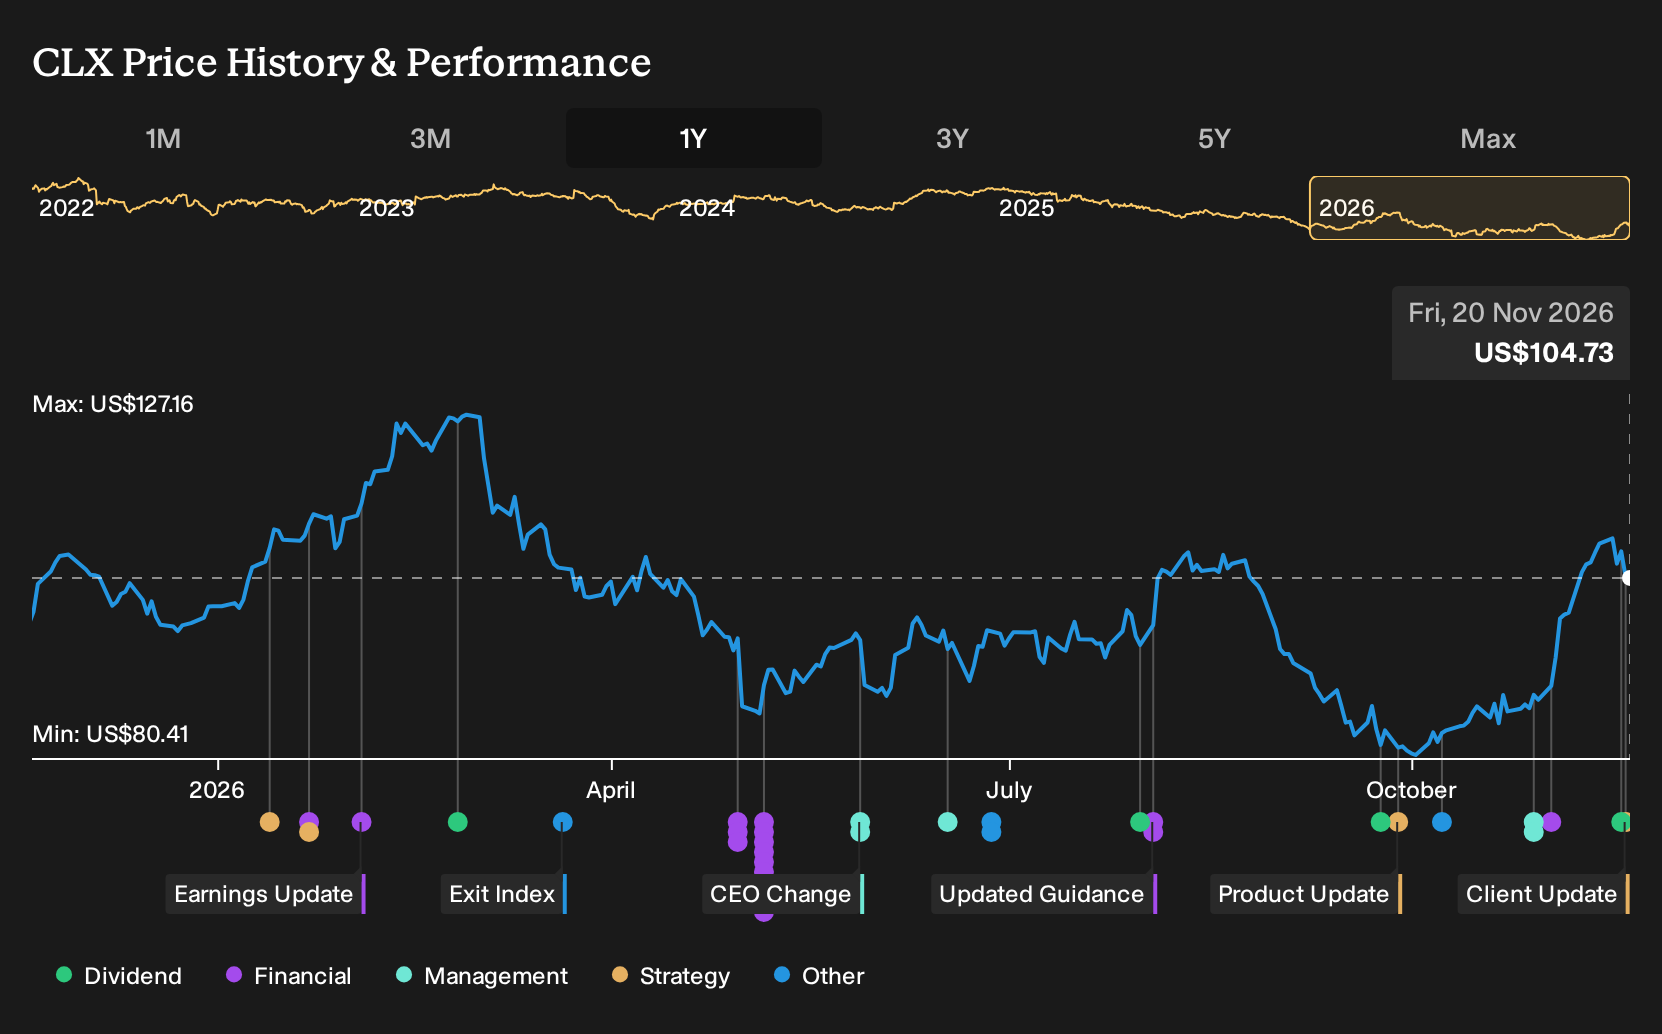
- Clorox reported that shareholders at its November 18, 2026 virtual annual meeting ratified Ernst & Young LLP as independent auditor and the board declared a US$1.25 quarterly dividend payable on February 12, 2027 to holders of record on January 27, 2027.
- The declared payout comes as Clorox's dividend has recently exceeded free cash flow at about 133%, which points to pressure on cash generation while a new CEO prepares to take charge in January 2027.
- The focus now turns to how Clorox's stretched dividend coverage shapes the broader investment narrative and what that might mean for investors.
Scan how Clorox's stretched payout compares with other income ideas by reviewing our hand-picked 8 dividend fortresses built for dividend-focused investors who watch cash coverage closely.
Clorox Investment Narrative Recap
To own Clorox, you effectively need to believe the health and hygiene focus, ERP optimization and GOJO integration described in the analyst consensus Narrative on Simply Wall St can support steady earnings while consumers keep trading down and shopping club and mass channels. The biggest near term swing factor remains how quickly productivity and mix help margins cope with over US$200 million of forecast cost inflation.
The key risk right now is cash generation. Dividend payouts are running at about 133% of free cash flow and roughly 85% to 90% of net earnings, which tightens room to invest while servicing debt that is not well covered by operating cash flow. If margin rebuilding stalls, capital allocation options narrow.
The US$1.25 quarterly dividend affirmation is the clearest touchpoint for that cash flow story. It keeps roughly US$600 million of annual dividend commitments in place even as free cash flow coverage remains thin and supply chain and input costs are guided to be significantly above historical levels in fiscal 2027.
For you as an income focused holder, this payout decision keeps the dividend stream intact for now but also concentrates attention on execution under the incoming CEO from January 2027. Progress on ERP benefits, GOJO and broader productivity will be watched closely because they underpin both dividend sustainability and any room to reduce leverage over the next few years.
Clorox's current analyst storyline implies revenues of US$8.1b and earnings of US$789.0 million by 2029, based on forecast revenue growth of 6.3% a year and an earnings increase of about US$202.0 million from US$587.0 million today.
Uncover why Clorox's fair value indicates a 7% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Some of the most cautious analysts focus on dividend risk rather than ERP upside. They were pencilling in about US$8.0b of revenue and US$745.1 million of earnings by 2029 before this Clorox dividend affirmation. Their more pessimistic story shows how sharply opinions can differ, so it can pay to compare several viewpoints.
Explore 7 other Clorox fair value estimates, including one that suggests as much as 26% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Clorox research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Clorox. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Clorox's overall financial health at a glance.
Looking for more investment ideas beyond Clorox?
Once you have a view on Clorox, it can help to widen the lens and compare it with other companies that match your income, quality or risk profile using the Simply Wall St Screener.
- If you want a shortlist of income candidates with higher yields, review our screener of 8 dividend fortresses that keep cash returns front and center.
- If valuation discipline matters most to you, scan the 40 high quality undervalued stocks that pair solid fundamentals with prices that may not fully reflect them.
- If capital preservation sits at the top of your checklist, start with our curated 32 resilient stocks with low risk scores that have more resilient risk profiles by our scoring.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com