


EN
Icahn Enterprises Stock Faces Cash Conversion Questions As Bearish Signals Persist
- Icahn Enterprises has come under pressure as technical indicators continue to flag persistent selling momentum, alongside growing questions about how efficiently the partnership converts reported sales into distributable cash.
- The wide gap between Icahn Enterprises' low P/S ratio and higher sector averages highlights how concerns about capital allocation and cash generation are shaping views of the underlying portfolio businesses.
- Next, the focus turns to how this shift in sentiment around Icahn Enterprises' cash conversion and valuation might reshape the broader investment narrative.
Compare Icahn Enterprises' pressured valuation and cash conversion issues with a curated set of deep-value ideas through the 40 high quality undervalued stocks, which may be pricing in similar concerns or offering cleaner fundamentals.
Icahn Enterprises Investment Narrative Recap
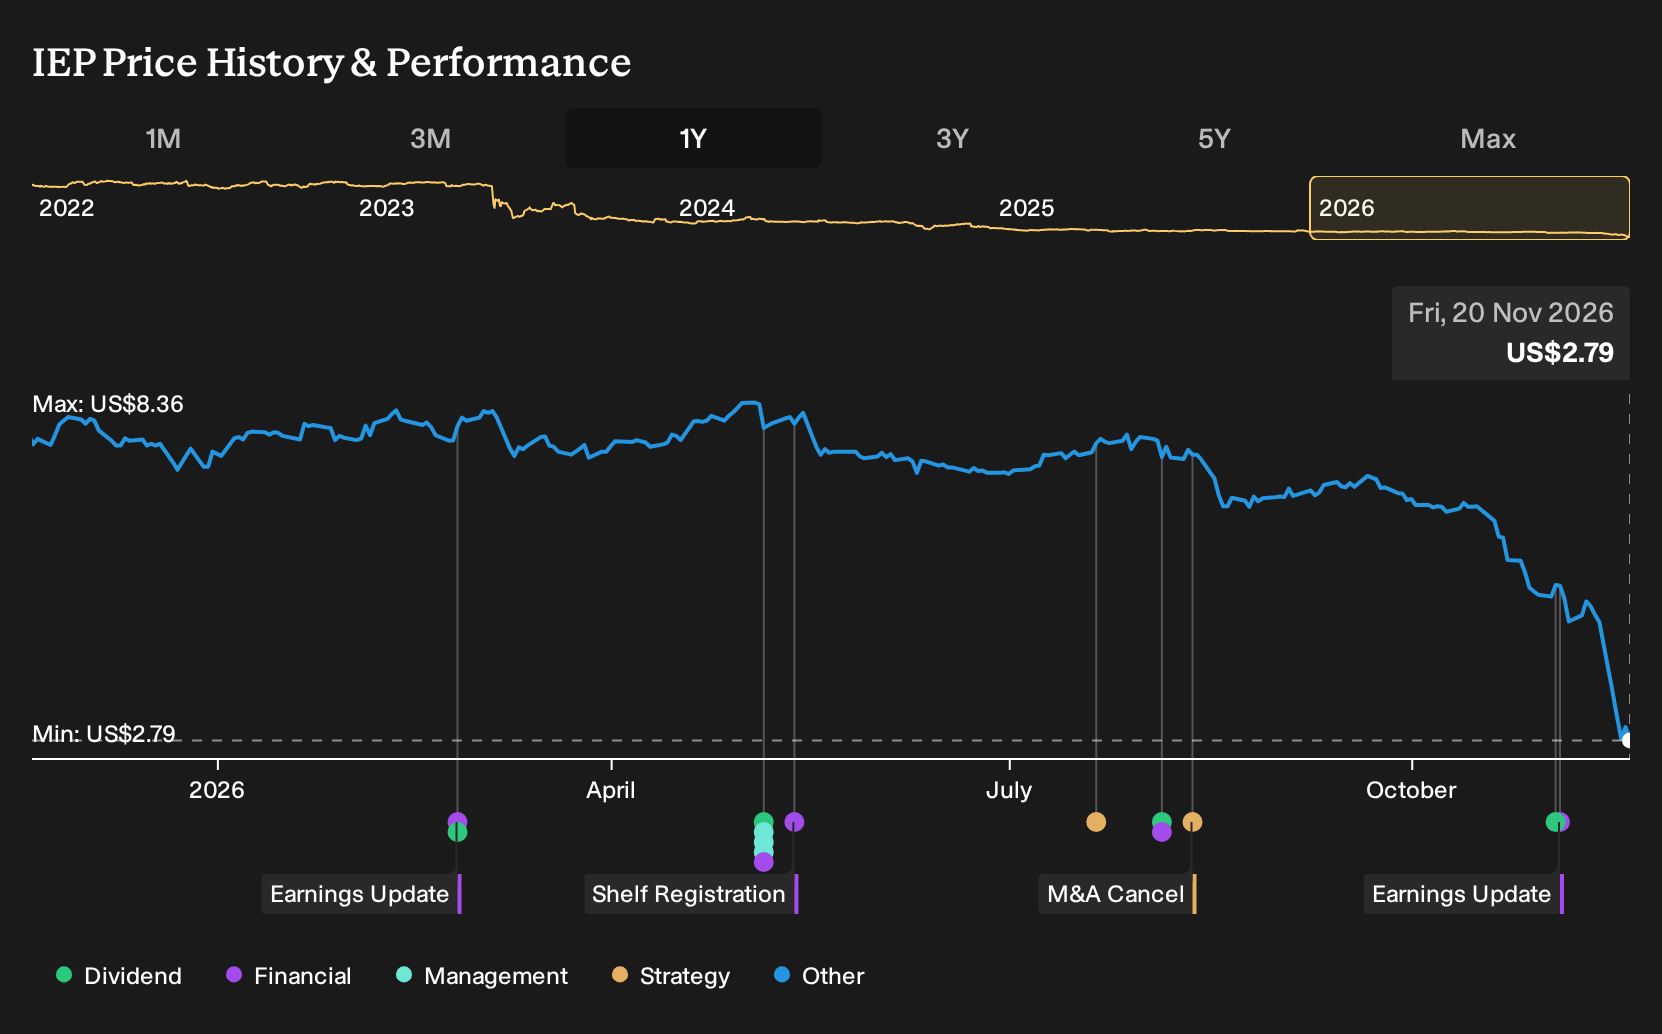
For an investor to stay with Icahn Enterprises, the core belief is that this mix of energy, utilities exposure and turnarounds can eventually translate into stronger cash generation than the current P/S of 0.2x implies. The recent 7.31% single day drop to US$2.79 and negative multi period returns highlight how little patience the market currently has for that story.
The near term catalyst remains execution in the underlying businesses, particularly refining margins, real estate reuse of automotive sites and progress in underperforming segments like food packaging and home fashions. The biggest risk right now is that ongoing losses and weak cash coverage of a 71.68% payout keep straining the balance sheet if operating fixes take longer than hoped.
The analyst consensus Narrative on Simply Wall St points to improving energy fundamentals and data center driven utility exposure as key supports for future distributable earnings. That hinges on crack spreads staying favorable and AI driven power demand supporting holdings such as AEP and Southwest Gas. The latest share price move does not change those drivers, but it does shrink the market value cushion if things disappoint.
On the other side of the ledger, the same narrative flags several pressure points that tie directly into today’s catalyst discussion. Energy profits are sensitive to EPA policy, several controlled businesses are wrestling with lower volumes or competition, and real estate plans depend on a healthy construction and leasing backdrop. With Icahn Enterprises already reporting a loss of US$1,016.0m on US$10,892.0m of revenue, execution on these fronts is what will decide whether the current discount to estimated future cash flow value proves justified.
What The Icahn Enterprises Forecasts Assume
Icahn Enterprises' narrative projects US$9.3b revenue and US$2.2b earnings by 2028. This implies fairly flat top line trends and an earnings increase of about US$2.6b from current earnings of a US$391.0m loss.
Uncover why Icahn Enterprises' fair value indicates a 330% potential upside to its current price, a gap Icahn Enterprises investors may not see remaining open for long.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community cluster between US$9.77 and US$12 per Icahn Enterprises unit, which contrasts sharply with a US$2.79 trading price before the latest drop. As you weigh that gap, consider the risks around refining margins, data center power demand and real estate execution, and compare several viewpoints before deciding what matters most to you.
Explore 3 other Icahn Enterprises fair value estimates, including one that suggests it could be worth just $9.77!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Icahn Enterprises research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Icahn Enterprises. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Icahn Enterprises' overall financial health at a glance.
Looking for more Icahn Enterprises style investment ideas?
Once you have formed a view on Icahn Enterprises, it can help to widen the lens and compare it with a broader set of potential opportunities using the Simply Wall St Screener.
- If you want a starting point for potential bargains with strong fundamentals, scan through the 40 high quality undervalued stocks that may already reflect cautious expectations in their pricing.
- For investors who care most about balance sheet strength and financial resilience, filter opportunities using the list of solid balance sheet and fundamentals (24 results) that screens for sturdier funding profiles.
- If you are hunting for lesser known opportunities that still have robust metrics, survey the 18 high quality undiscovered gems that remain off many investors' radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com