


EN
Telix Pharmaceuticals (ASX:TLX) Shares Look Overvalued Against Current Earnings
Telix Pharmaceuticals has given long term holders a strong ride, yet the recent pullback puts fresh focus on a simple question for you as an investor. Do the current earnings of Telix make its share price look well supported or stretched when set against what you are paying today.
- Over the past 5 years the stock has returned 86.2%, which puts real weight on whether the underlying earnings profile can carry that kind of share price journey.
- The business is heavily geared to turning clinical and commercial execution into sustainable profit, so any change in how efficiently revenue converts into earnings may shift what counts as a reasonable entry price.
- There is a second opinion on Telix Pharmaceuticals worth weighing. See what analysts think Telix Pharmaceuticals's shares could be worth.
The issue now is whether Telix Pharmaceuticals' current market value is properly explained by the earnings it is generating today.
If you are considering whether Telix Pharmaceuticals' recent share price pullback leaves its earnings multiple looking elevated or fair, it can be useful to compare that question across 3 high quality undervalued stocks.
Is Telix Pharmaceuticals Getting Expensive on Earnings?
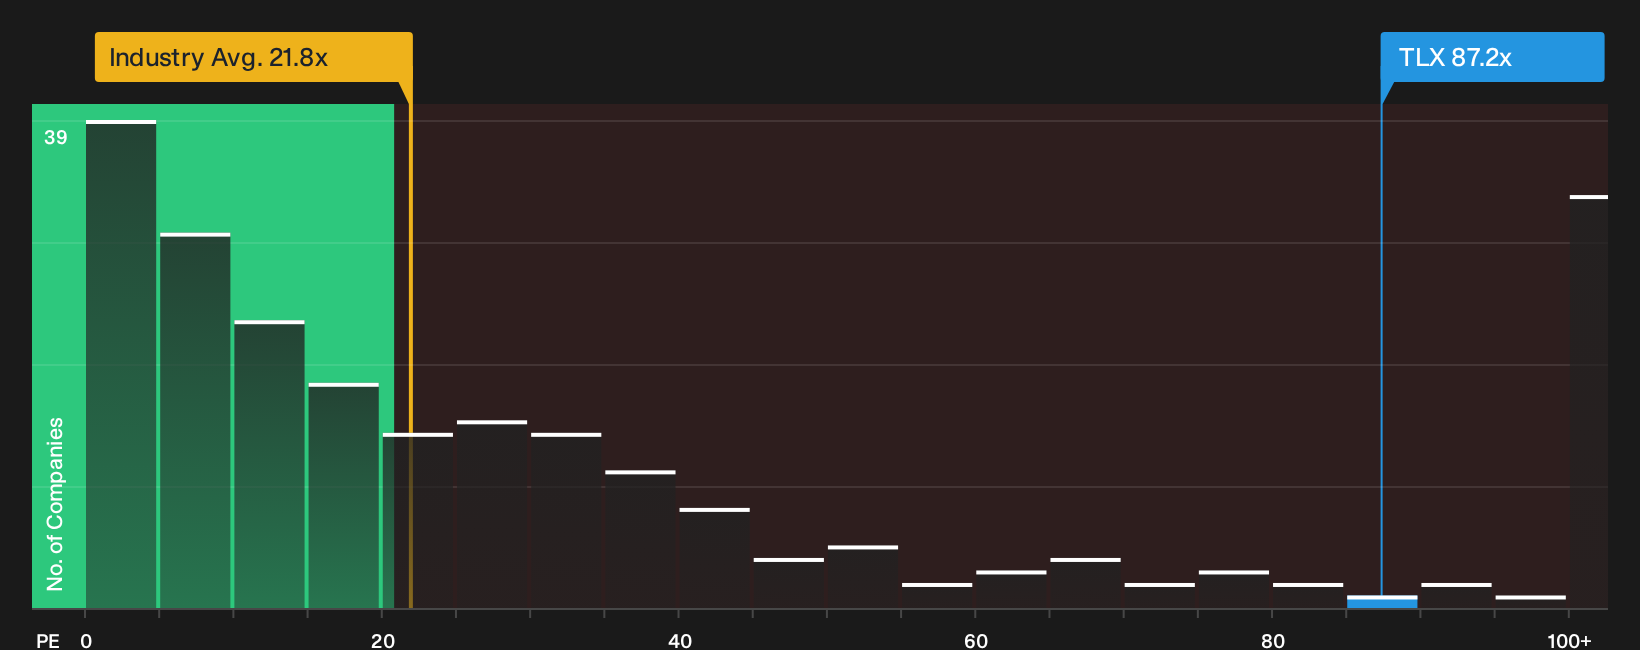
P/E works well for Telix Pharmaceuticals because earnings have become an important reference point for how the market prices its progress. On this lens, the stock trades on a P/E of 87.2x, which is well above the broader Biotechs sector average of 21.8x and also higher than the 51.6x peer group level.
The valuation framework that blends Telix Pharmaceuticals' growth profile, margins, size and risk points to a lower P/E as a more typical anchor. As a result, the current multiple screens as overvalued against that tailored yardstick. For you as a shareholder, the gap means a lot of future execution is already reflected in the P/E. The key question is whether the earnings path you expect makes that premium worthwhile for your own risk tolerance. Explore the numbers behind Telix Pharmaceuticals's P/E valuation.
The Telix Pharmaceuticals Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Telix Pharmaceuticals pick up where the P/E puzzle leaves off by explaining which paths for growth, margins and earnings would need to hold for the stock to be worth materially more or materially less than it is today. Each scenario ties a fair value estimate to a particular mix of potential catalysts and risks so you can track over time which version of events seems to be unfolding.
One of the top community narratives on Telix Pharmaceuticals: 28% undervalued
According to Vallix, a Simply Wall St Community investor who wrote the Narrative, Telix Pharmaceuticals blends a commercial imaging franchise with a higher risk therapeutics pipeline.
"Telix develops and commercialises radiopharmaceutical products, basically, precision imaging agents and therapeutics that help doctors find and eventually destroy tumours..."
Discover why this Narrative puts Telix Pharmaceuticals at 28% undervalued.
The share price is visible, but Telix Pharmaceuticals' leadership choices sit in the background
Before making any long term call on Telix Pharmaceuticals, it helps to look at who is steering the business, how their interests line up with yours, and what that pay structure really looks like. See who runs Telix Pharmaceuticals and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com