


EN
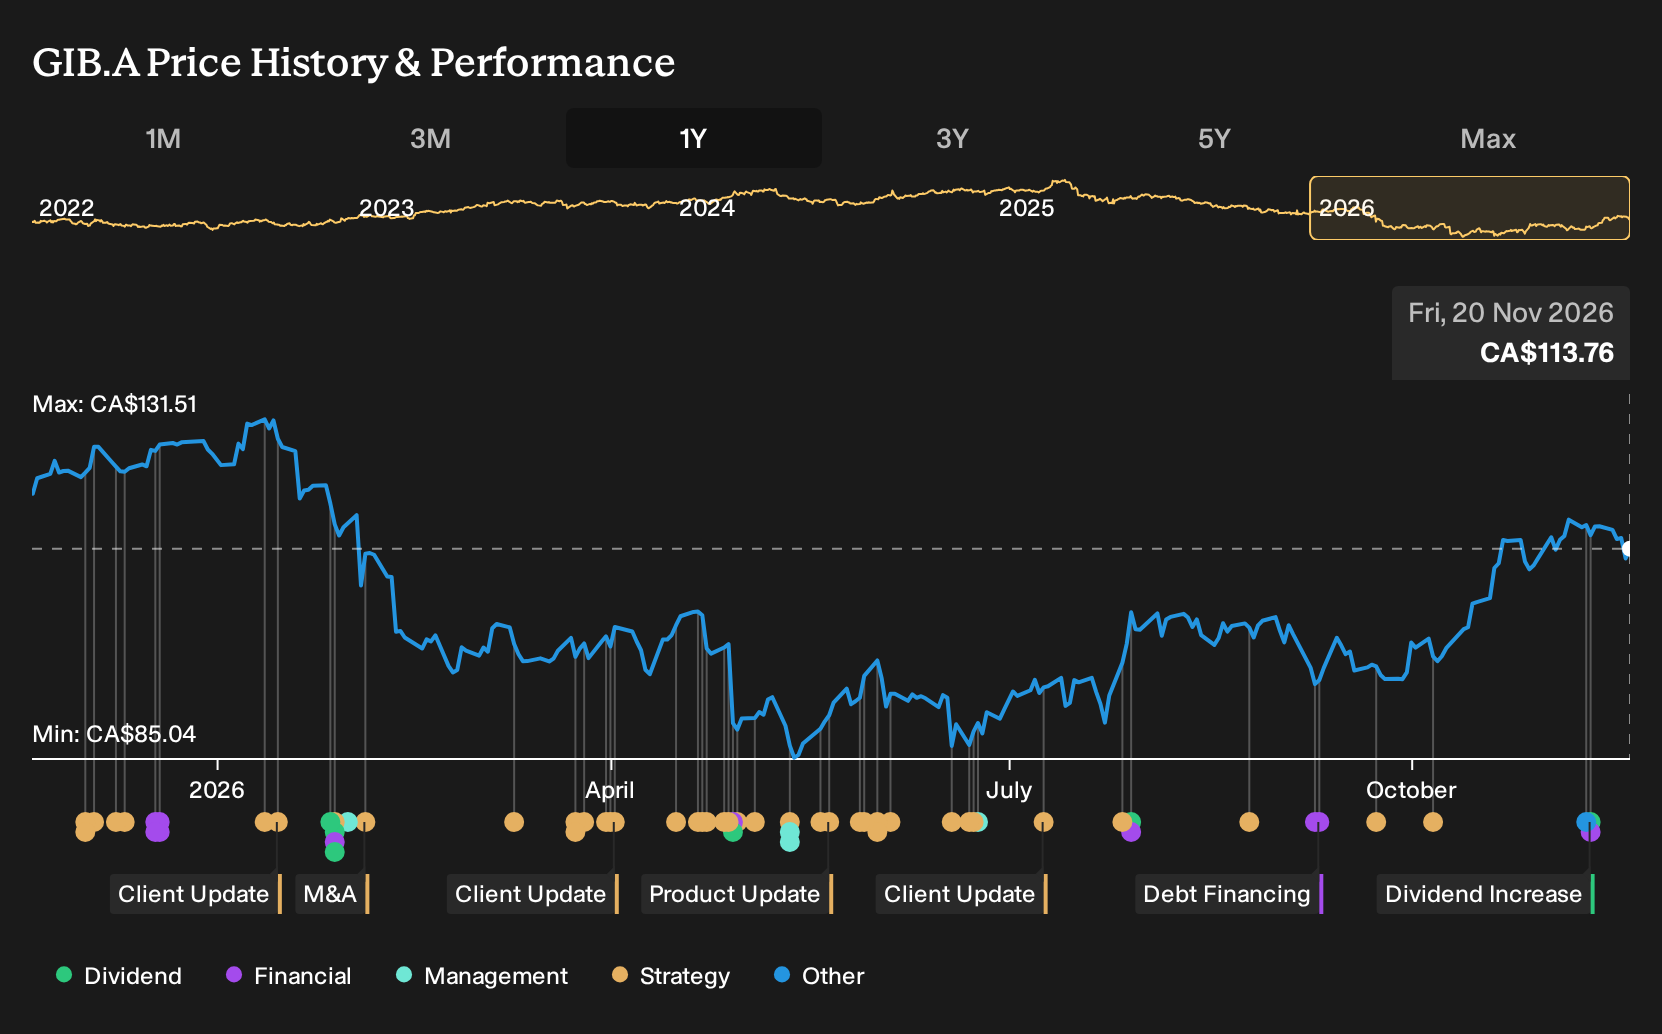
Earnings And Dividend Hike Might Change The Case For Investing In CGI (TSX:GIB.A)
- CGI Inc. reported fourth quarter sales of CA$4,146.1 million and net income of CA$460.7 million, alongside an 8.8% increase in its quarterly dividend to CA$0.185 per share, approved for payment on December 18, 2026 to shareholders of record on November 27, 2026.
- The combination of higher earnings and a larger dividend indicates that CGI is allocating resources to both reinvestment in its technology services business and direct cash returns to shareholders.
- This development provides a basis to examine how CGI's investment narrative is shaped by the higher dividend, stronger earnings and the company’s cash deployment choices.
Scan how CGI's combination of higher earnings, an increased payout, and active buybacks compares with other cash-generative companies. Use the hand picked 3 high quality undervalued stocks as a starting point.
CGI Investment Narrative Recap
To own CGI, you need to believe its core IT services, managed services and IP solutions can keep winning work and turning that backlog into consistent earnings, even as macro conditions stay mixed. The latest results show higher sales, net income and EPS, which supports that operating story. The higher dividend and ongoing buybacks signal management still sees enough cash coming in to fund both reinvestment and shareholder returns.
The near term swing factor remains how quickly large enterprise and government clients approve projects in markets where the analyst consensus Narrative on Simply Wall St already flags slower decision making, especially in parts of Europe. The biggest risk is that budget delays or rebids in those segments mute organic growth, which would make the richer capital return mix less of a support for the investment case.
The dividend increase to CA$0.185 per share sits at the center of this latest update because it interacts directly with cash generation and capital allocation. When you pair that with CA$4,146.1 million in quarterly sales and CA$460.7 million of net income, you get a clearer line of sight into whether earnings can comfortably fund both payouts and reinvestment in areas like AI rich services.
The completed repurchase of 6,078,300 shares for CA$574.63 million adds another layer to the near term catalyst story. Fewer shares can amplify per share metrics if operating performance holds up, although the business still faces the same risks the analyst consensus Narrative on Simply Wall St highlights around tax rates, reliance on large contracts and macro driven delays, which can all affect how powerful those capital returns feel to you as a shareholder.
CGI's narrative projects CA$17.8b revenue and CA$2.2b earnings by 2029. This assumes 2.5% yearly revenue growth and an earnings increase of about CA$400m from CA$1.8b today.
Uncover how CGI's fair value indicates a 12% potential upside to its current price before that discount window narrows.
Exploring Other Perspectives
One bullish twist in the alternate CGI story is the focus on heavier AI and IP investment. The most optimistic analysts were already penciling in revenue of about CA$18.2b and earnings of roughly CA$2.2b by 2029 before this dividend hike and buyback update. You can treat this new cash return news as a prompt to recheck how those pre news forecasts might shift and to compare several different narratives before deciding what seems reasonable to you.
Explore 3 other CGI fair value estimates, including one that suggests as much as 83% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your CGI research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for CGI. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CGI's overall financial health at a glance.
Looking for more CGI investment ideas?
If the CGI story has sharpened your thinking about quality, income and capital returns, you can use the Simply Wall St Screener to hunt for other stocks that fit your own checklist rather than someone else’s.
- Prefer assets that combine strong fundamentals with room for a re rating? Start with a curated pool of 9 high quality undiscovered gems that might not be on every investor’s radar yet.
- If balance sheet strength is non negotiable for you, filter for companies in the list of solid balance sheet and fundamentals (6 results) and focus on those with the financial resilience you want backing your thesis.
- For readers who put risk control first and return second, narrow your search using a 9 resilient stocks with low risk scores that highlights businesses with more measured risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com