


EN
Ramelius Resources (ASX:RMS) Shares Could Trade At A Premium Despite FY26 AGM Growth Targets
Ramelius Resources has delivered a powerful three year share price run, yet the stock has pulled back sharply in recent months. This raises a straightforward question for investors about how well its current price lines up with the earnings it is generating today. With the company highlighting sizeable production ambitions and substantial recent profits, the issue is whether the market is now paying too much attention to the growth story or not enough.
- Ramelius Resources has returned about 120.1% over the past three years. This puts real weight on the question of whether its present earnings base can support that kind of re-rating.
- Management is pointing to higher long term gold output, a focus on higher grade ore and record profitability. This can influence how sustainable current earnings and cash flows may be relative to the recent share price.
- Your read on Ramelius Resources is one view; the desks covering it have another. See what analysts think Ramelius Resources's shares could be worth.
The issue now is whether Ramelius Resources' current share price can be squared with its earnings power once those profits are set against the Fair Ratio benchmark.
If you are weighing Ramelius Resources against other gold names with serious scale, a focused screener of 32 elite gold producer stocks can give you a cleaner comparison set.
Has Ramelius Resources Run Too Far on Earnings?
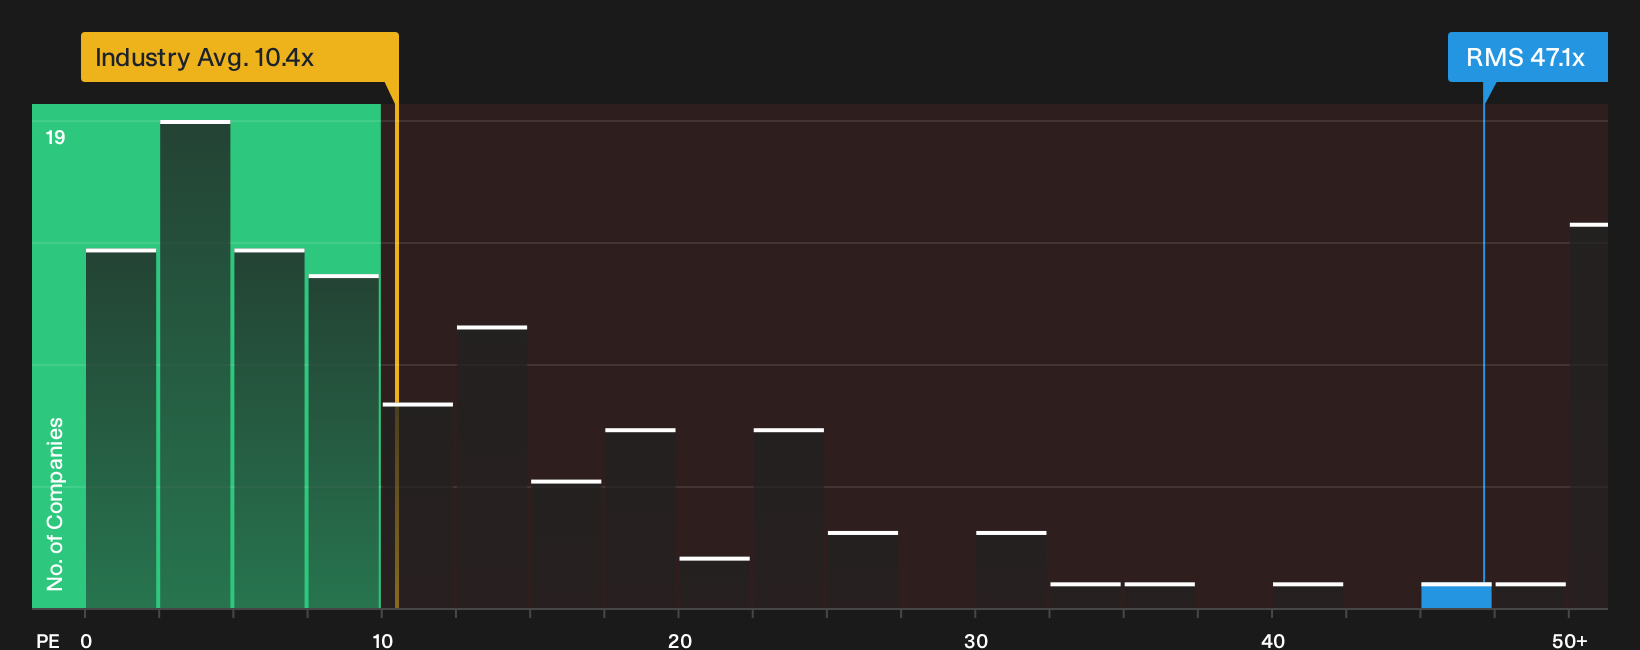
The P/E ratio fits Ramelius Resources because investors often frame gold producers in terms of the profits they generate on each ounce pulled out of the ground. On this yardstick, the stock trades on about 47.1x earnings, which is far above both the broader Metals and Mining sector at roughly 10.4x and the gold peer group near 12.9x. That kind of gap indicates the market is attaching a rich price tag to every dollar of current profit.
The Fair Ratio, which blends Ramelius Resources' growth profile, profitability, size and risk into a tailored benchmark, points to the present P/E being above the level you might expect given those fundamentals. On this framework the shares screen overvalued. Because management is talking about production pushing past 600,000 ounces a year by 2030 and highlighting strong recent earnings, the current multiple already incorporates a lot of confidence that these plans and margins hold together. That leaves you weighing how much execution and gold price risk you are willing to accept for a valuation this full relative to that Fair Ratio reference. Explore the numbers behind Ramelius Resources's P/E valuation.
The Ramelius Resources Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Ramelius Resources pick up where this valuation puzzle leaves off. They spell out in plain terms what would need to happen to future volumes, margins and earnings for the stock to look meaningfully cheaper or more expensive than today. Rather than relying on a single P/E or model output, each scenario lays out the assumptions behind its fair value so you can compare those assumptions with Ramelius Resources' reported results as they arrive on the Community page.
One of the top community narratives on Ramelius Resources: 56% undervalued
According to Robbo, a Simply Wall St Community investor who wrote this Narrative, the investment case for Ramelius Resources focuses on balance sheet strength and optionality.
"Ramelius maintains very low debt levels and a substantial pipeline of projects, with the company still appearing to have a significant war chest to support further growth…"
Discover why this Narrative puts Ramelius Resources at 56% undervalued.
One more angle on Ramelius Resources that could change how you see the price
There is a separate lens on Ramelius Resources that sits outside today’s multiples, because professional analysts have mapped out where they expect this miner to be a few years from now. Explore where analysts expect Ramelius Resources to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com