


EN
Salesforce (CRM) Stock Looks Reasonable After Its 35% Five Year Fall
Salesforce has just gone through a rough patch in the market, and the slide is forcing a fresh look at whether the current share price lines up with what its earnings can reasonably support. For anyone following the stock, the question is not just about sentiment around software and AI, but about what investors are actually paying for the company’s profit stream today.
- Over the past 5 years the stock has declined 35.2%, which puts the focus squarely on whether the earnings profile now on offer justifies the valuation reset.
- Recent headlines around AI competition, government related AI programs and acquisitions such as Contentful and Cresta can influence how investors think about Salesforce’s future profitability, capital needs and the durability of its current earnings base.
- There is a second opinion on Salesforce worth weighing. See what analysts think Salesforce's shares could be worth.
The issue now is whether Salesforce’s current market value is appropriately supported by its earnings when set against the Fair Ratio benchmark.
If this slide in Salesforce has you questioning what you are really paying for earnings, it can help to compare it with 41 high quality undervalued stocks built on similar valuation checks.
Does Salesforce Look Undervalued on Earnings?
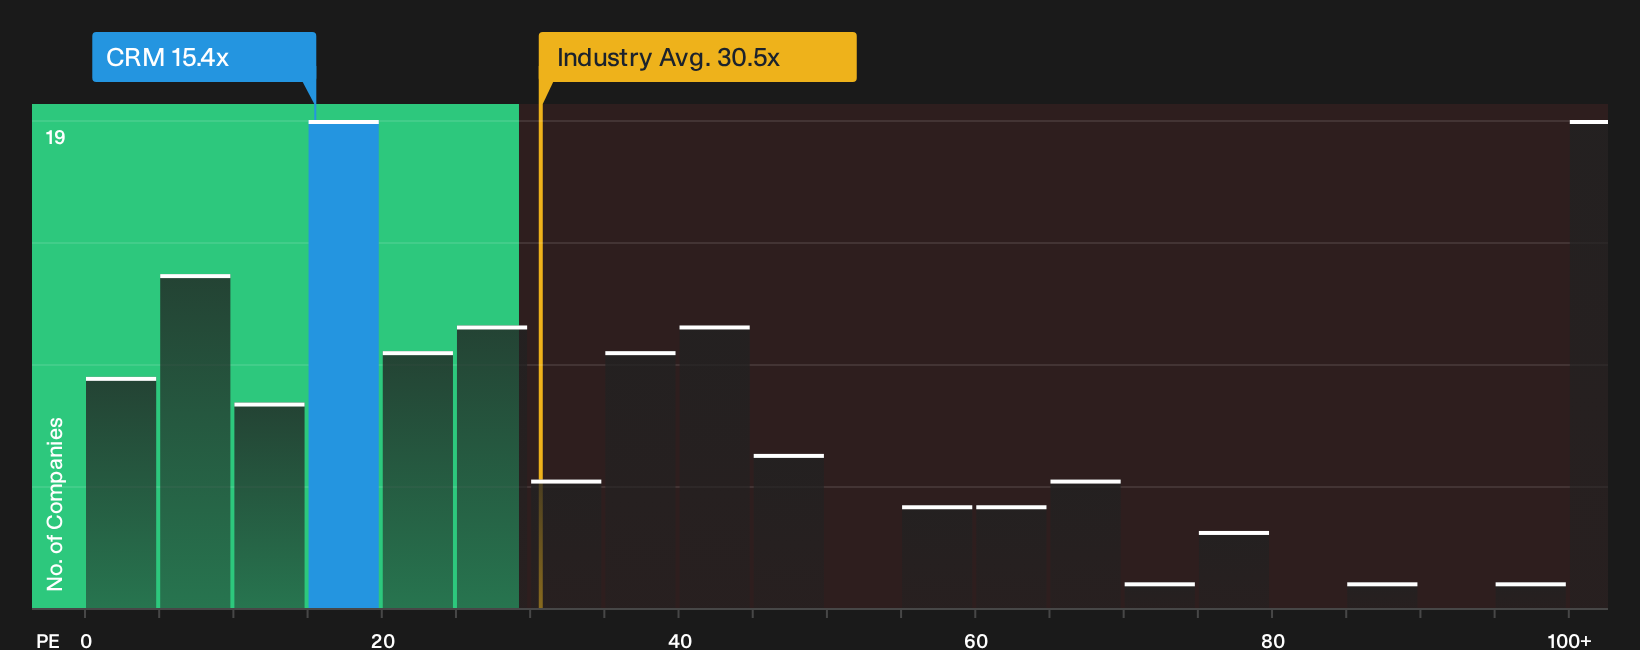
The P/E ratio is a useful metric for Salesforce because earnings are a central focus for investors in established software platforms. On this basis, Salesforce trades at about 15.4x earnings, which is well below the broader software industry average of roughly 30.5x and peers closer to 38.3x. This gap suggests the market is applying a clear discount to the stock compared with other software businesses that share similar accounting foundations.
The Fair Ratio framework blends factors such as growth, profitability, size and risk into one benchmark. It points to a higher multiple than Salesforce currently trades on, which indicates the stock screens as undervalued on this measure. Despite recent worries around AI competition and the sell-off that followed, the current P/E still prices Salesforce below what this tailored yardstick implies investors might typically pay for its earnings profile. Explore the numbers behind Salesforce's P/E valuation.
The Salesforce Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Salesforce valuation puzzle leaves off by spelling out what kind of growth, margin profile and earnings path would need to hold for the stock to look materially cheaper or more expensive than today’s price on the Community page. Each narrative treats fair value as a hypothesis about Salesforce's business that you can watch over time, rather than a static number on a single day.
One of the top community narratives on Salesforce: 39% undervalued
According to HedgeY, an investor in the Simply Wall St Community, the key question is whether Salesforce can turn AI from a threat into a new earnings engine.
"Salesforce is not only defending the old SaaS model, it is trying to redefine it as a platform that sells trusted data, permissions, workflows, and agentic actions…"
Discover why this Narrative puts Salesforce at 39% undervalued.
The price of Salesforce is only one piece of the decision
Share price and P/E tell you what Salesforce costs today, but analyst projections for revenue, margins and earnings a few years out offer a separate lens on what that price is really asking you to believe. Explore where analysts expect Salesforce to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com