


EN
South32 (ASX:S32) Shares May Be Below Fair Value On Aluminium Deal Progress
South32 has delivered a solid share price run over the past few years, and with fresh deal activity reshaping its portfolio, the question now is how well today's price lines up with the earnings behind it. For anyone tracking the stock after a mix of shorter term ups and downs, the key issue is whether the current market tag is still grounded in what the business is actually making.
- Over the past 3 years, South32 has returned 37.9%, which puts real weight on whether the underlying earnings profile can carry that kind of share price outcome.
- Alcoa's plan to acquire most of South32's aluminium portfolio for up to US$8b can reshape the mix of profit, capital intensity and future cash generation that investors are effectively paying for today.
- There is a second opinion on South32 worth weighing. See what analysts think South32's shares could be worth.
The issue now is whether South32's current share price is justified by the earnings the company is generating and is expected to generate.
If you want a broader view of how other metals and mining businesses are priced on their earnings, a focused stock screen is a useful second reference point. This is especially true for tools such as 30 best rare earth metal stocks.
Is South32 a Bargain on Earnings?
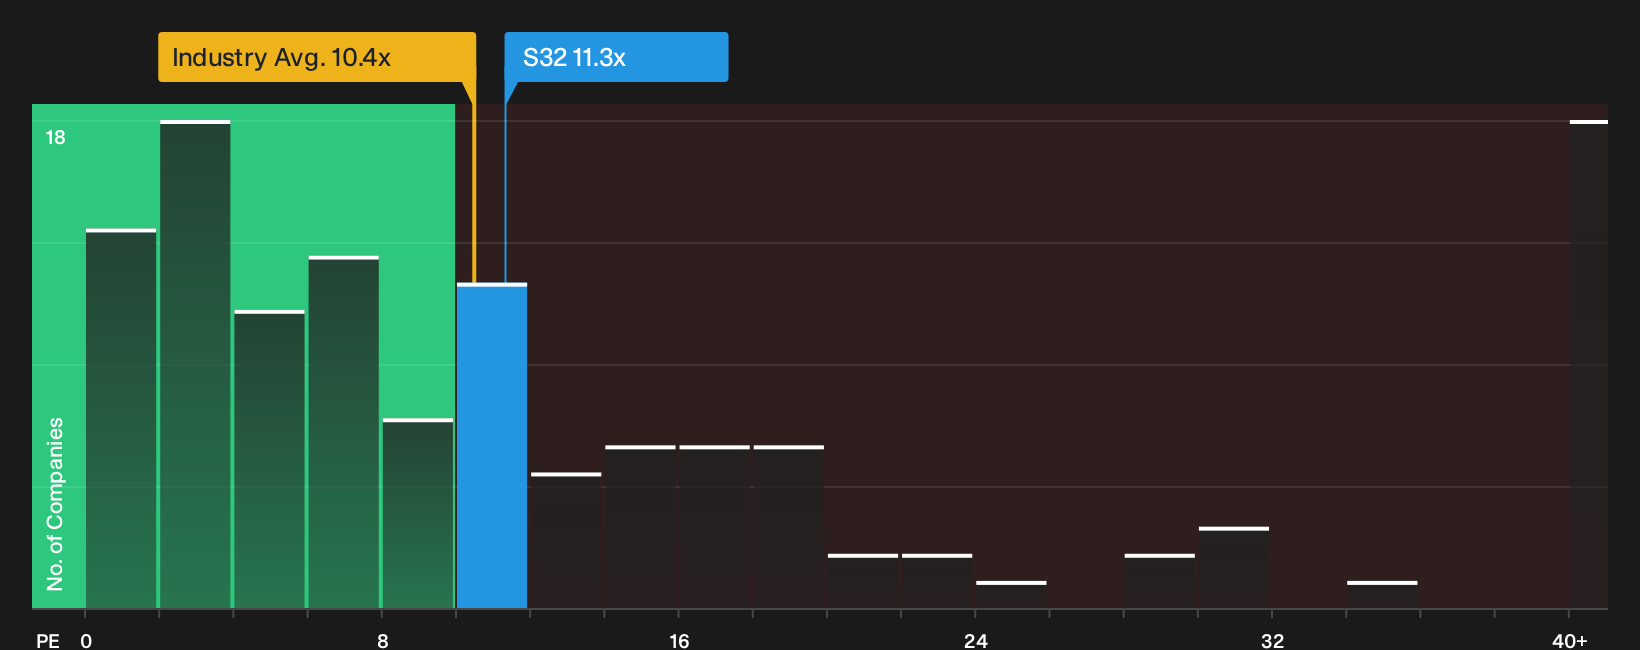
The P/E ratio suits South32 because earnings still sit at the center of how investors judge a diversified miner. On this yardstick, the stock trades on roughly 11.3x earnings, which is below the metals and mining sector average of about 10.4x and also well under the broader peer group on roughly 24.6x. That gap to peers points to a market that prices South32 more cautiously than many comparable resources stocks, even though the raw sector benchmark does not put it at an extreme.
The fair P/E level implied by the model, which blends South32’s growth outlook, profitability, size and risk profile, sits above where the shares currently change hands. On this framework, the ratio screens the stock as undervalued. Because Alcoa’s planned A$8b style aluminium asset deal could alter South32’s future earnings mix, this lower multiple may reflect investors waiting to see how the portfolio reshapes once the transaction completes. Explore the numbers behind South32's P/E valuation.
The South32 Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle leaves off for South32 by spelling out which paths for future growth, profitability and earnings would need to hold for the shares to look meaningfully cheap or expensive versus today's price. Each narrative ties its number to a clear view on how South32's growth, margins and risk profile could evolve, giving you a reference point you can revisit as new information comes through.
One of the top narratives on South32: 24% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The current valuation implies the market is not fully pricing South32 as a simpler, growth funded base metals and critical minerals company with a large copper and zinc pipeline..."
Discover why this Narrative puts South32 at 24% undervalued.
South32’s price tag is only one part of the decision
Valuation models tell only part of the South32 story, because Simply Wall St’s broader checks have also picked up specific risk factors that investors may want to weigh before getting comfortable. Take a closer look at 2 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com