


EN
Is HubSpot (HUBS) Undervalued Following Its Leadership Overhaul?
Leadership overhaul puts HubSpot in focus
HubSpot (HUBS) is back under the spotlight after a sweeping leadership reshuffle, with co founder Brian Halligan returning as CEO and long serving CFO Kate Bueker preparing to retire.
The leadership shake up comes after a tough run for the ticker. The share price is at US$193.88 with a 30 day share price return that is down 22.4%, while the 1 year total shareholder return has fallen 45.4%. This suggests momentum has been fading despite the fresh headlines.
Scan how other software players are reacting to similar leadership and sentiment shifts by reviewing our curated list of 42 high quality undervalued stocks alongside HubSpot on your watchlist.
After a near 50% slide in the past year and a fresh leadership reset at HubSpot, the question tightens: Is this the moment to lean into the reset, or wait for a cheaper entry before moving?
Most Popular Narrative: 15% Undervalued
HubSpot's last close at $193.88 sits below the analyst consensus Narrative fair value of $228.90, which the analyst consensus Narrative on Simply Wall St bases on detailed revenue, earnings, and discount rate assumptions.
Rapid adoption of HubSpot AI agents and LLM connectors, including a rising share of Pro+ customers using agents and 5x growth in monthly agentic actions, supports the shift to a seats and credits model and creates a path for higher net revenue retention and margin contribution from AI usage over time.
See why 69 investors see HubSpot as 15% undervalued.
Result: Fair Value of $228.90 (UNDERVALUED)
Still, the narrative for HubSpot can break if SMB demand stays weak and the new AI agent credit model fails to lift recurring spend as analysts expect.
Find out about the key risks to this HubSpot narrative.
Another View: HubSpot Through The P/E Lens
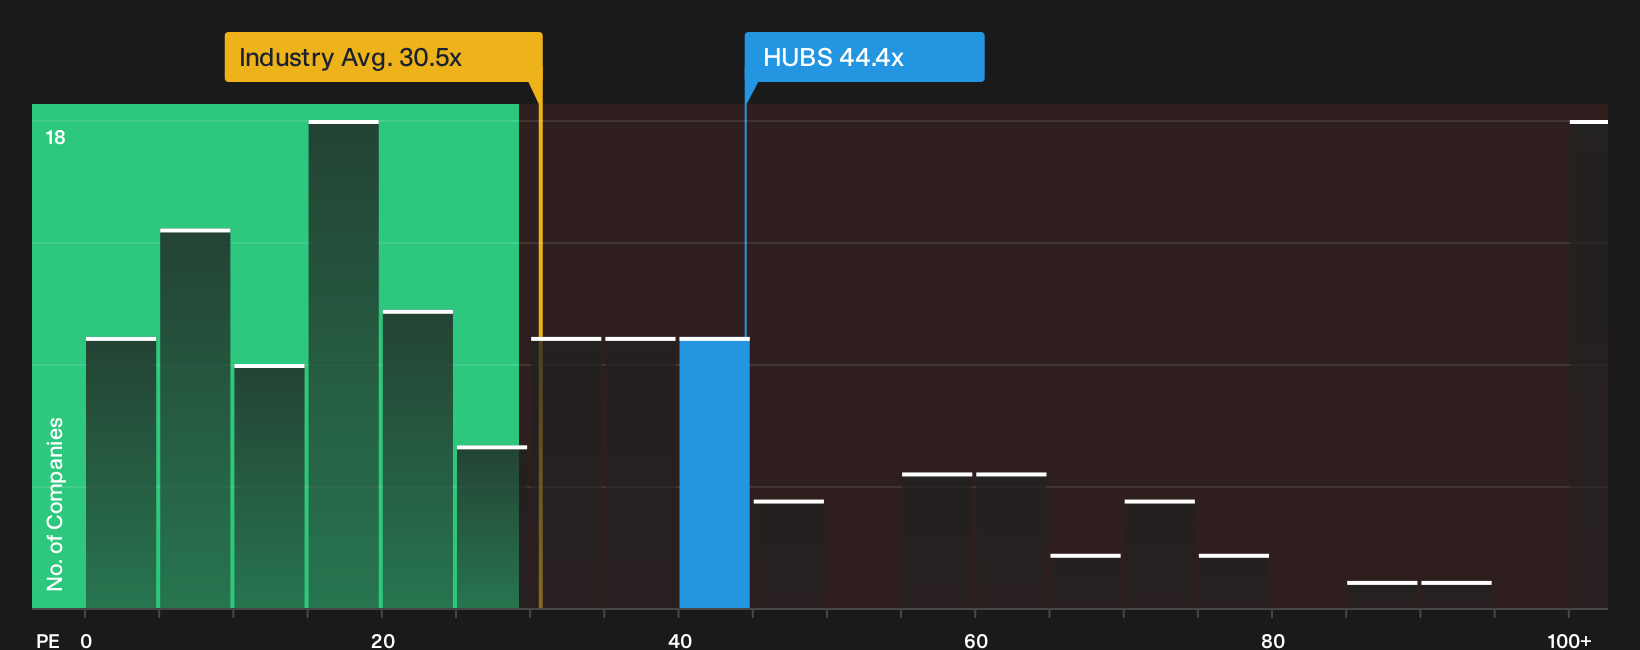
On the flip side of that narrative fair value, HubSpot trades on a P/E of 44.4x compared with about 30.5x for the US Software industry and 54.3x for its peer group. The Simply Wall St fair ratio sits higher again at 59.7x. Is that premium a cushion or a margin of risk if expectations reset?
To see how that valuation gap could close in either direction, walk through the detailed multiples breakdown in our See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted by the split views on HubSpot today. Act while sentiment is still resetting, and pressure test the upside by weighing the 3 key rewards.
Looking for more HubSpot sized investment ideas?
Do not stop your research at HubSpot. Broaden your shortlist with fresh ideas that match different risk levels, income needs, and balance sheet strength.
- Target potential mispricing by scanning a focused universe of quality companies using the 42 high quality undervalued stocks.
- Build a steadier income stream by reviewing businesses that feature the 8 dividend fortresses.
- Dial down portfolio stress by concentrating on companies highlighted in the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com