


EN
Meta Platforms (META) Taps Euro Bond Market As Fair Value Debate Heats Up
Meta Platforms (META) has just tapped the euro bond market, issuing several tranches of long dated senior notes across maturities from 2031 to 2065. That fresh funding immediately puts the balance sheet in focus.
For investors watching the tape, Meta Platforms’ share price has retreated sharply in the short term, with a 1 day move of 5.85% lower and a 30 day share price return down 19.53%, yet the 3 year total shareholder return of 67.55% still points to strong longer run gains.
Scan how other AI heavyweights are handling balance sheet pressure alongside Meta Platforms by reviewing our curated list of 53 AI infrastructure stocks.
Meta Platforms now combines a powerful advertising engine with heavy AI and hardware spending, yet the share price has dropped sharply. Is this still a strong business offered at a fair price, or has the market already paid up?
Most Popular Narrative: 44.9% Undervalued
Meta Platforms closed at $561.32 while the leading narrative fair value sits at $1,018.71, which implies a large valuation gap according to mitchell_lawler, a Simply Wall St Community investor who wrote the narrative and frames Meta as more than just an ad seller.
This is what the capex is for. The spending is not subtle. Meta's capital expenditure ran to $72.2 billion in 2025. Guidance for 2026 has since been lifted to a range of $125 billion to $145 billion. The company is roughly doubling its infrastructure bill in a single year, and when it raised the range in April, the stock fell on the news.
See why 203 investors see Meta Platforms as 45% undervalued.
That view leans heavily on the idea that the AI and hardware buildout can turn Meta Platforms from an attention business into something closer to a toll on digital commerce, with the current share price not reflecting that potential according to the narrative. The discount rate used in that work is 8.84%, which anchors the cash flow projections that back the $1,018.71 estimate.
For readers weighing that argument against the recent share price pullback, the key question is whether Meta's large capex program and 31.1% net profit margin can support the cash flows implied in that fair value, or whether the market is more accurately pricing in the risks around regulation, board changes and Reality Labs losses.
Result: Fair Value of $1,018.71 (UNDERVALUED)
Still, the Meta Platforms narrative can break if regulators tighten data and privacy rules, or if heavy Reality Labs losses keep dragging on group profitability.
Find out about the key risks to this Meta Platforms narrative.
Another View: What Meta Platforms’ P/E Is Telling You
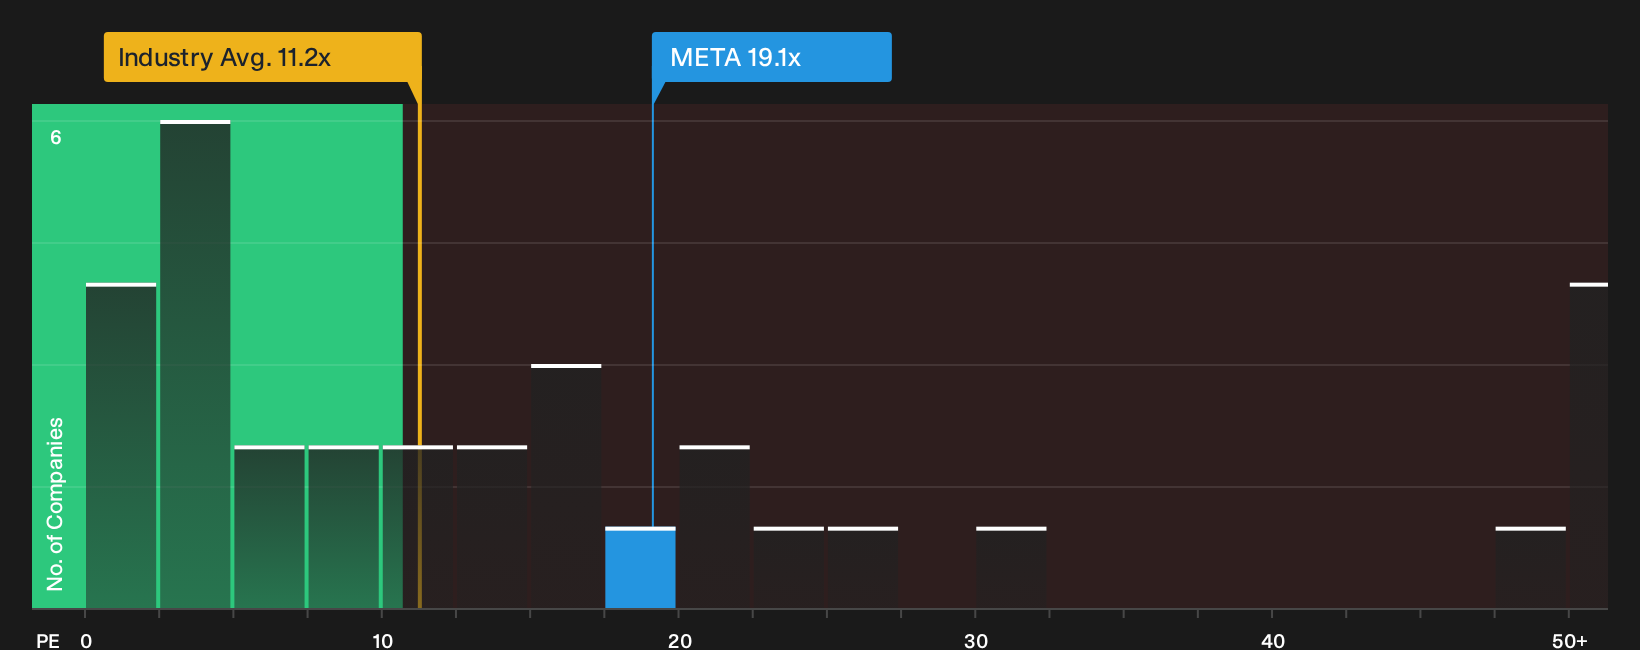
There is a very different picture when you look at Meta Platforms through its P/E. The stock trades at 19.1x earnings. That is higher than the US Interactive Media and Services industry at 11.2x, yet below both the peer average of 23.1x and a fair ratio estimate of 36.7x, which some investors may interpret as indicating the market could move closer to that level over time.
This mix of cheaper than peers, richer than the sector and below the fair ratio points to the possibility of valuation risk if sentiment turns, but also room for the multiple to stretch if the bullish narrative holds. Which side of that trade are you really underwriting?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Meta Platforms in this piece is mixed, with clear upside arguments set against real concerns. Act while the data is fresh and test both sides for yourself by starting with the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Meta Platforms?
If Meta Platforms has your attention right now, do not stop there. Use the same data driven approach to line up your next set of candidates.
- Spot potential mispricings early by scanning a curated pool of 42 high quality undervalued stocks before the crowd starts paying attention.
- Strengthen the income side of your portfolio by zeroing in on dependable payers using our focused set of 8 dividend fortresses.
- Sleep easier when markets get choppy by building a watchlist from a hand picked 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com