


EN
UiPath (PATH) Stock Could Be Cheap After a 77% Five Year Slump
UiPath has seen its share price fall sharply in recent years, which puts fresh attention on a simple question for you as an investor. Given that drop, is today’s UiPath stock price actually justified by the earnings the business is generating?
- Over the past 5 years the share price has declined 77.2%, which puts the focus squarely on whether the current valuation still lines up with UiPath’s earnings power.
- The new partnership with Google Cloud’s Gemini for healthcare can influence how investors think about future earnings, since wider automation in regulated healthcare may support different assumptions for revenue growth and profitability over time.
- Your read on UiPath is one view; the desks covering it have another. See what analysts think UiPath's shares could be worth.
For investors, the discussion centers on whether UiPath’s current price is adequately supported by what the company earns today and what those earnings reasonably indicate over time.
If you want a cleaner comparison point for UiPath’s earnings story and AI exposure, compare it with 43 profitable AI stocks that aren't just burning cash.
Does UiPath Look Undervalued on Earnings?
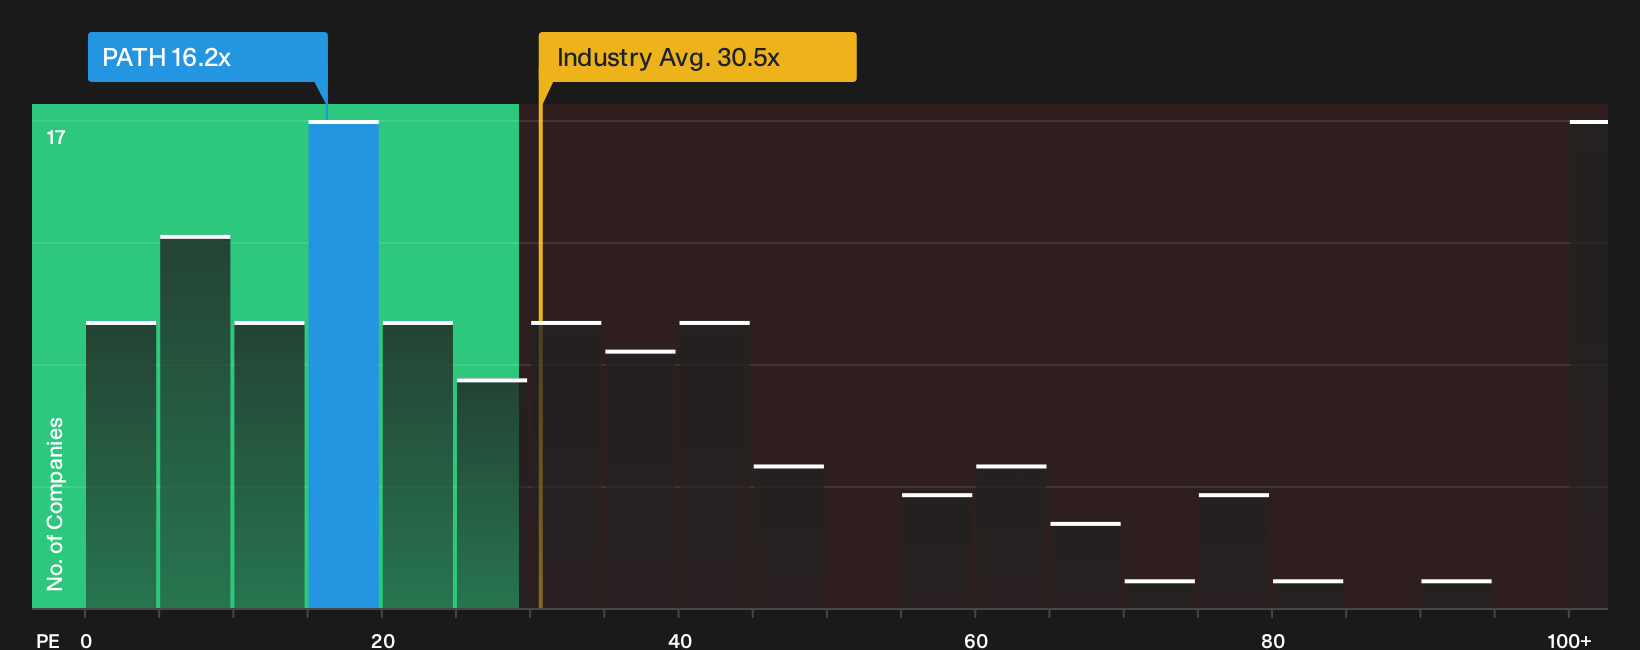
The P/E ratio works well for UiPath because it already generates free cash flow and reports earnings, so investors have a concrete profit base to compare with the share price. On this lens, UiPath trades on a P/E of about 16.2x, which is well below the wider software industry average of roughly 30.5x and also under the peer group near 36.2x.
Because the recent Google Cloud Gemini for healthcare partnership raises questions about how AI could feed into future demand, it is striking that the valuation still sits materially below the multiple suggested by a more tailored fair-value model. That framework, which folds in UiPath’s sector, growth profile, margins and risk, points to a higher P/E than the market currently assigns, so the stock screens as undervalued on this earnings measure. For you as a shareholder or potential buyer, the gap flags a discount that only looks justified if you believe the business will struggle to convert its automation and AI position into sustained profit growth. Explore the numbers behind UiPath's P/E valuation.
The UiPath Narrative: What Would Justify Today's Price?
UiPath’s recent share price slide raises a simple follow up question for you as an investor. What would actually need to happen to growth, margins and earnings for today’s valuation gap to close in either direction? Simply Wall St Narratives sit on the Community page and map out those different futures, with each one tying a potential fair value to a clear set of catalysts and risks so you can track which story aligns with how UiPath’s business develops over time.
Bulls and bears are reading the same UiPath AI and automation story yet reaching very different conclusions about what the current price already assumes.
Bull case: 27% undervalued
This view comes from the analyst consensus Narrative on Simply Wall St, which leans on quantified AI related ARR and profitability.
"UiPath''s focus on accelerating innovation across the agentic automation road map is expected to grow deeper customer relationships and strategic partnerships, and the reported US$250 million in AI related ARR with AI attached deals several times larger than traditional automation deals points to potential support for future revenue and ARR…"
Discover why this Narrative puts UiPath at 27% undervalued.
Bear case: 12% overvalued
The bearish analyst Narrative on Simply Wall St argues that pricing pushback and execution risk already bake in a rich setup for UiPath.
"Although UiPath is repositioning its automation suite as a broad BOAT platform that orchestrates robots, agents and legacy systems, several brokers still question whether this repositioning can lift ARR growth much above roughly 10%…"
Explore why this Narrative puts UiPath at 12% overvalued.
One more UiPath question worth asking
The valuation story only goes so far if you do not know who is steering UiPath or how their pay packets line up with your interests, and that picture is worth checking next. See who runs UiPath and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com