


EN
Capricorn Metals (ASX:CMM) Shares Seem Fairly Priced On Earnings Strength
Capricorn Metals has retreated in recent weeks after a strong multi year run, which puts fresh attention on whether the current A$11.48 share price lines up with the earnings power of the business. With the stock giving back some ground in the short term yet still carrying very substantial longer term gains, the question now is how much of its profit profile is already reflected in the market value.
- Capricorn Metals has delivered a gain of 298.9% over the past 5 years, so a lot of past success is already embedded in the share price and sets a high bar for what its earnings need to support.
- The group’s valuation now leans heavily on how consistently it can convert its operations into earnings. Profit quality, cost control and capital intensity all feed directly into what investors are willing to pay for each dollar of income.
- Your read on Capricorn Metals is one view; the desks covering it have another. See what analysts think Capricorn Metals's shares could be worth.
The issue now is whether Capricorn Metals’ current valuation is justified by its earnings profile when set against the Fair Ratio benchmark.
If you want a broader yardstick when weighing Capricorn Metals against its earnings-based valuation, compare it with 3 high quality undervalued stocks.
Where Does Capricorn Metals Sit on Earnings?
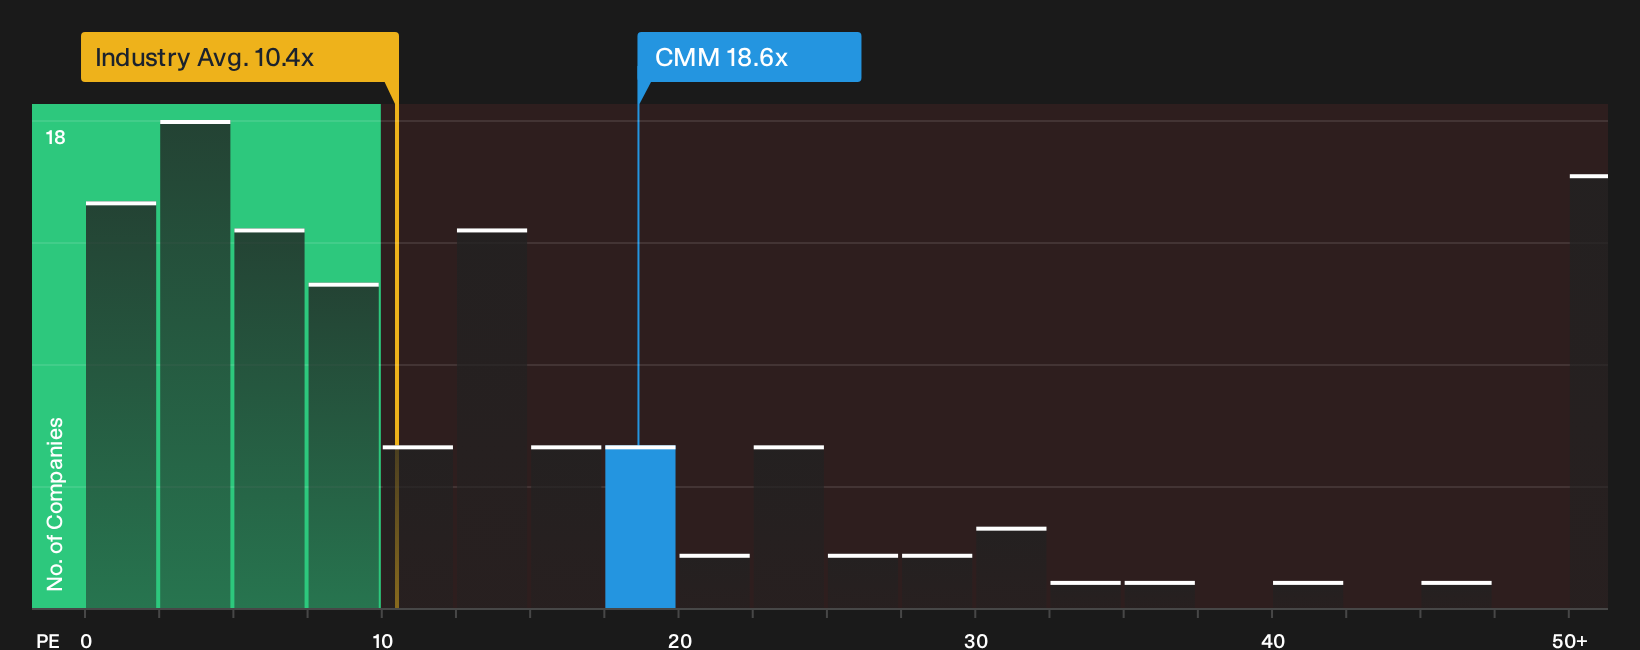
The P/E ratio is a useful lens for Capricorn Metals because earnings are a key yardstick for a producer that is already generating profit. On this measure, the stock trades at about 18.6x earnings, which is above the broader metals and mining sector average of roughly 10.4x. That sector figure is skewed by a lot of lower growth or more cyclical operators, so a straight comparison only tells part of the story.
A more tailored benchmark is the Fair Ratio, which estimates the multiple you might expect given Capricorn Metals’ growth profile, margins, size and risk. The current 18.6x P/E sits only slightly above that Fair Ratio. This points to a valuation that is broadly in line with what this earnings framework would suggest, while still implying the market is willing to pay a modest premium versus many other miners. The peer group average near 22.1x also hints that similar companies trade on richer earnings tags, so the stock does not screen as especially stretched or especially cheap relative to those closest comparables. Explore the numbers behind Capricorn Metals's P/E valuation.
The Capricorn Metals Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Capricorn Metals valuation puzzle leaves off and spell out what growth, margin and earnings paths would need to hold for the shares to be worth meaningfully more or less than today. Each scenario ties a fair value estimate to a specific mix of potential catalysts and risks so you can track over time which version of Capricorn Metals' future is actually unfolding.
One of the top narratives on Capricorn Metals: 52% undervalued
This Narrative is the bullish analyst Narrative on Simply Wall St, built on the most optimistic analyst price target and forecasts, not one person's view.
"The current valuation implies that the market places limited value on Capricorn Metals' enlarged 5.2 to 5.24 million ounce reserve base and planned lift toward approximately 400,000 ounces per year of production..."
Discover why this Narrative puts Capricorn Metals at 52% undervalued.
Capricorn Metals: why the people steering the business could matter as much as the price tag
Before making any call on Capricorn Metals, it helps to know who is actually running the operation, how their incentives line up with yours, and whether that structure really supports the outcomes the share price implies. See who runs Capricorn Metals and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com