


EN
Coatue Management Just Bought 8 Million Shares of Salesforce Stock. Why Investors Should Care.
Enterprise software-focused hedge fund Coatue Management has taken an intriguing position in Salesforce (CRM). According to its latest 13F filing, Coatue bought approximately 8.03 million shares of the company during the third quarter of 2026. At CRM stock's current price of roughly $185, this position is worth approximately $1.5 billion, although its value on the reporting date may have been slightly different.
This move merits consideration, especially as Salesforce is facing tough times attracting investors despite the company becoming more profitable alongside increasing demand for artificial intelligence (AI) products. Coatue Management also increased its Meta Platforms (META) position during the period, buying approximately 1.99 million shares during the quarter. Although these moves do not indicate how the fund is currently positioned, they show that Coatue found some good moves in established tech companies during Q3.
About Salesforce Stock
Salesforce is a leading enterprise software firm based in San Francisco, California. The company specializes in customer relationship management (CRM), cloud applications, data analytics, and business automation powered by AI. Salesforce's market capitalization currently amounts to roughly $150.8 billion.
CRM stock is currently under significant selling pressure. At today's levels, shares are trading approximately 31% below the 52-week high of $269.11. However, they are still approximately 26% above the 52-week low of $146.32. CRM stock has declined 15% over the past five trading days.
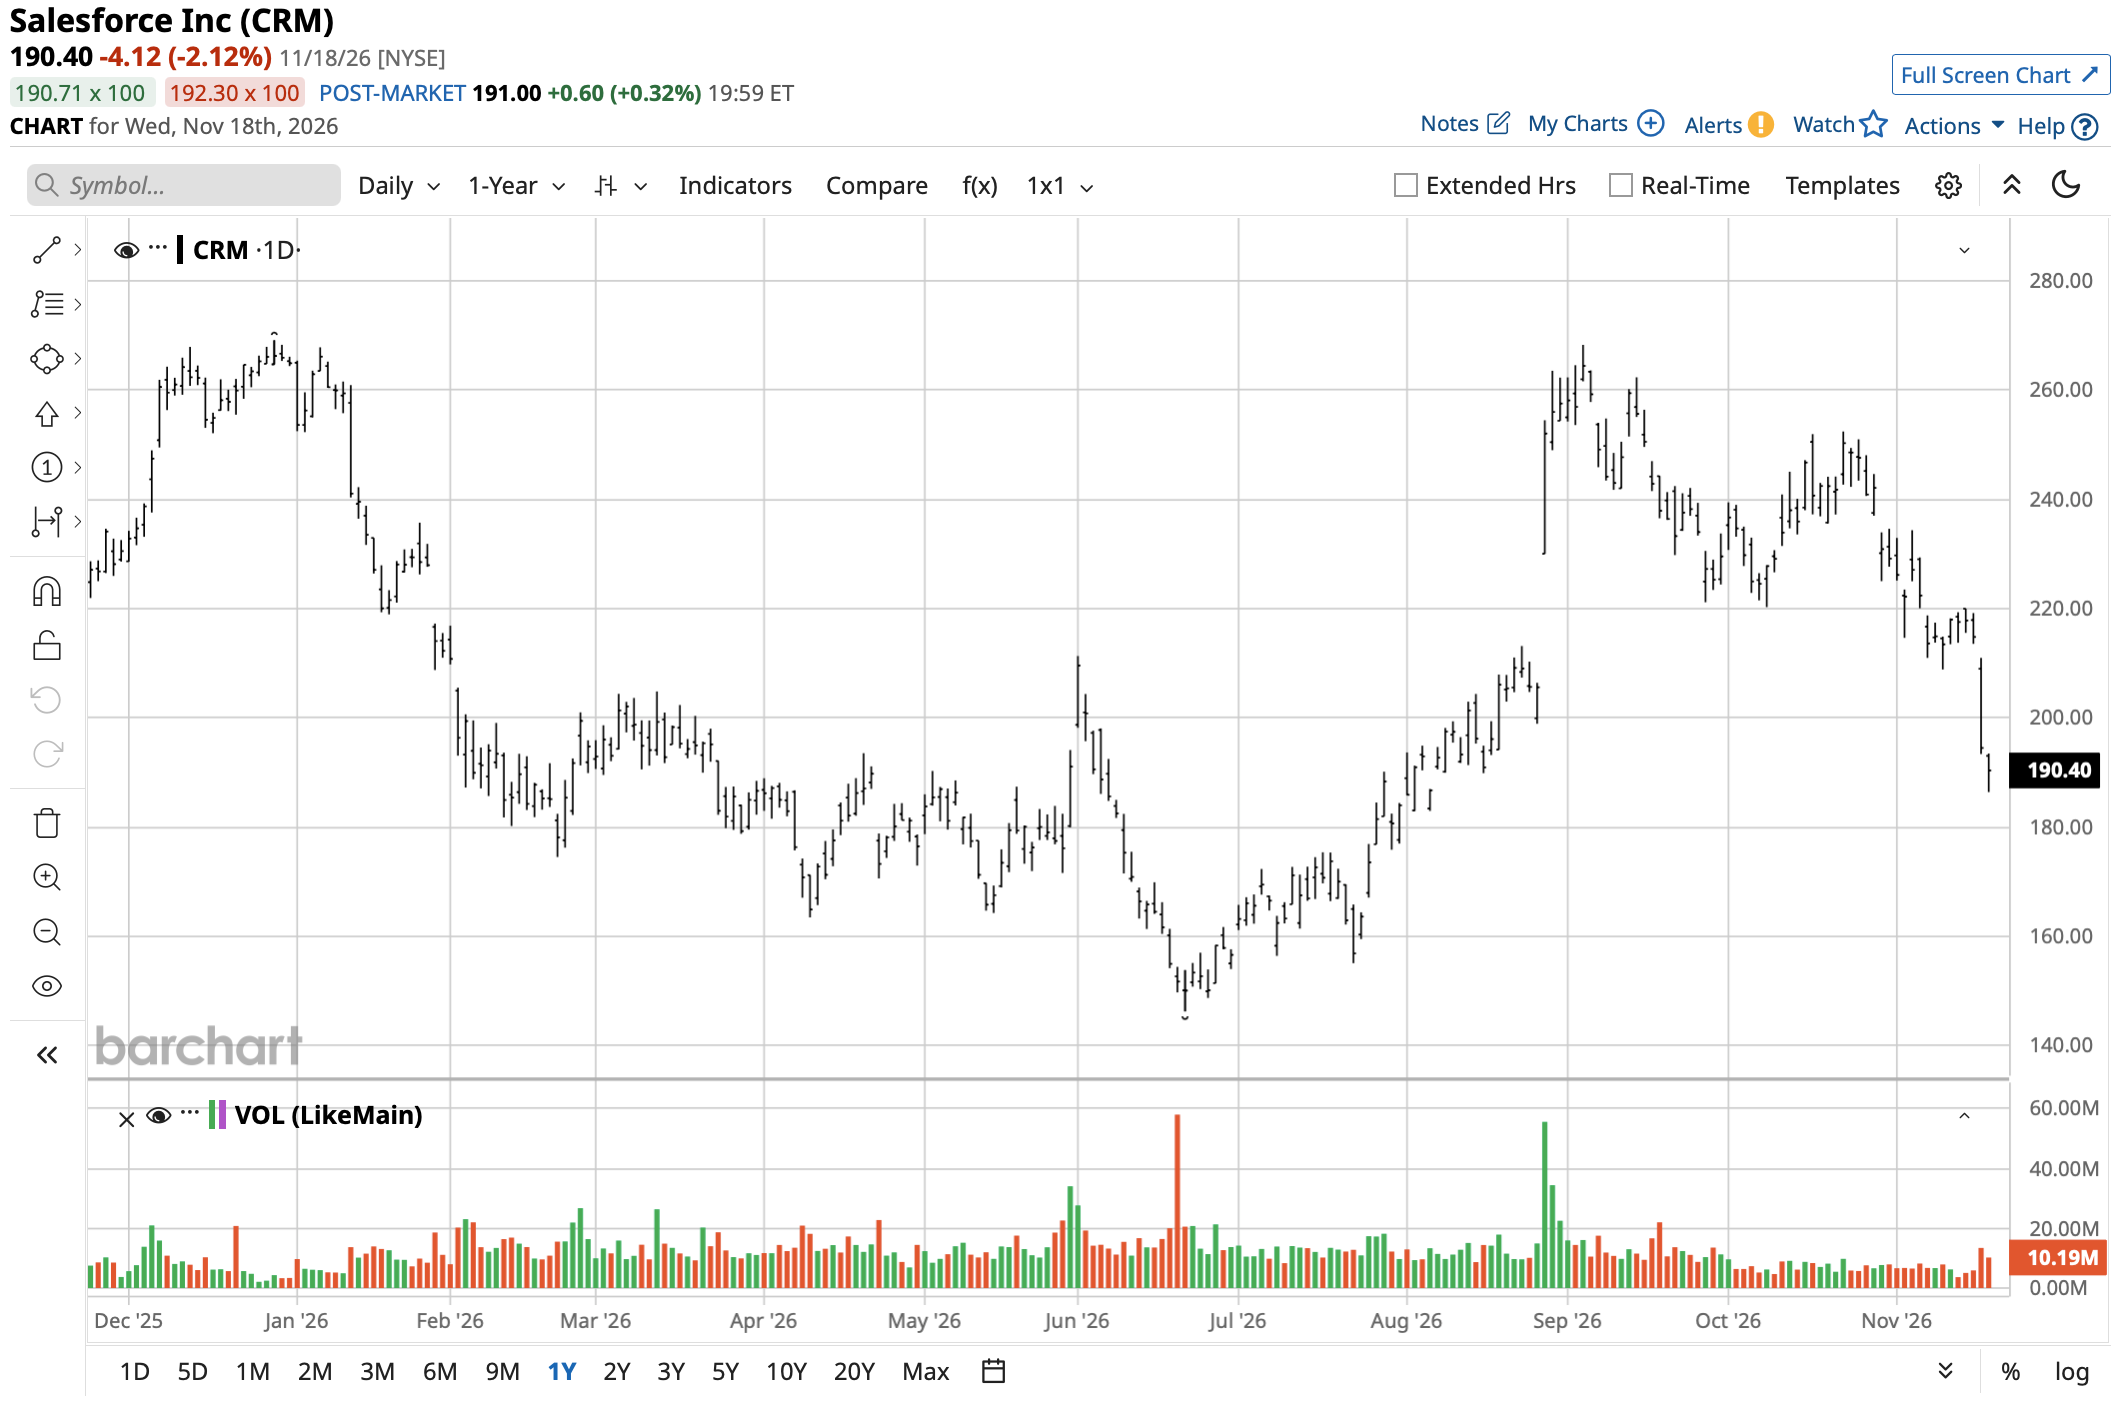
From a valuation standpoint, Salesforce stock has a forward price-to-earnings (P/E) ratio of 14.8 times, while its trailing P/E ratio is about 14.1 times. Additionally, Salesforce has a price-to-sales (P/S) ratio of 3.7 times, which is quite attractive considering that the company generates double-digit revenue and earnings growth while also having an operating margin of more than 30% on an adjusted basis.
Nevertheless, a low valuation does not mean Salesforce is undervalued. In CRM stock's case, many investors are worried about whether AI automation may ultimately disrupt enterprise software business models. Salesforce needs to prove to investors that its AI products can generate solid incremental revenue.
Salesforce Posts Solid Q2 Earnings
Salesforce reported second-quarter fiscal 2027 results on Aug. 26. During the period, the company reported revenue of $11.3 billion, up 11% year-over-year (YOY). EPS of $4.29 was up 119% YOY, while adjusted EPS grew by 103% to $5.90. Salesforce reported a non-GAAP operating margin of 34.1%, meaning that the company can be profitable and invest in AI at the same time.
More importantly, Salesforce reported a 14% YOY increase in current remaining performance obligations (cRPO) to $33.5 billion. The company also reported a 71% jump in operating cash flow to $1.3 billion and an 81% increase in free cash flow to $1.1 billion.
Management raised its fiscal 2027 revenue guidance to a range of $46.1 billion to $46.4 billion, which corresponds to 11% to 12% YOY growth. For Q3, Salesforce expects revenue of $11.42 billion to $11.5 billion, along with adjusted EPS of $3.42 to $3.44. The company also left its full-year operating margin estimate unchanged at 34.3%.
One of the most positive things in the Q2 report was the growth of its AI business. Annual recurring revenue (ARR) for Agentforce and Data 360 reached $3.9 billion, growing more than 210% YOY. Agentforce ARR alone exceeded $1.5 billion. However, investors should note that this is the aggregate ARR generated by several AI products, including Slackbot and Headless 360.
These numbers indicate that Salesforce is starting to monetize its AI investments. Meanwhile, the company is also increasing revenue via acquisitions, which means that organic revenue growth should be monitored.
Salesforce also continues to pay dividends and return money to investors with its $25 billion accelerated share repurchase program.
What Do Analysts Think of Salesforce Stock?
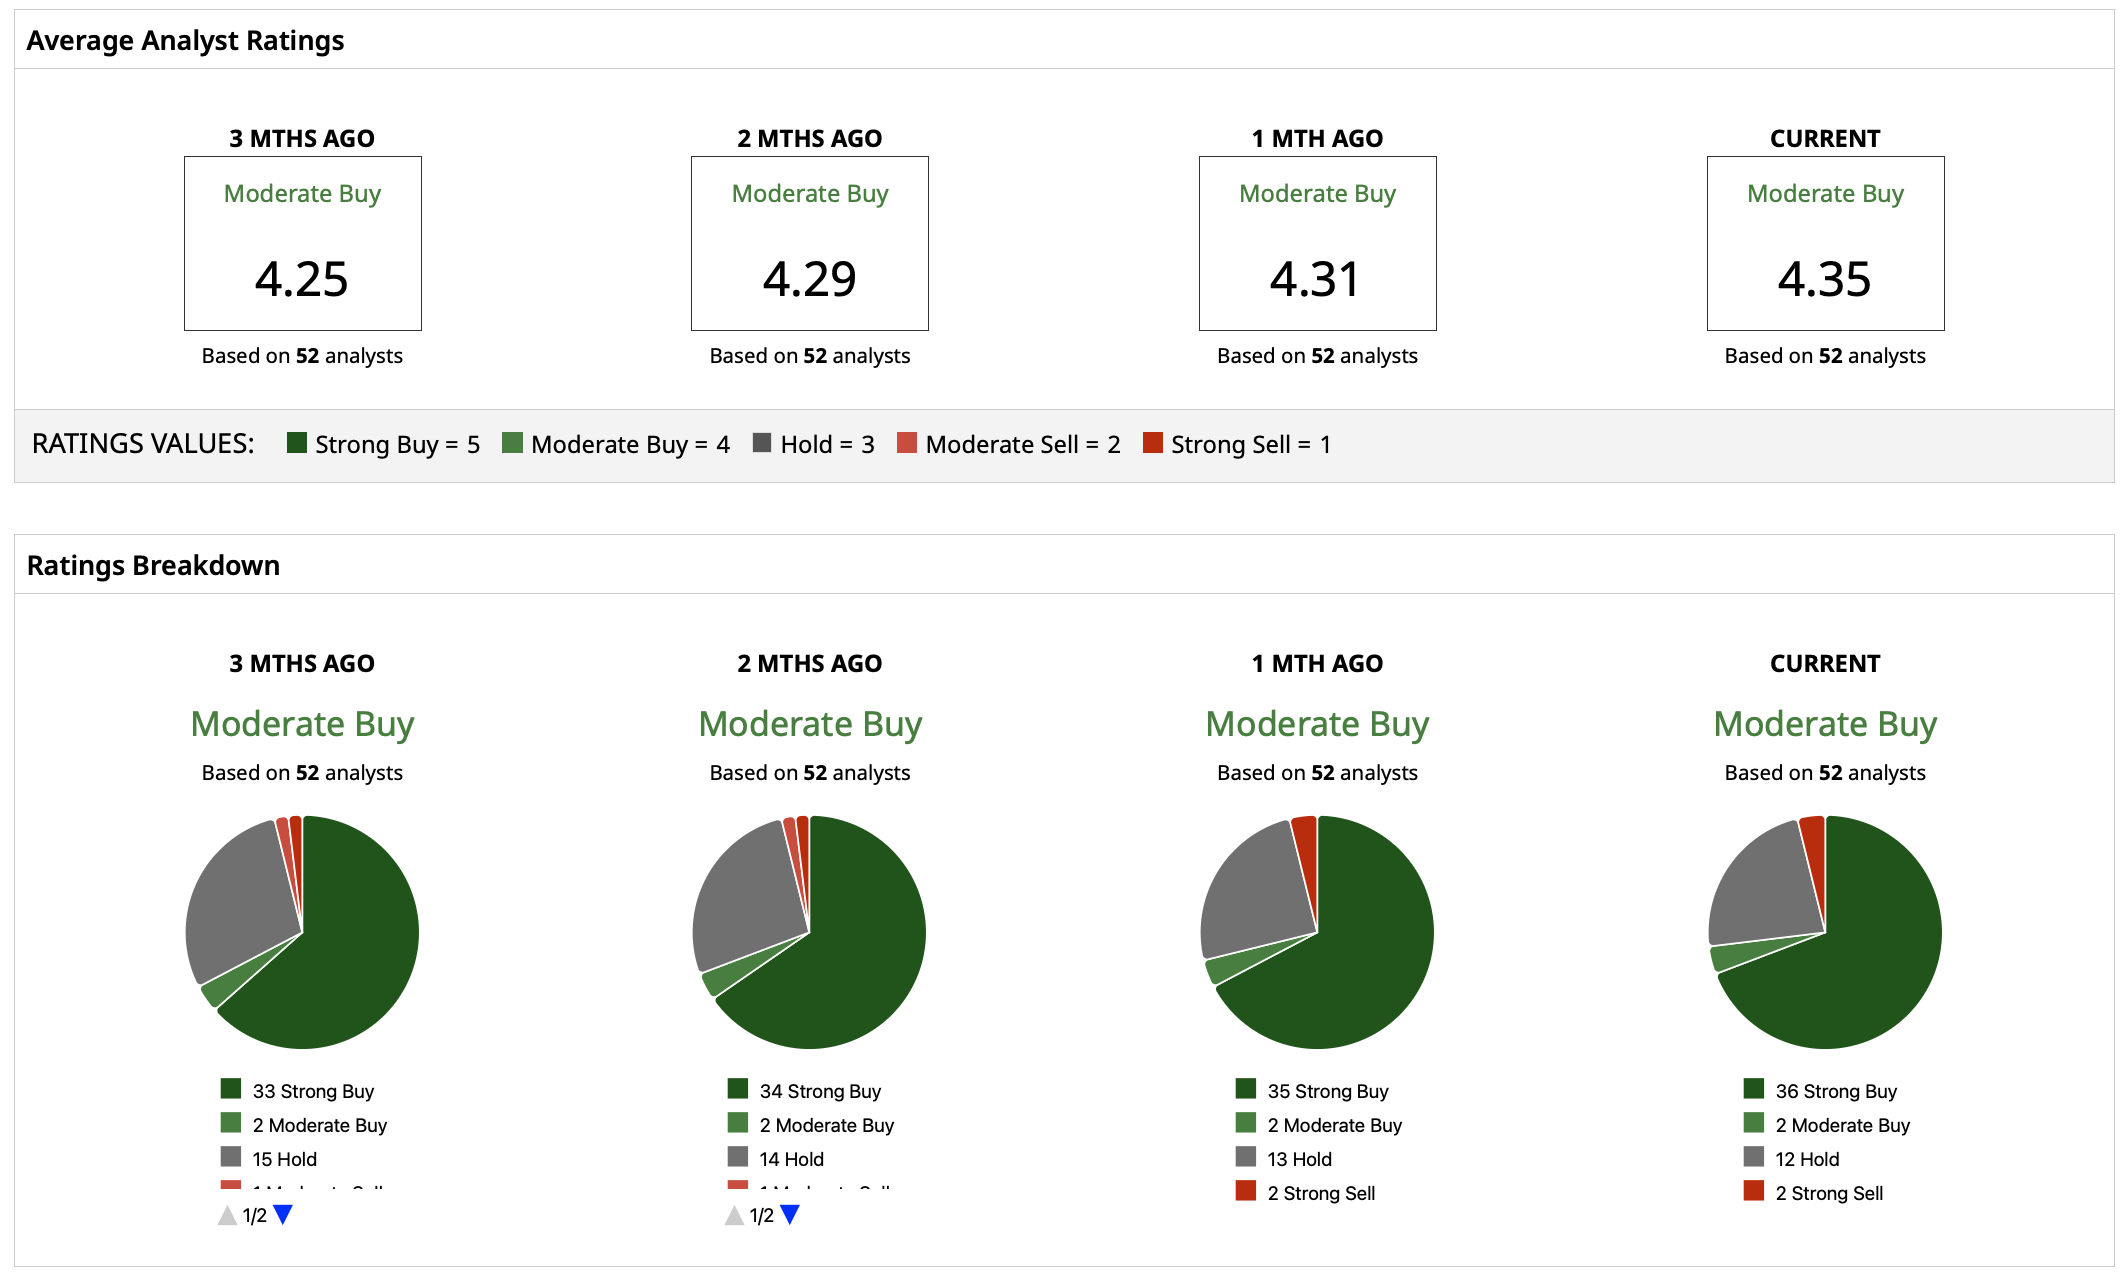
Despite the weak stock performance, Salesforce appears to have considerable recovery potential, as indicated by Wall Street's consensus “Moderate Buy” rating. CRM stock has a mean price target of $285.88, translating to potential upside of approximately 55% from current levels.
The highest price target of $475 suggests potential upside of 158% from here, while the lowest target of $165 implies a potential 10% fall. That wide price target range shows the degree of uncertainty about Salesforce's future growth potential and the impact of AI on enterprise software spending.
On the date of publication, Yiannis Zourmpanos did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.