


EN
Coca-Cola's Valuation Is the Highest in 25 Years. Where Does The Stock Go From Here?
Coca-Cola (NYSE:KO) shares trade near $98, and Barron’s reported that the stock’s valuation is the highest in 25 years. Our 24/7 Wall St. price target is $111.93. That means 14.21% upside over the next 12 months, and our model rates KO a buy with high confidence.
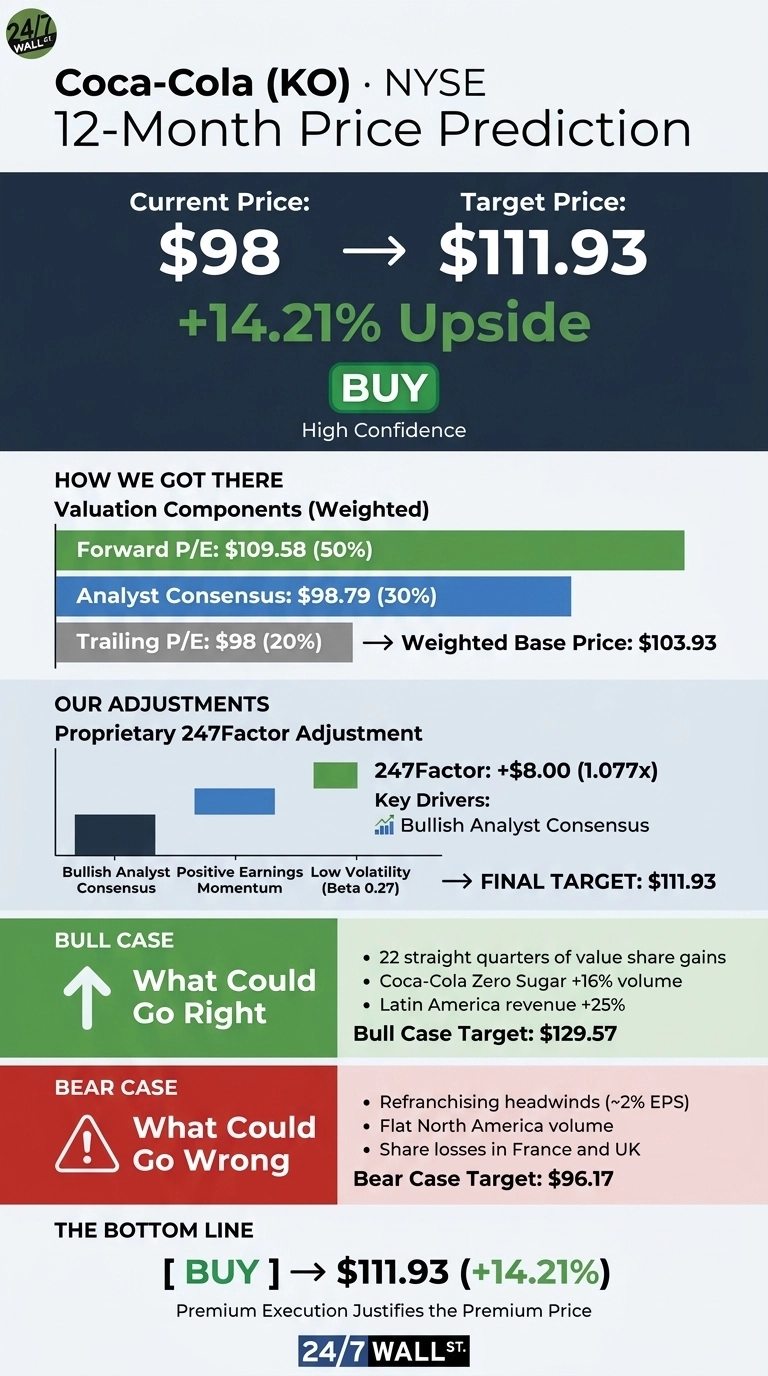 24/7 Wall St. 24/7 Wall St. Price Target Summary Metric Value Current Price $98 Price Target from 24/7 Wall St. $111.93 Upside/Downside 14.21% Recommendation BUY Confidence Level 90%
A rich multiple needs earnings to back it up, and Coca-Cola has delivered.
It has beaten EPS estimates in all 7 of its most recent reported quarters and has raised its 2026 earnings outlook at every report this year. I think the premium holds as long as volume growth does.
Rotation Into Defensives Lifts Coca-Cola Near Its 52-Week HighKO is up 41.54% year to date and 9.22% over three months. It gained 3.9% over the past month but slipped 0.52% over the past week.
The stock sits about 2% below its 52-week high of $100.56 and is well clear of its low of $65.99. Jim Cramer credited part of the run to investors who “have rotated out of tech into the tried and trues“.
In Q3, adjusted EPS came in at $0.91 against a $0.8809 consensus. Revenue rose 7.43% to $13.38B, beating the $12.93B estimate. Unit case volume grew 5%, and management now guides for comparable EPS growth of at least 11% and free cash flow of at least $13.0B.
Volume and Pricing Power Fuel the Bull CaseCoca-Cola has gained global value share for 22 consecutive quarters and took four points of pricing in Q3. Coca-Cola Zero Sugar grew 16%, and Latin America revenue rose 25%.
Net debt stands at 1.3 times EBITDA, which leaves room for buybacks or a possible IPO of its bottling operations in India. Analysts break down as 7 Strong Buys and 13 Buys. If execution holds, our optimistic scenario makes $129.57.
Refranchising Headwinds and a Stretched Multiple Could Stall GainsKO trades at 32 times trailing earnings with a free cash flow yield of 1.26%. In fairness, that cash yield uses weak trailing figures, and 2026 guidance calls for much stronger cash generation.
In 2027, Coca-Cola faces an 8% revenue headwind and a 2% EPS headwind from acquisitions and divestitures, mainly the African bottler sale. Bulls note that refranchising should improve margins. Other risks include flat North America volume, share losses in France and the UK, and the IRS litigation. Our bear case is $96.17.
Is Coca-Cola Pricier Than PepsiCo and Monster? Company P/E Latest Quarter Revenue Growth Coca-Cola 32 7.43% PepsiCo (NASDAQ:PEP) 23 5.59% Monster Beverage (NASDAQ:MNST) 46 16.65%PepsiCo is Coca-Cola’s most direct global rival, and it is cheaper at 23 times earnings. That discount reflects weaker growth: PepsiCo guides for core EPS growth of just 2.5% to 3.5%, while Coca-Cola expects at least 11%.
Monster is a useful growth contrast because it relies on Coca-Cola for distribution. It trades at 46 times earnings, but its operating margin contracted to 28% from 30.7%. Coca-Cola’s valuation falls between its two peers, which makes our 24/7 Wall St. price target look reasonable.
Premium Execution Justifies the Premium PriceMy 24/7 Wall St. price target is $111.93, the model rates KO a buy, and confidence is high. The deciding factor is steady earnings growth coupled with a low beta, the kind of multi-decade dividend track record we screened for in our free Dividend Kings guide.
The outlook improves if volume and pricing each contribute 2-3 points of growth into 2027. The risk rises if refranchising pressures and soft North American demand slow EPS growth sharply. For now, I think the growth justifies the premium.
This is the level where our model projects Coca-Cola could trade if current growth trends and market conditions hold.
Year Price Target from 24/7 Wall St. 2026 $98.74 2027 $111.93 2028 $124.12 2029 $133.43 2030 $142.79These projections assume Coca-Cola keeps running its existing strategy. A faster-than-expected decline in the valuation or a ruling in the IRS dispute could push results significantly higher or lower.