


EN
Salesforce Layoff Alert: How to Play CRM Stock Amid Another Round of Job Cuts
Salesforce (CRM) is facing another round of job cuts just as investors are already questioning the sustainability of its growth in an increasingly artificial intelligence (AI) -driven software market. According to reports, Salesforce has begun another workforce reduction, with employees discussing layoffs in internal Slack channels and a senior manager confirming that they and several colleagues were affected. The company has not disclosed the size or scope of the latest cuts.
The latest reductions add to a series of workforce cuts this year, including layoffs impacting hundreds of positions across California, Washington, and other markets. Salesforce also cut fewer than 1,000 roles earlier in 2026, including positions in marketing, product management, data analytics, and its Agentforce AI business.
However, the bigger question is whether the layoffs represent another step toward a leaner, more profitable Salesforce or signal deeper concerns about the company’s traditional software model as AI reshapes enterprise technology.
CRM shares have already come under significant pressure this year, while the latest layoff report triggered another sharp selloff. With Salesforce preparing to report its next quarterly results, investors will be watching whether aggressive cost management, Agentforce growth, and the company’s broader AI strategy can provide a catalyst for CRM stock.
About Salesforce Stock
Salesforce is a leading global provider of cloud-based customer relationship management (CRM) software, headquartered in the iconic Salesforce Tower in San Francisco, California.
Salesforce’s market cap stands at $150.9 billion, reflecting its status as one of the most valuable enterprise software companies globally. With its comprehensive platform, innovative technology, and scalable business model, Salesforce remains at the forefront of enterprise digital transformation.
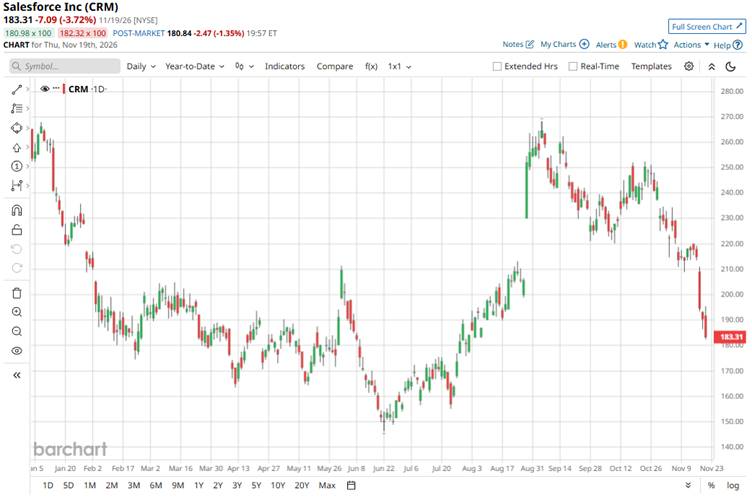
Salesforce stock has come under renewed pressure, extending what has already been a difficult year for investors. Shares are down 18% over the past 52 weeks and 30% year-to-date (YTD), while the stock currently sits 17.5% below its 52-week high of $269.11.
The selling has accelerated in recent sessions, with CRM slumping 15% over the past five days, as investors reacted to reports of another round of Salesforce layoffs and broader concerns about the impact of artificial intelligence on traditional enterprise software. The latest job cuts have added to worries that Salesforce is relying increasingly on cost reductions and workforce efficiency to offset slower growth.
The latest decline also reflects a broader reassessment of Salesforce’s AI strategy. Investors are weighing the potential of Agentforce and other AI offerings against the risk that increasingly capable AI agents could reduce demand for traditional per-seat software. That concern has become more pronounced as Salesforce continues to restructure its workforce while simultaneously investing heavily in AI and making acquisitions, including its roughly $5.7 billion deal for Braze.
With Salesforce’s next earnings report scheduled for Dec. 2, investors will likely look for evidence that Agentforce can reignite growth.
CRM stock currently trades at 15.17 times forward earnings, which is a discount compared to industry peers.
Steady Q2 Results
Salesforce released its second-quarter fiscal 2027 results on Aug. 26, for the quarter ended July 31, delivering stronger profitability and continued momentum in its AI and data businesses.
Revenue increased 11% year-over-year (YoY) to $11.3 billion, while subscription and support revenue, Salesforce’s core revenue stream, rose 12% to $10.8 billion. The company’s cRPO increased 14% YoY to $33.5 billion, compared with $29.4 billion a year earlier, while total RPO rose 11% to $66.3 billion.
Profitability also improved substantially. Non-GAAP net income increased to $4.8 billion, and adjusted EPS rose 103% to $5.90. Salesforce reported a non-GAAP operating margin of 34.1%, compared with 34.3%. Cash generation was notably stronger, with operating cash flow rising 71% to $1.3 billion and free cash flow increasing 81% to $1.1 billion.
AI remained a major focus of the quarter. Agentforce and Data 360 ARR reached nearly $3.9 billion, up more than 210% YoY, while Agentforce ARR exceeded $1.5 billion, representing growth of more than 240%. Salesforce also reported 3.2 billion Agentic Work Units delivered during the quarter and said Data 360 processed 104 trillion records, up 355% YoY. These metrics provide additional context for investors assessing whether Salesforce’s AI investments are translating into measurable commercial adoption.
For the outlook, Salesforce raised its fiscal 2027 revenue guidance to $46.1 billion-$46.4 billion. The new forecast implies 11%-12% YoY growth.
Subscription and support revenue growth guidance was raised to slightly above 12%, while full-year non-GAAP operating margin guidance was maintained at 34.3%. Salesforce maintained its operating cash flow and free cash flow growth outlook at approximately 4%-5% YoY.
For the third quarter of fiscal 2027, Salesforce guided for a revenue of $11.42 billion-$11.50 billion, representing 11%-12% YoY growth. The company expects non-GAAP EPS of $3.42-$3.44, while cRPO growth is expected to be approximately 14% YoY.
Analysts predict EPS to rise 32.2% YoY to $12.82 in fiscal 2027, but slide by 10.1% annually to $11.53 in fiscal 2028. Plus, the consensus estimate for the third quarter is at $2.41, which reflects a decline of 9.4% YoY.
What Do Analysts Expect for CRM Stock?
BTIG Research struck a more cautious tone on CRM stock, with analyst Allan Verkhovski maintaining a “Buy” rating but lowering the price target to $250 from $300 on Nov. 18. However, even after the cut, the $250 target implies meaningful upside from Salesforce’s recent price, underscoring that BTIG has not abandoned its longer-term bullish view.
Furthermore, J.P. Morgan analyst Samik Chatterjee reiterated a “Buy” rating on Salesforce on Nov. 17 while maintaining a $265 price target.
However, Citi analyst Tyler Radke reiterated a “Hold” rating on Salesforce on Nov. 16, without assigning a new price target. The cautious stance came as CRM shares faced intensified selling pressure, reflecting growing investor concerns around Salesforce’s growth trajectory and the potential impact of AI on its traditional enterprise-software model.
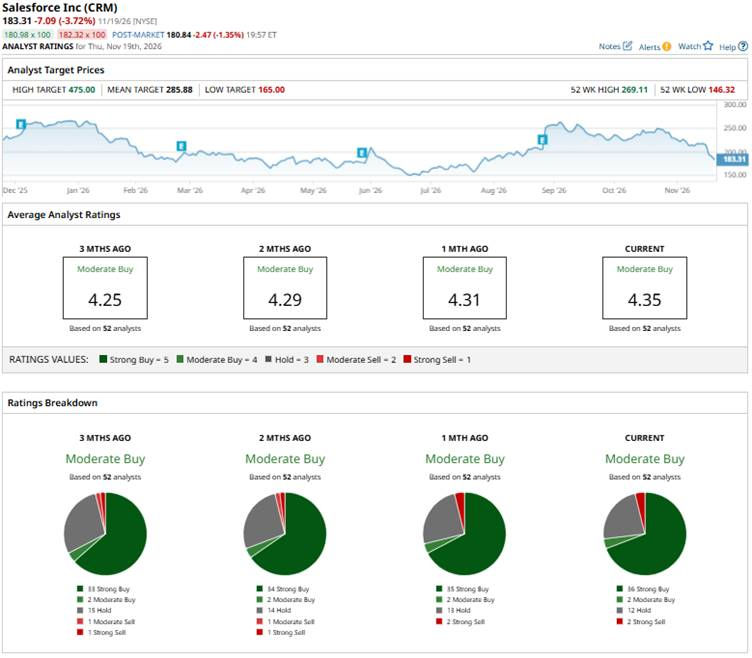
Wall Street is cautiously bullish on CRM stock. Overall, it has a consensus “Moderate Buy” rating. Of the 52 analysts covering the stock, 36 advise a “Strong Buy,” two suggest a “Moderate Buy,” 12 analysts are on the sidelines, giving it a “Hold” rating, and two rate it as a “Strong Sell.”
The average analyst price target for CRM is $285.88, indicating a potential upside of 56%. The Street-high target price of $475 suggests that the stock could rally as much as 159%.
On the date of publication, Subhasree Kar did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.