


EN
Amazon Stock: What Wall Street's Latest Forecasts Say About Its Next Move
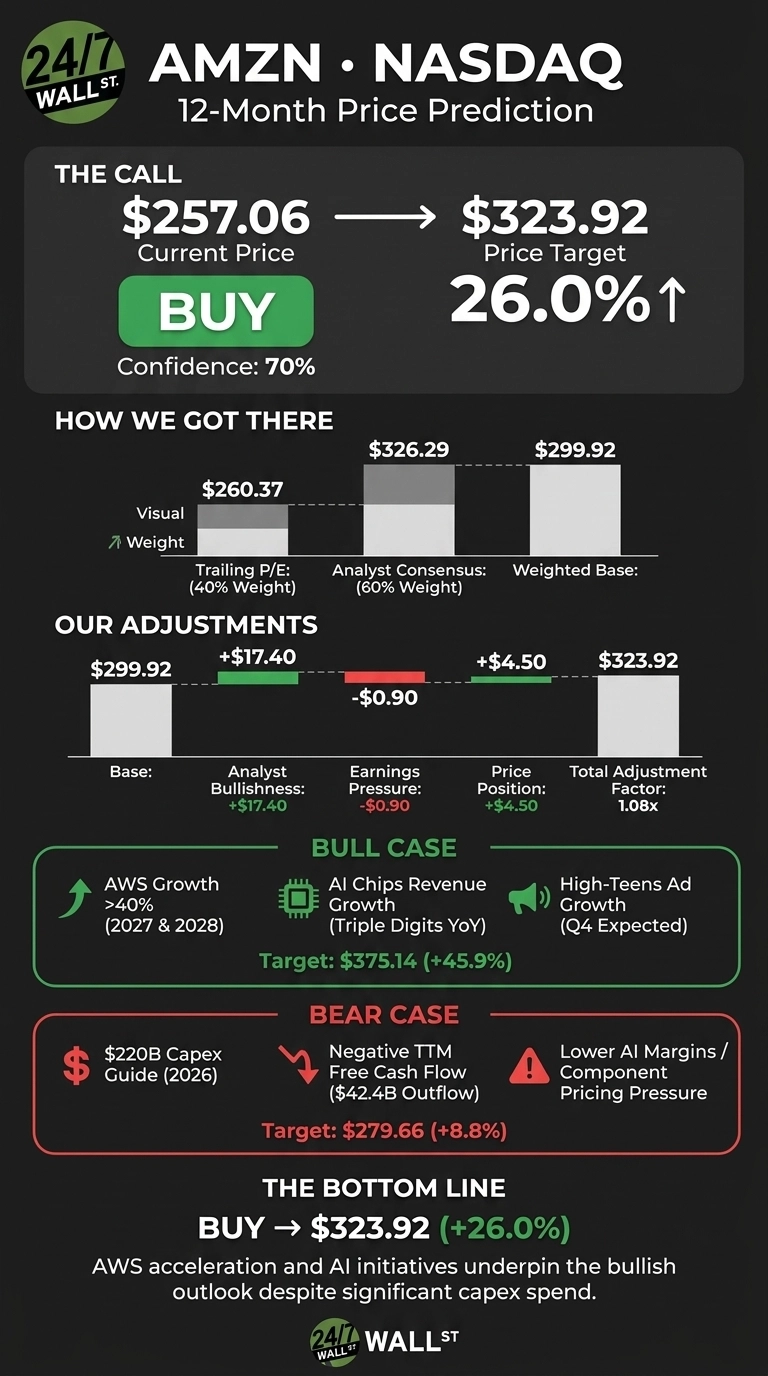
The 24/7 Wall St. price target for Amazon (NASDAQ:AMZN) is $323.92 over the next 12 months. With shares at $257.06, that implies about 26.0% upside. The stock gets a buy rating with 70% confidence.
24/7 Wall St. Price Target Summary Metric Value Current Price $257.06 Price Target from 24/7 Wall St. $323.92 Upside/Downside 26.0% Recommendation BUY Confidence Level 70%That confidence rests on near-unanimous Wall Street support: 16 Strong Buy and 43 Buy ratings against 2 Holds and no Sells, with a consensus target of $326.29. The swing factor is whether AWS growth can justify a historic capex cycle.
AWS Posts Its Fastest Growth in Nearly Five Years While Shares Cool OffAmazon slipped 3.7% over the past week but is up 2.82% over the past month and 11.37% year to date. It sits about 10.5% below its 52-week high of $287.20 and roughly 31.2% above its $196 low.
Barron’s this week called it the best-looking chart in the Magnificent 7, while Forbes reported an SEC filing showing Jeff Bezos donated Amazon shares.
Third-quarter revenue of $201.94 billion rose 12.1%, narrowly missing the $202.20 billion consensus, and GAAP EPS of $1.89 missed the $1.9579 estimate. Underneath, operating income jumped 61.15% to $28.08 billion, a 13.9% margin that management called its highest ever. AWS revenue rose 39% to $45.98 billion.
 24/7 Wall St. Why Bulls See $375 Within Reach
CEO Andy Jassy said, “We believe that AWS can grow north of 40% in each of 2027 and 2028 and be a trillion-dollar revenue business in the next five to 10 years.”
The AWS backlog of $578 billion backs that view, along with Bedrock token volume up nearly 17x and Trainium commitments from OpenAI (2 GW) and Anthropic (up to 5 GW).
External Trainium sales begin late 2027, and management expects ad growth back in the high teens in Q4. The bull case reaches $375.14, about 45.9% above today’s price.
Free Cash Flow Is the Pressure PointHeavy AI spending produced a trailing free cash outflow of $42.4 billion. Q3 capex surged 120.1% to $77.26 billion, 2026 capex is guided near $220 billion, and management expects to spend significantly more in 2027.
All of that has to be powered, cooled, and networked by somebody, which is why we featured seven non-chipmaker suppliers riding the same expansion in a free AI infrastructure report.
Memory costs and lower-margin AI mix could pressure AWS profitability. Still, operating cash flow grew 19.4%, and the Q3 net income dip reflects $9.5 billion in prior-year Anthropic gains. The bear case of $279.66 still sits 8.8% above the current price.
How Amazon Compares to Microsoft and Alphabet in the AI Cloud RaceMicrosoft (NASDAQ:MSFT) runs Azure, AWS’s closest rival. Azure grew 48% last quarter, and Microsoft’s operating margin of 46.8% dwarfs Amazon’s 11.16%, which retail reduces.
Alphabet (NASDAQ:GOOGL) shares the same capex tension. Google Cloud grew 103%, yet Q3 free cash flow was -$9.065 billion. Its low P/E is flattered by equity gains.
Company Trailing P/E Cloud Growth Amazon 36 39% Microsoft 29 48% Alphabet 13 103%Amazon carries the highest trailing multiple, and its retail-diluted operating margin leaves room to expand as AWS grows. That premium depends on AWS lifting consolidated margins.
AWS Momentum Tips Our Model Toward a Buy RatingThe 24/7 Wall St. price target of $323.92 carries a buy rating at 70% confidence. AWS acceleration tips the scale.
The bull case improves if AWS tops 40% growth and Q4 operating income lands within the $28.5 billion to $33.5 billion guide. The bear case gains weight if capex rises while AWS growth stalls. On balance, our model considers the upside above the downside.
Here is where our model projects Amazon could trade over a longer horizon, assuming current growth trends hold.
Year Price Target from 24/7 Wall St. 2026 $264.92 2027 $323.92 2028 $384.12 2029 $429.52 2030 $463.24Amazon needs to keep executing on AWS and retail margins for these projections to hold. Capex payback, external chip sales, or a consumer slowdown could swing the outcome sharply in either direction.