


EN
IT distribution & solutions stocks Q3 recap: Benchmarking ScanSource
Wrapping up Q3 earnings, we look at the numbers and key takeaways for the it distribution & solutions stocks, including ScanSource NASDAQ:SCSC and its peers.
IT Distribution & Solutions will be buoyed by the increasing complexity of IT ecosystems, rising cloud adoption, and demand for cybersecurity solutions. Enterprises are less likely than ever to embark on these complicated journeys solo, and companies in the sector boast expertise and scale in these areas. However, cloud migration also means less need for hardware, which could dent demand for large portions of the product portfolio and hurt margins. Additionally, planning for potentially supply chain disruptions is ongoing, as the COVID-19 pandemic showed how damaging a pause in global trade could be in areas like semiconductor procurement.
The 8 it distribution & solutions stocks we track reported an impressive Q3. As a group, revenues beat analysts’ consensus estimates by 11.5% while next quarter’s revenue guidance was 14.9% above.
Amidst this news, share prices of the companies have had a rough stretch. On average, they are down 5.2% since the latest earnings results.
Weakest Q3: ScanSource NASDAQ:SCSC
Operating as a crucial link in the technology supply chain since 1992, ScanSource (NASDAQ:SCSC) is a hybrid distributor that connects hardware, software, and cloud services from technology suppliers to resellers and business customers.
ScanSource reported revenues of $962.3 million, up 30.1% year on year. This print exceeded analysts’ expectations by 11.7%. Overall, it was a solid quarter for the company with full-year revenue guidance exceeding analysts’ expectations.
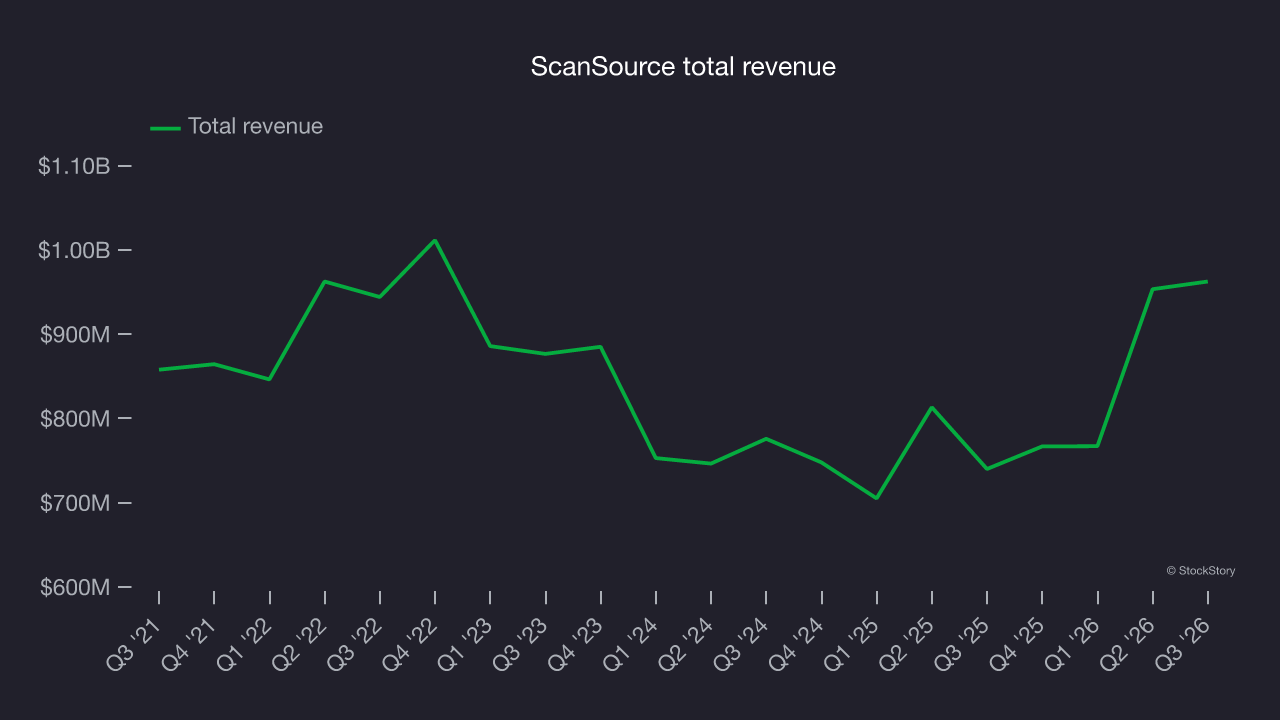
Investor expectations, however, were likely higher than Wall Street’s published projections, leaving some wishing for even better results (analysts’ consensus estimates are those published by big banks and advisory firms, not the investors who make buy and sell decisions). The stock is down 17.3% since reporting and currently trades at $47.15.
Is now the time to buy ScanSource? Access our full analysis of the earnings results here, it’s free.
Best Q3: Avnet (NASDAQ:AVT)
With a century-long history of adapting to technological evolution, Avnet (NASDAQ:AVT) is a global electronic components distributor that connects manufacturers of semiconductors and other electronic parts with businesses that need these components.
Avnet reported revenues of $10.72 billion, up 81.7% year on year, outperforming analysts’ expectations by 16.2%. The business had an exceptional quarter with a beat of analysts’ EPS estimates and a solid beat of analysts’ EPS guidance for next quarter estimates.
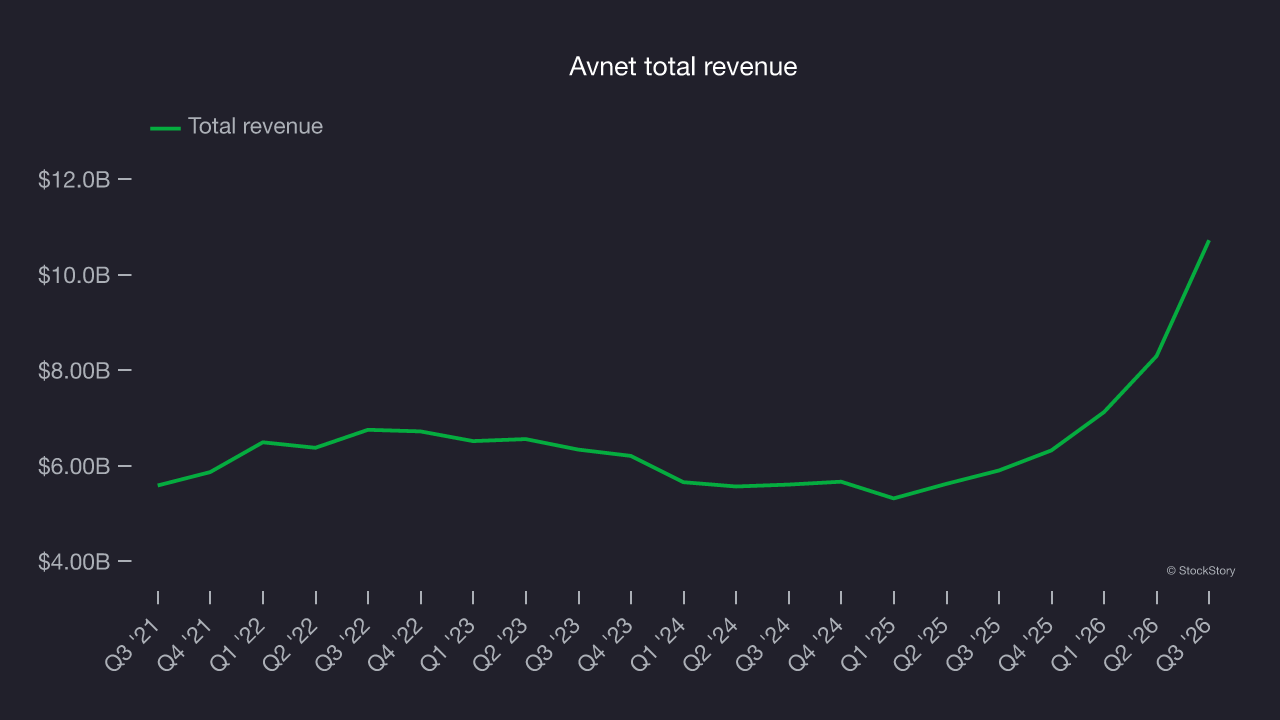
Avnet delivered the biggest analyst estimate beat, highest guidance raise, and fastest revenue growth in the group. Although it had a fine quarter compared to its peers, the market seems unhappy with the results as the stock is down 11.7% since reporting. It currently trades at $78.34.
Is now the time to buy Avnet? Access our full analysis of the earnings results here, it’s free.
CDW (NASDAQ:CDW)
Serving as a crucial bridge between technology manufacturers and end users since 1984, CDW (NASDAQ:CDW) is a multi-brand provider of information technology solutions that helps businesses and public sector organizations select, implement, and manage hardware, software, and IT services.
CDW reported revenues of $6.75 billion, up 17.7% year on year, exceeding analysts’ expectations by 9.3%. It may have had the worst quarter among its peers, but its results were still good as it also locked in a beat of analysts’ EPS estimates.
Interestingly, the stock is up 11.9% since the results and currently trades at $167.61.
Read our full analysis of CDW’s results here.
TD SYNNEX (NYSE:SNX)
Serving as the crucial middleman in the technology supply chain, TD SYNNEX (NYSE:SNX) is a global technology distributor that connects thousands of IT manufacturers with resellers, helping businesses access hardware, software, and technology solutions.
TD SYNNEX reported revenues of $21.56 billion, up 37.7% year on year. This number topped analysts’ expectations by 13.5%. It was an exceptional quarter as it also put up a beat of analysts’ EPS estimates and a solid beat of analysts’ EPS guidance for next quarter estimates.
The stock is down 22.2% since reporting and currently trades at $224.05.
Read our full, actionable report on TD SYNNEX here, it’s free.
ePlus (NASDAQ:PLUS)
Starting as a financing company in 1990 before evolving into a full-service technology provider, ePlus (NASDAQ:PLUS) provides comprehensive IT solutions, professional services, and financing options to help organizations optimize their technology infrastructure and supply chain processes.
ePlus reported revenues of $667.9 million, up 9.7% year on year. This print beat analysts’ expectations by 5%. It was an exceptional quarter as it also logged a beat of analysts’ EPS estimates.
ePlus had the weakest performance against analyst estimates and slowest revenue growth among its peers. The stock is up 16% since reporting and currently trades at $95.66.
Read our full, actionable report on ePlus here, it’s free.
Market update
Over the past year, investors have been forced to repeatedly answer the same question: What is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Top 5 Growth Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.