


EN
Q3 earnings highlights: Fortrea vs the rest of the drug development inputs & services stocks
Quarterly earnings results are a good time to check in on a company’s progress, especially compared to its peers in the same sector. Today we are looking at Fortrea NASDAQ:FTRE and the best and worst performers in the drug development inputs & services industry.
Companies specializing in drug development inputs and services play a crucial role in the pharmaceutical and biotechnology value chain. Essential support for drug discovery, preclinical testing, and manufacturing means stable demand, as pharmaceutical companies often outsource non-core functions with medium to long-term contracts. However, the business model faces high capital requirements, customer concentration, and vulnerability to shifts in biopharma R&D budgets or regulatory frameworks. Looking ahead, the industry will likely enjoy tailwinds such as increasing investment in biologics, cell and gene therapies, and advancements in precision medicine, which drive demand for sophisticated tools and services. There is a growing trend of outsourcing in drug development for nimbleness and cost efficiency, which benefits the industry. On the flip side, potential headwinds include pricing pressures as efforts to contain healthcare costs are always top of mind. An evolving regulatory backdrop could also slow innovation or client activity.
The 8 drug development inputs & services stocks we track reported a favorable Q3. As a group, revenues beat analysts’ consensus estimates by 2.7%.
While some drug development inputs & services stocks have fared somewhat better than others, they have collectively declined. On average, share prices are down 3.2% since the latest earnings results.
Fortrea NASDAQ:FTRE
Spun off from Labcorp in 2023 to focus exclusively on clinical research services, Fortrea (NASDAQ:FTRE) is a contract research organization that helps pharmaceutical, biotech, and medical device companies develop and bring their products to market through clinical trials and support services.
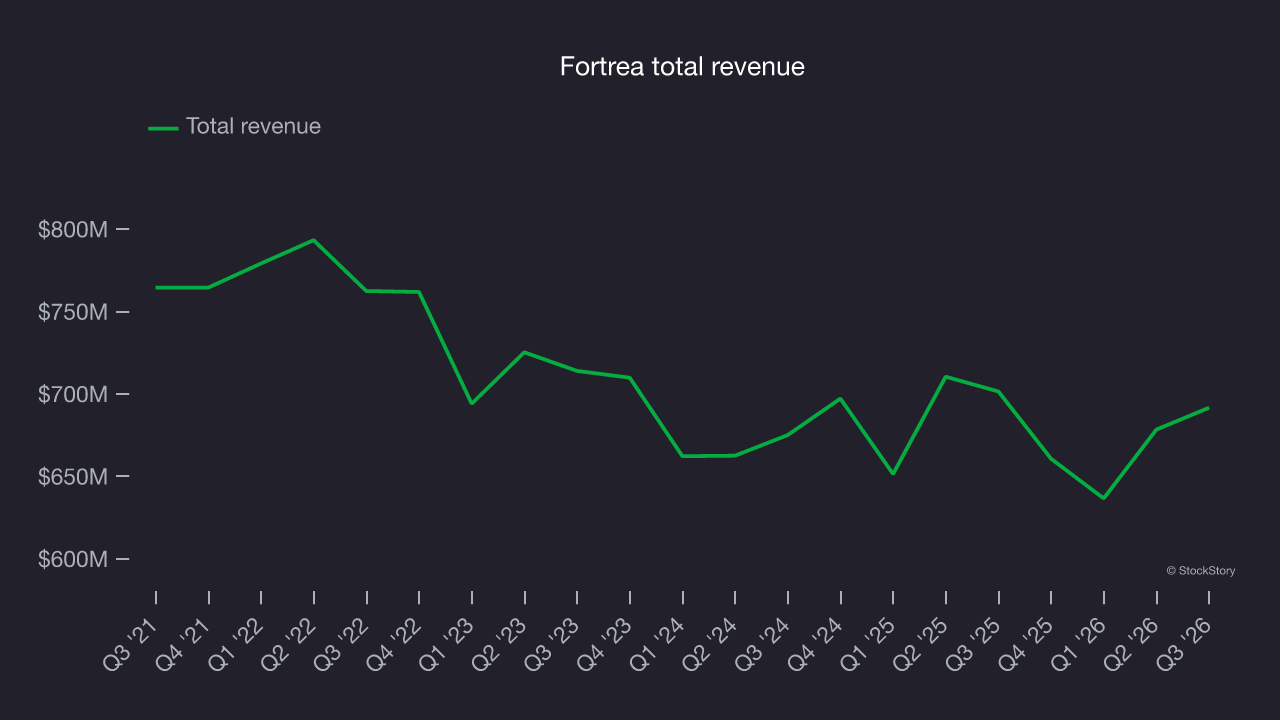
Fortrea reported revenues of $691.5 million, down 1.4% year on year. This print exceeded analysts’ expectations by 3.1%. Overall, it was a favorable quarter for the company with a beat of analysts’ EPS estimates and full-year revenue guidance slightly topping analysts’ expectations.
“Fortrea delivered another quarter of progress on our return-to-growth strategy, reflecting stronger commercial execution, continued operational improvements and financial discipline,” said Anshul Thakral, CEO of Fortrea. “Our sustained bookings momentum is building a foundation for growth, while targeted investments in early clinical development and technology enhance our ability to deliver differentiated value to clients. I’m proud of how Fortrea’s teams around the world are embracing our future direction while delivering for clients today. Our continued execution against our priorities gives us confidence to raise the midpoints of full-year guidance while narrowing ranges. We remain focused on translating stronger demand into revenue growth, margin expansion and long-term shareholder value.”
Investor expectations, however, were likely higher than Wall Street’s published projections, leaving some wishing for even better results (analysts’ consensus estimates are those published by big banks and advisory firms, not the investors who make buy and sell decisions). The stock is down 22.1% since reporting and currently trades at $20.15.
Is now the time to buy Fortrea? Access our full analysis of the earnings results here, it’s free.
Best Q3: Azenta (NASDAQ:AZTA)
Serving as the guardian of some of medicine's most valuable materials, Azenta (NASDAQ:AZTA) provides biological sample management, storage, and genomic services that help pharmaceutical and biotechnology companies preserve and analyze critical research materials.
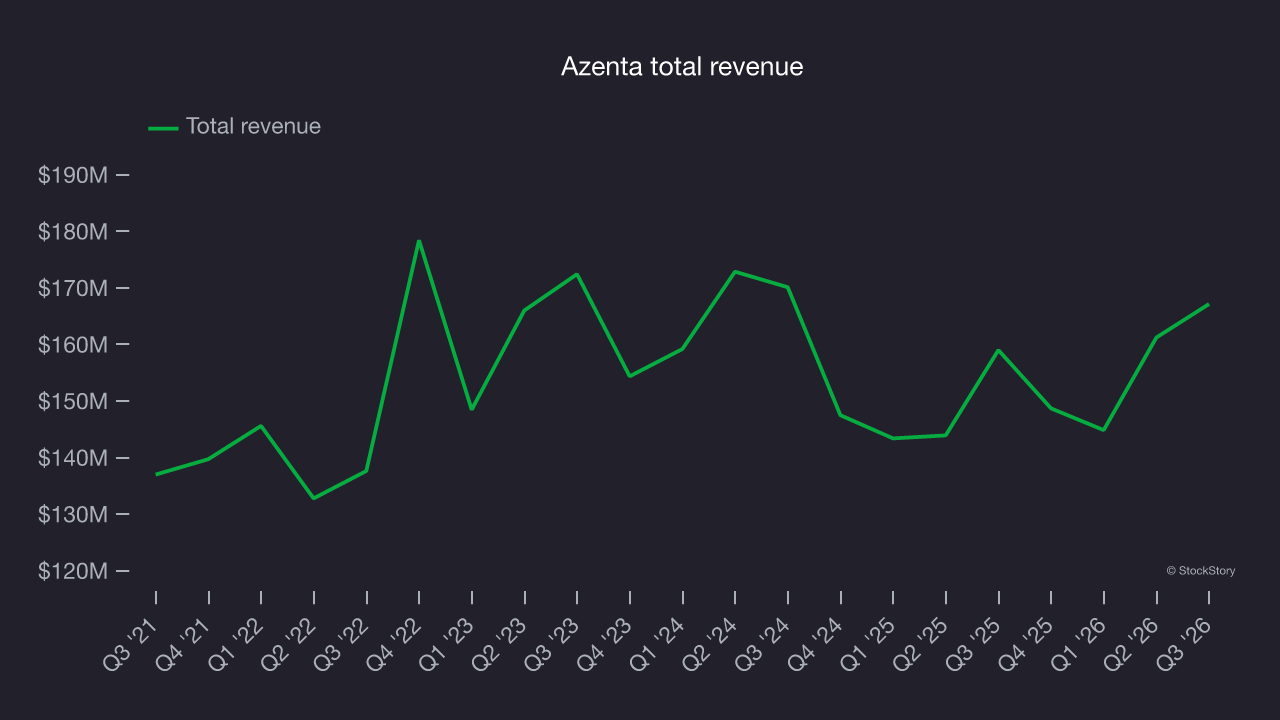
Azenta reported revenues of $167.1 million, up 5.1% year on year, outperforming analysts’ expectations by 4.3%. The business had an impressive quarter with a beat of analysts’ EPS estimates.
The market seems happy with the results as the stock is up 14.9% since reporting. It currently trades at $46.53.
Is now the time to buy Azenta? Access our full analysis of the earnings results here, it’s free.
Weakest Q3: IQVIA (NYSE:IQV)
Created from the 2016 merger of Quintiles (a clinical research organization) and IMS Health (a healthcare data specialist), IQVIA (NYSE:IQV) provides clinical research services, data analytics, and technology solutions to help pharmaceutical companies develop and market medications more effectively.
IQVIA reported revenues of $4.43 billion, up 8% year on year, exceeding analysts’ expectations by 1.5%. Still, it was a mixed quarter as it posted full-year EPS guidance in line with analysts’ estimates.
As expected, the stock is down 7.3% since the results and currently trades at $253.73.
Read our full analysis of IQVIA’s results here.
Repligen (NASDAQ:RGEN)
With over 13 strategic acquisitions since 2012 to build its comprehensive bioprocessing portfolio, Repligen (NASDAQ:RGEN) develops and manufactures specialized technologies that improve the efficiency and flexibility of biological drug manufacturing processes.
Repligen reported revenues of $209.3 million, up 10.9% year on year. This print surpassed analysts’ expectations by 1.1%. Overall, it was a solid quarter as it also logged a beat of analysts’ EPS estimates and a solid beat of analysts’ organic revenue estimates.
Repligen pulled off the highest full-year guidance raise of the whole group. The stock is down 5.3% since reporting and currently trades at $170.58.
Read our full, actionable report on Repligen here, it’s free.
West Pharmaceutical Services (NYSE:WST)
Founded in 1923 and serving as a critical link in the pharmaceutical supply chain, West Pharmaceutical Services (NYSE:WST) manufactures specialized packaging, containment systems, and delivery devices for injectable drugs and healthcare products.
West Pharmaceutical Services reported revenues of $874.5 million, up 8.7% year on year. This number beat analysts’ expectations by 5.7%. It was a very strong quarter as it also produced a solid beat of analysts’ full-year EPS guidance estimates and a beat of analysts’ EPS estimates.
West Pharmaceutical Services delivered the biggest analyst estimate beat in the group. The stock is down 3.5% since reporting and currently trades at $389.67.
Read our full, actionable report on West Pharmaceutical Services here, it’s free.
Market update
Over the past year, investors have been forced to repeatedly answer the same question: What is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Strong Momentum Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.