


EN
Does Reaffirmed Guidance Change The Bull Case For NRG Energy Stock (NRG)?
- NRG Energy reported third quarter 2026 sales of US$9,466 million and net income of US$561 million, reaffirmed 2026 earnings guidance, introduced 2027 guidance, and updated progress on its ongoing share buyback program.
- The reaffirmed earnings outlook alongside continued share repurchases reflects management confidence in NRG Energy's cash generation as it prepares for a planned US$4 billion gas asset sale.
- We will look at how NRG Energy's reaffirmed earnings guidance reshapes the earlier investment narrative built around leverage and cash flow.
Scan beyond NRG Energy and size up other potential value setups with our hand-picked 35 high quality undervalued stocks that currently screen well on cash generation and balance sheet strength.
NRG Energy Investment Narrative Recap
To own NRG Energy, you need to believe its enlarged power and retail platform can turn today’s cash generation into durable earnings while managing a heavy debt load. The latest quarter shows solid profitability and reaffirmed 2026 guidance, so the immediate earnings story is intact. In the near term, the key catalyst remains execution on operations and cash conversion from the expanded asset base.
The biggest risk still sits on the balance sheet. Interest expenses are not well covered by earnings and leverage remains elevated after the LS Power deal. Recent results and guidance do not remove that pressure. They simply buy time for NRG Energy to demonstrate that earnings and free cash flow can comfortably support debt and planned asset sales.
The reaffirmed 2026 earnings guidance and new 2027 net income range look most relevant here. Management now expects net income of US$1,325 million to US$1,755 million in 2026 and US$1,355 million to US$1,765 million in 2027. That sets a clearer yardstick for how the LS Power assets, retail operations, and Vivint Smart Home need to perform as a combined platform.
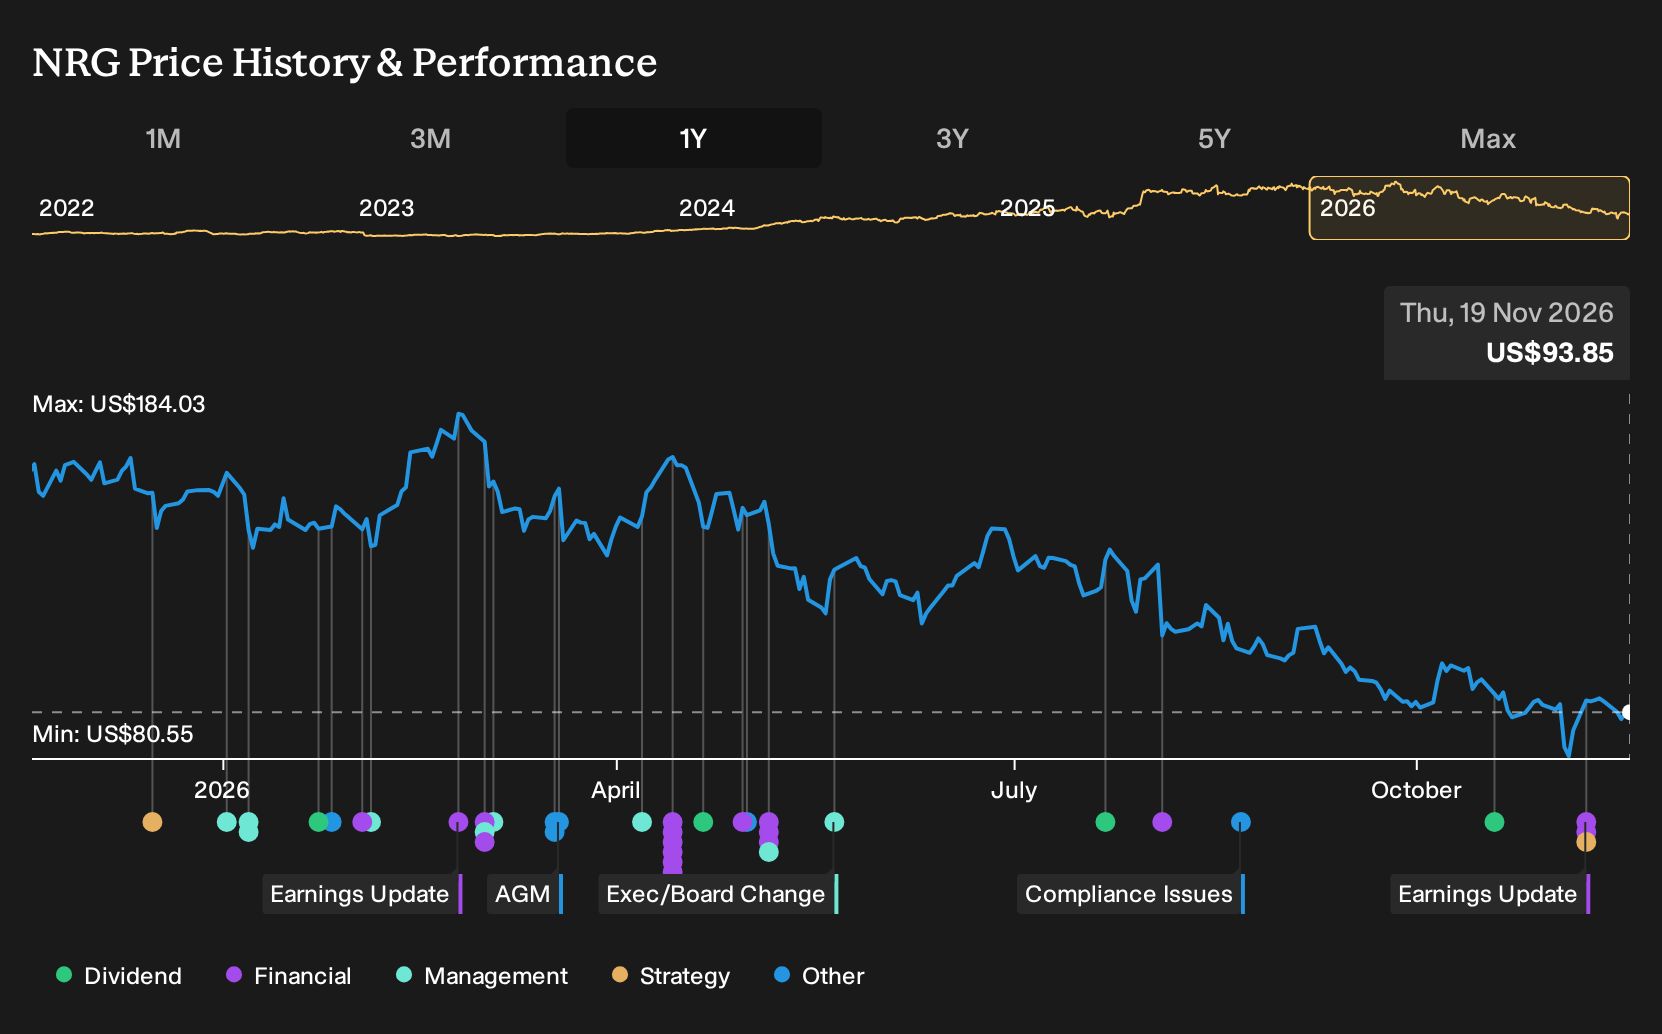
For catalysts and risks, that guidance matters more than the headline share price move. According to John_Eric, an investor in the Simply Wall St Community, the central question is whether the enlarged generation and retail footprint earns enough after financing costs to justify the acquisition and leverage. The updated ranges provide concrete numbers to track against that thesis as NRG Energy advances the planned US$4b gas asset sale and continues working through its buyback commitments.
In the working narrative from John_Eric, the US$150.00 fair value for NRG Energy rests on a model that pairs 23.7% annual revenue growth with a 2.4% future profit margin. Together, these figures imply enough earnings power to justify that valuation once acquisition effects and required investment are fully absorbed.
Uncover why NRG Energy's fair value indicates a 60% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame the 1.2 GW hyperscaler project as a key swing factor for NRG Energy. Before this latest update, the top cohort expected revenue to reach about US$41.0b and earnings of US$2.8b by 2029. That is a very bullish script. These projections were set before the new quarterly results and guidance, so you may want to compare this upbeat story with more cautious views and decide which assumptions feel realistic to you.
Explore 5 other NRG Energy fair value estimates, including one that suggests as much as 381% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your NRG Energy research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for NRG Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NRG Energy's overall financial health at a glance.
Looking for more investment ideas beyond NRG Energy?
Once you have a view on NRG Energy, it often helps to widen the lens and compare it with other opportunities that fit different goals, risk levels, and income needs. The Simply Wall St Screener can help you quickly filter for shares that match the kind of portfolio you want to build.
- If you want a focus on steady balance sheets and resilient fundamentals, start with this list of solid balance sheet and fundamentals (25 results) to see which businesses rank well on financial strength.
- If your priority is limiting downside risk, use the 30 resilient stocks with low risk scores to zero in on companies that our models assess as having relatively lower risk profiles.
- If you are hunting for opportunities the market might be overlooking, the 19 high quality undiscovered gems can surface lesser known stocks with solid underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com