


EN
Amkor Technology (AMKR) Lifts Its Dividend As The Undervalued Case Faces A Test
Amkor Technology (AMKR) has just nudged its quarterly cash dividend higher, a small per share change that still matters for investors who focus on steady cash returns from semiconductor service providers.
That dividend tweak lands at a tricky moment for Amkor Technology, with the share price at about $34.13 after falling around 18% over the past month and roughly 32% over the past quarter, even though the 1 year total shareholder return is about 13.8% and closer to 56.9% over five years.
Scan how Amkor Technology's dividend move compares with other chip-related opportunities by running your filters through our handpicked 53 AI infrastructure stocks.
Amkor Technology now trades well below the average analyst target of about $65.70, even after Argus cut its own goal to $32. Is that a bargain, or is the market correctly pricing in the risks?
Most Popular Narrative: 48% Undervalued
On the Simply Wall St analyst consensus Narrative, Amkor Technology screens as undervalued, with a fair value of about $66 against a last close of $34.13. That view is built on explicit revenue, earnings and discount rate assumptions rather than a single opinion.
Acceleration in AI data center and high performance computing programs, including HDFO CPU ramps and multiple 2.5D and high density fan out engagements, is increasing demand for advanced packaging. This can support higher revenue and a richer mix that benefits gross margin and earnings.
See why 24 investors see Amkor Technology as 48% undervalued.
The analyst consensus Narrative on Simply Wall St ties that AI packaging demand, long duration NVIDIA and TSMC agreements, and global factory build out into a discounted cash flow style model that uses an 11.16% revenue growth rate, an 8.25% net margin and a 12.54% discount rate to land at a $66 fair value. It also bakes in a 27.78x future P/E multiple on projected 2029 earnings, which sits below the 43.5x multiple cited for the wider US semiconductor group in the Narrative. This reflects a view that Amkor Technology could justify a higher valuation than today without matching the richest parts of the sector.
Result: Fair Value of $66 (UNDERVALUED)
Still, the narrative can break if underused new plants weigh on margins, or if ongoing Communications softness keeps Amkor Technology’s largest end market under pressure.
Find out about the key risks to this Amkor Technology narrative.
Another View: Amkor Technology On Simple Earnings Math
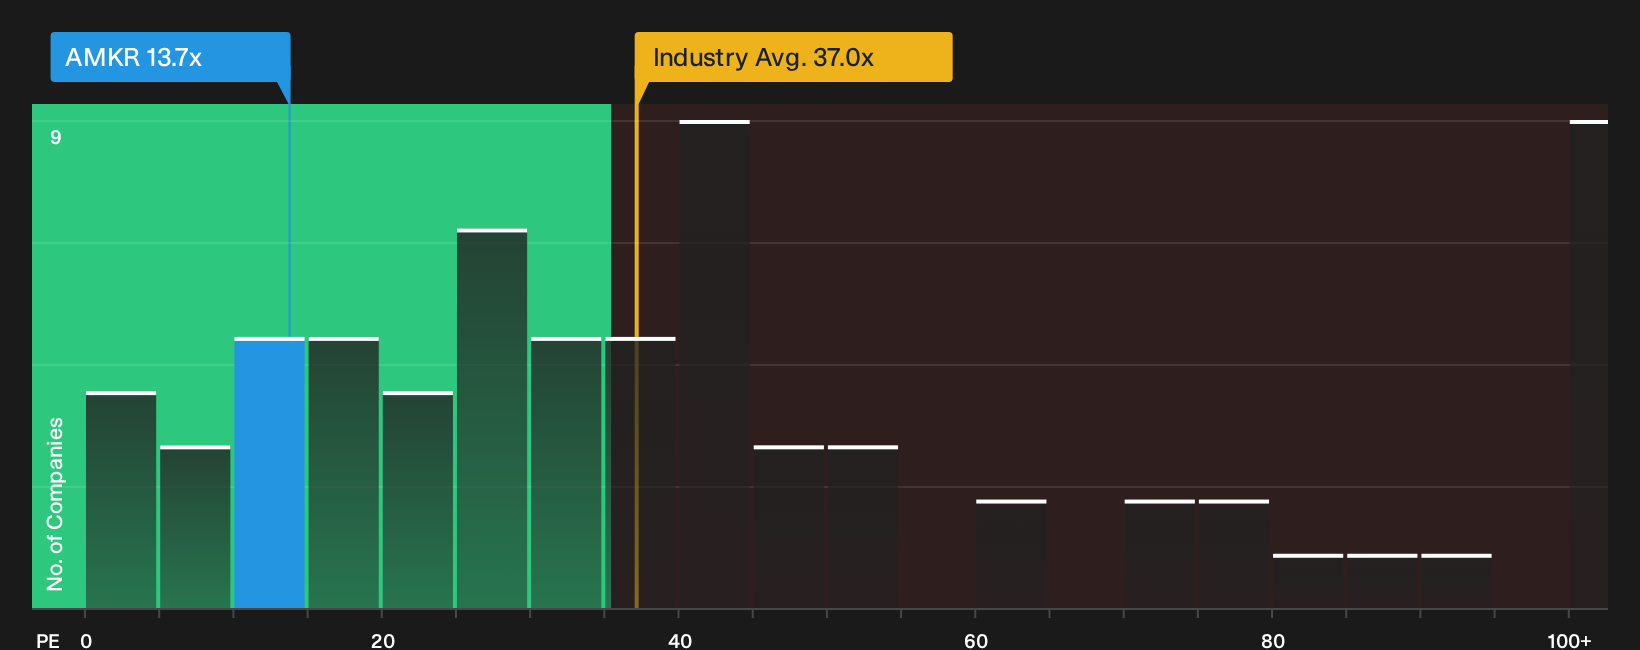
The narrative model points to a $66 fair value, yet a plain P/E check tells a different story. Amkor Technology trades on 13.7x earnings, far below the US Semiconductor group at 37x and peers at 39x, while the fair ratio sits at 29x. That gap could either signal mispricing or reflect very real risk. Which side do you think the market is on?
Before leaning on any one yardstick, it helps to see what the numbers imply in detail, and how much room there might be for that fair ratio to narrow toward or away from the current 13.7x level. See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Amkor Technology for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed tone around Amkor Technology leaves you unsure, consider taking a closer look at the numbers yourself by weighing both the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Amkor Technology?
Do not just park your attention on one ticker. Spread your research and give yourself options that match different risk levels, income needs and growth angles.
- Target steady compounding by scanning a 30 resilient stocks with low risk scores that aims to prioritise resilience when markets turn choppy.
- Hunt for mispriced opportunities by checking a 35 high quality undervalued stocks that filters for strong fundamentals at what may be reasonable entry points.
- Boost your watchlist for income by reviewing a 8 dividend fortresses that highlights higher yielding payers with support from the underlying business.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com