


EN
Learn Why The Bull Case For Agnico Eagle Mines Stock Could Change Following Metals Sell Off
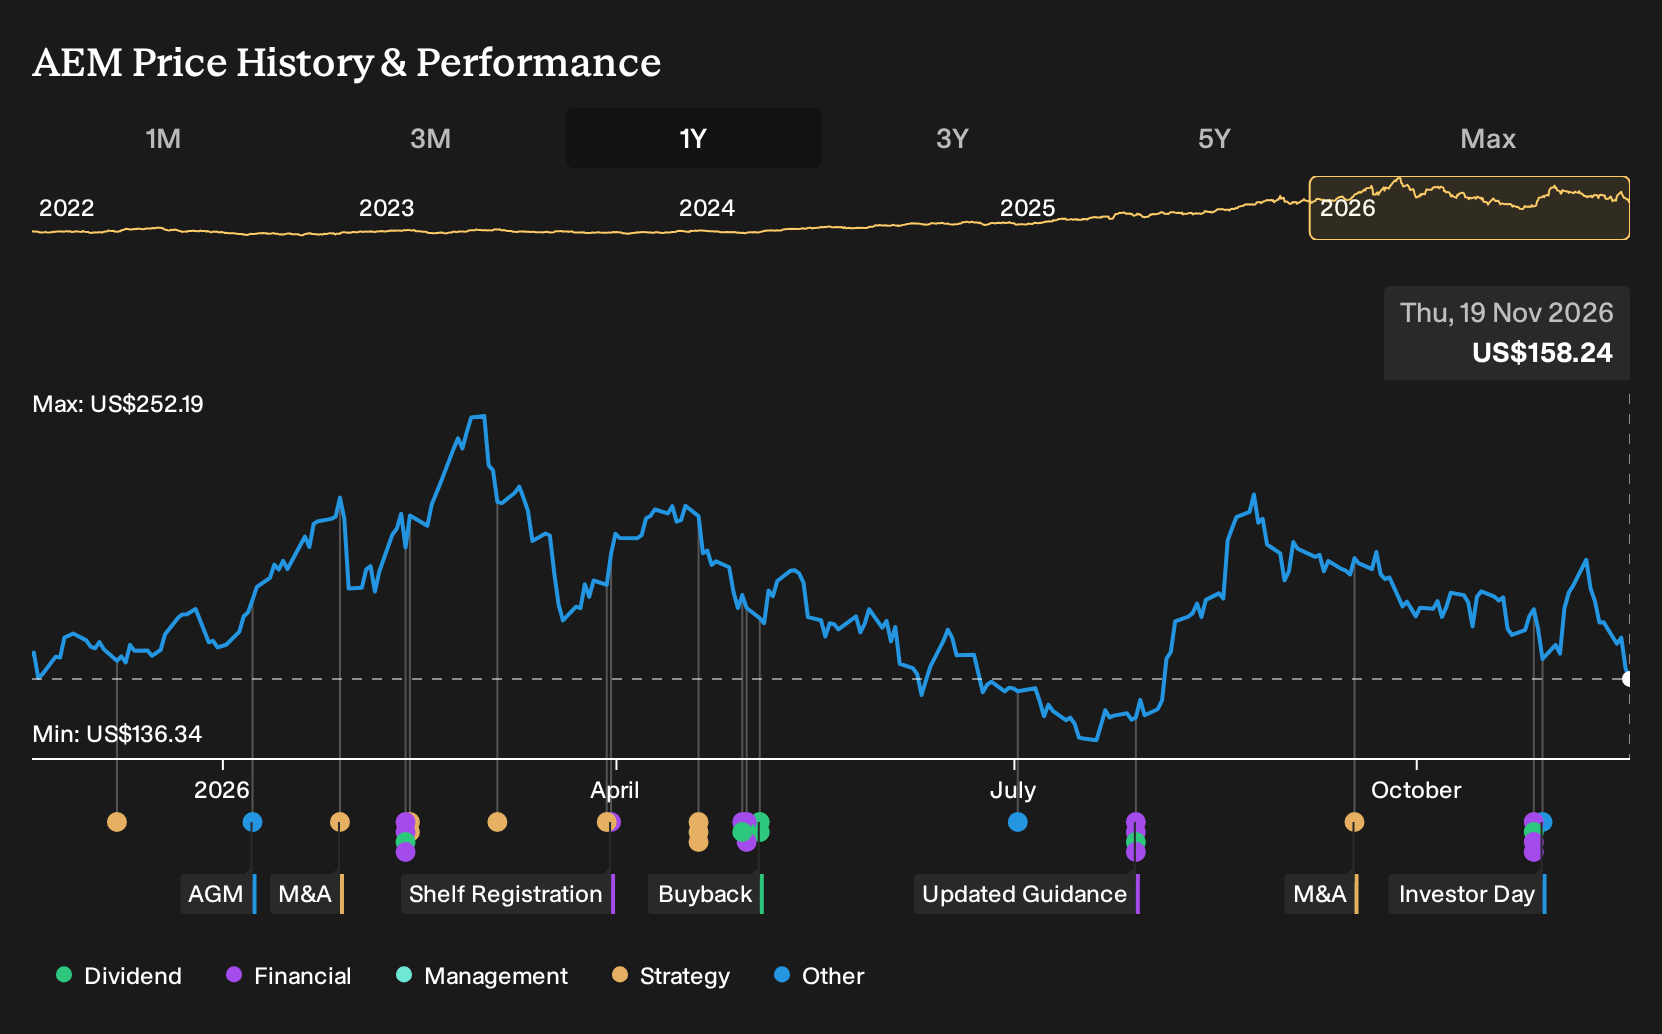
- Agnico Eagle Mines has been caught in a broad sell-off in precious and industrial metals, with gold, silver, copper, and platinum prices hitting year-plus lows and pulling large producers lower.
- The pressure on metals pricing lands on top of Agnico Eagle Mines' existing cost headwinds, where inflation and higher sustaining spend are already squeezing operating margins.
- This article examines how Agnico Eagle Mines' investment narrative shifts when sector-wide metals weakness collides with rising cost pressure.
See how Agnico Eagle Mines compares with other large producers affected by the same metals sell-off by checking the hand-picked 33 elite gold producer stocks.
Agnico Eagle Mines Investment Narrative Recap
To own Agnico Eagle Mines, you need to be comfortable with a gold producer that is pushing hard on long lead time growth while dealing with near term cost pressure and weaker metals pricing. The key near term swing factor is how effectively operations manage inflation and higher sustaining spend after all in sustaining costs moved toward the top of guidance.
The biggest risk right now sits in margins getting squeezed if gold prices stay under pressure while cash costs, labor, diesel, and royalties stay elevated. According to lenny67, an investor in the Simply Wall St Community, the Canadian Malartic production gap and empty mill capacity remain important medium term issues, and the recent metals sell off does not directly change that engineering problem.
The most relevant new development for this setup is the Canadian impact assessment process for the proposed Marban open pit mine in Quebec, which would not include on site processing or tailings storage and is scoped for a 9 year mine life. That project, if it advances, could help supply future ore into Agnico Eagle Mines processing network and partially address regional throughput concerns around Canadian Malartic.
Marban also highlights the execution challenge. Progress depends on meeting tailored information and study guideline requirements and securing support from regulators and Indigenous communities, while the rest of the portfolio already demands more than US$3.5b of planned capital in 2027 and 2028. The operational catalyst is clear, but so is the risk of permitting, capital allocation, and schedule slippage stacking on top of current cost headwinds.
On lenny67’s numbers, the narrative’s fair value of $123,914 comes from applying a 311.0% yearly revenue growth assumption and a 39.5% future profit margin. Together, these figures imply a very large expansion in earnings power if Agnico Eagle Mines and Renforth’s setup play out as outlined.
Uncover why Agnico Eagle Mines' fair value indicates a 78208% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame the recent metals sell off as a temporary shock against a longer build out story at Agnico Eagle Mines. Before this slump, they were pencilling in revenue of $17.7b and earnings of $7.0b by 2029, tied to major project execution. Those upbeat forecasts were set before this week’s volatility, so you should expect opinions to shift and explore a range of updated views.
Explore 5 other Agnico Eagle Mines fair value estimates, including one that suggests as much as 78208% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Agnico Eagle Mines research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Agnico Eagle Mines. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easier to evaluate Agnico Eagle Mines' overall financial health at a glance.
Looking for more Agnico Eagle Mines investment ideas?
If you want to put Agnico Eagle Mines in context and widen your opportunity set, using the Simply Wall St Screener can help you compare this miner against a broader set of listed businesses with different profiles and risk levels.
- If you want potential mispriced quality on your radar, scan through a curated set of 35 high quality undervalued stocks that pair stronger fundamentals with more modest valuations.
- If resilience matters more to you than headline upside, focus on a 30 resilient stocks with low risk scores that screens for sturdier balance sheets and steadier risk scores.
- If you care about balance sheet strength first and everything else second, start with a list of solid balance sheet and fundamentals (25 results) to narrow the field to companies with more robust financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com