


EN
Danaher (DHR) Lifts Growth Guidance, Is The Stock Still Cheap?
Danaher’s higher growth guidance and fresh FDA clearance
Danaher (DHR) has raised its core growth guidance to 4% to 5% for next year and is steering more capital into diagnostics-focused R&D, backed by an active acquisition pipeline. Recent FDA clearance for Masimo’s smartSedLine system adds another clinical asset.
Recent trading tells a mixed story. Danaher’s share price is up 4% over the past 90 days and 1.5% over the past month, yet is slightly down year to date. The 1 year total shareholder return of 3.2% and 3 year total shareholder return of 4.7% remain modest as investors weigh the higher growth guidance and fresh FDA news against a still cautious longer term track record.
Spot patterns in how Danaher leans into diagnostics-led growth by comparing it with a hand-picked set of healthcare groups, screened for resilient fundamentals and balance sheets using the list of solid balance sheet and fundamentals (25 results).After a modest 1 year return and a 5 year record that still trails, along with a recent 90 day climb and higher growth guidance, does Danaher’s current valuation still leave enough upside for new buyers?
Most Popular Narrative: 12% Undervalued
Danaher’s last close at $227.56 sits below the analyst consensus Narrative fair value of about $259.90, implying a discount in the current price. The analyst consensus Narrative on Simply Wall St ties that gap to specific growth, margin and cash flow expectations that extend through 2029 and anchor the updated $259.90 fair value using an 8.37% discount rate.
Accelerating demand for biologics and single use bioprocessing equipment, reflected in more than 30% year over year growth in bioprocessing equipment orders in early 2026 and mid teens order growth for consumables and equipment in Q2 2026, supports expectations for a multiyear capacity investment and onshoring cycle that can lift Biotechnology segment revenue and operating leverage.
What is driving that 12% gap between price and fair value in the Narrative, and how does it link to Danaher’s mix of recurring diagnostics and bioprocessing revenue, 83 investors see Danaher as 12% undervalued.
Result: Fair Value of $259.90 (UNDERVALUED)
Still, the Danaher narrative can unravel if China pricing pressure on diagnostics deepens or if respiratory testing weakness lingers longer than analysts currently assume.
Find out about the key risks to this Danaher narrative.
Another View: Danaher Through The P/E Lens
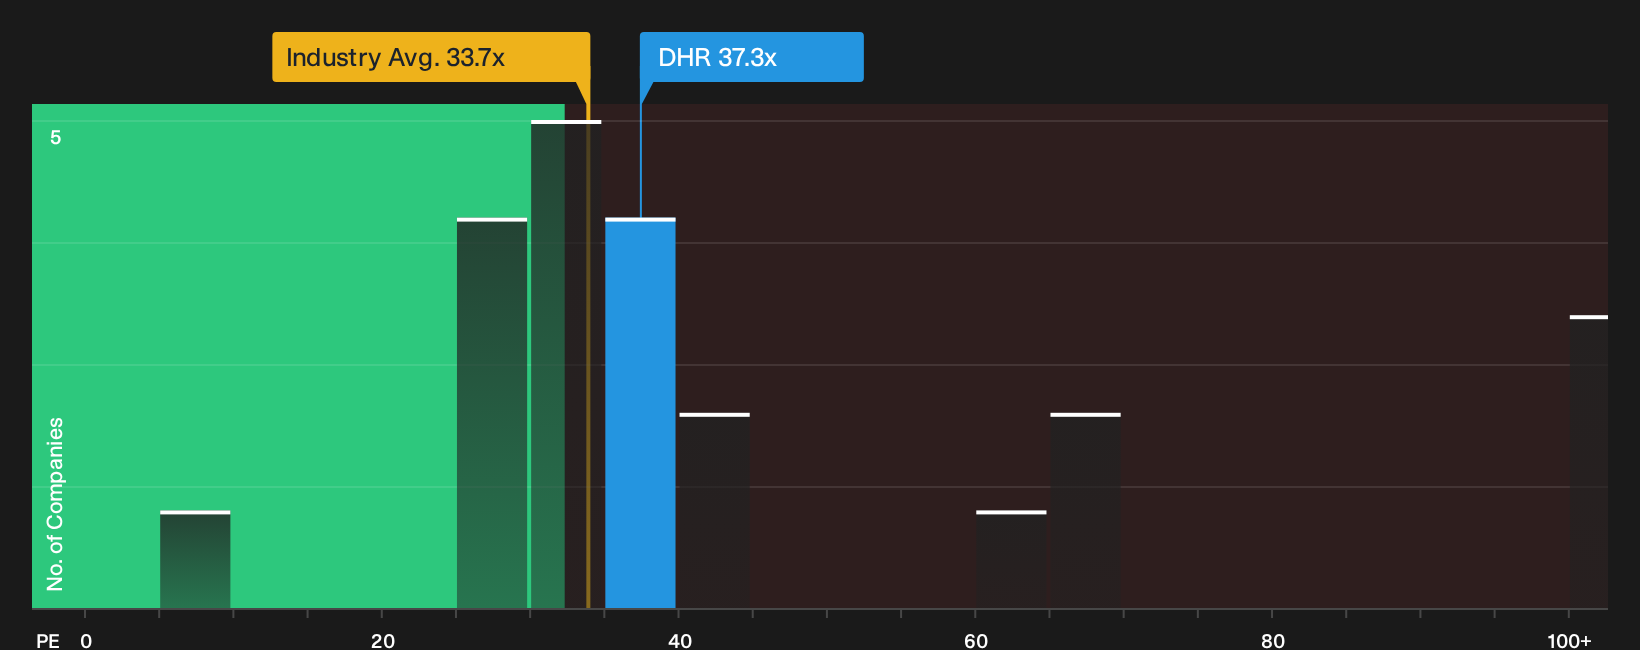
Danaher may look 12% below the analyst fair value, yet the current P/E of 37.3x sits above the Global Life Sciences average at 33.7x and above its own fair ratio of 35x. That richer tag points to less margin for error. Is the market already paying up for the recovery story?
To stress test how much room that leaves in the current price, it helps to walk through how the earnings multiple compares with both peers and the fair ratio, and what that gap might mean for upside or downside if sentiment cools. See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Danaher can pull you in both directions, so pressure test the data yourself and decide where you stand on the risk reward balance. To weigh up both sides quickly, start by reviewing the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Danaher?
If Danaher has sharpened your focus on quality, use that momentum and scan for other opportunities now instead of waiting for the next headline to push you.
- Target resilient balance sheets and steady fundamentals by reviewing our list of solid balance sheet and fundamentals (25 results) as a base for your watchlist.
- Hunt for quality at a discount with the 36 high quality undervalued stocks and see which businesses offer more potential for every dollar you commit.
- Lock in cash flow from equities by scanning the 8 dividend fortresses and sort for companies aiming to sustain yields above 5%.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com