


EN
Is Wall Street Bullish or Bearish on Simon Property Stock?
Indianapolis, Indiana-based Simon Property Group, Inc. (SPG) is a self-administered and self-managed real estate investment trust (REIT). Valued at $74.6 billion by market cap, the company owns, develops, and manages retail real estate properties including regional malls, outlet centers, community/lifestyle centers, and international properties.
Shares of this real estate giant have outperformed the broader market over the past year. SPG has gained 25% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 8%. In 2026, SPG stock is up 21.7%, surpassing the SPX’s 4.8% rise on a YTD basis.
Zooming in further, SPG’s outperformance is also apparent compared to the State Street Real Estate Select Sector SPDR ETF (XLRE). The exchange-traded fund has gained about 5.9% over the past year. Moreover, SPG’s double-digit gains on a YTD basis outshine the ETF’s 6.3% returns over the same time frame.
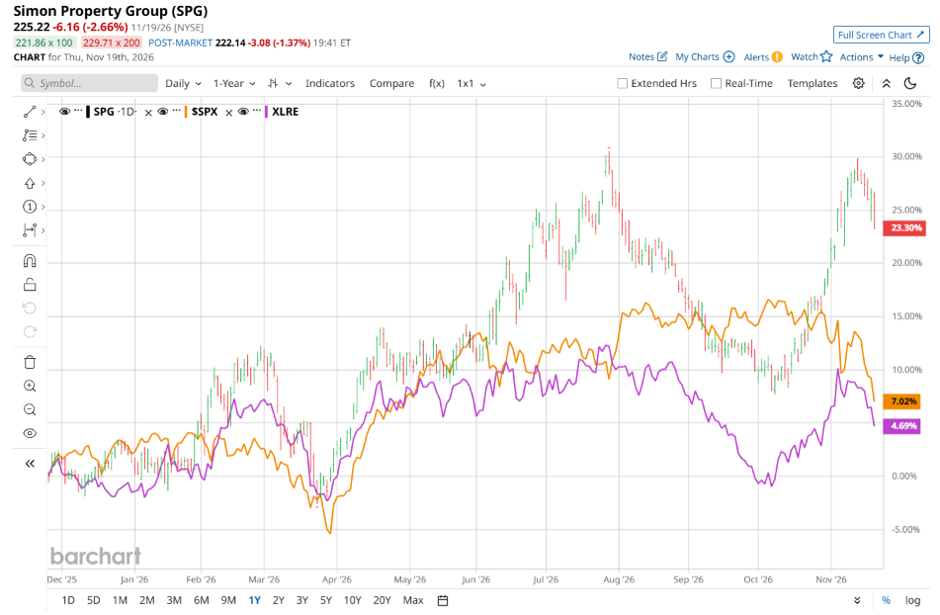
SPG has delivered a significant rally, substantially outperforming both the broader market and its real estate sector peers, driven by resilient occupancy rates, solid funds from operations (FFO) growth, and steady dividend increases.
On Nov. 5, SPG shares closed down marginally after reporting its Q3 results. Its FFO of $3.37 per share surpassed Wall Street expectations of $3.32 per share. The company’s revenue was $1.8 billion, beating Wall Street forecasts of $1.7 billion. SPG expects full-year FFO in the range of $13.30 to $13.40 per share.
For the current fiscal year, ending in December, analysts expect SPG’s FFO per share to grow 4.9% to $13.35 on a diluted basis. The company’s FFO surprise history is impressive. It beat the consensus estimate in each of the last four quarters.
Among the 22 analysts covering SPG stock, the consensus is a “Moderate Buy.” That’s based on seven “Strong Buy” ratings, and 15 “Holds.”
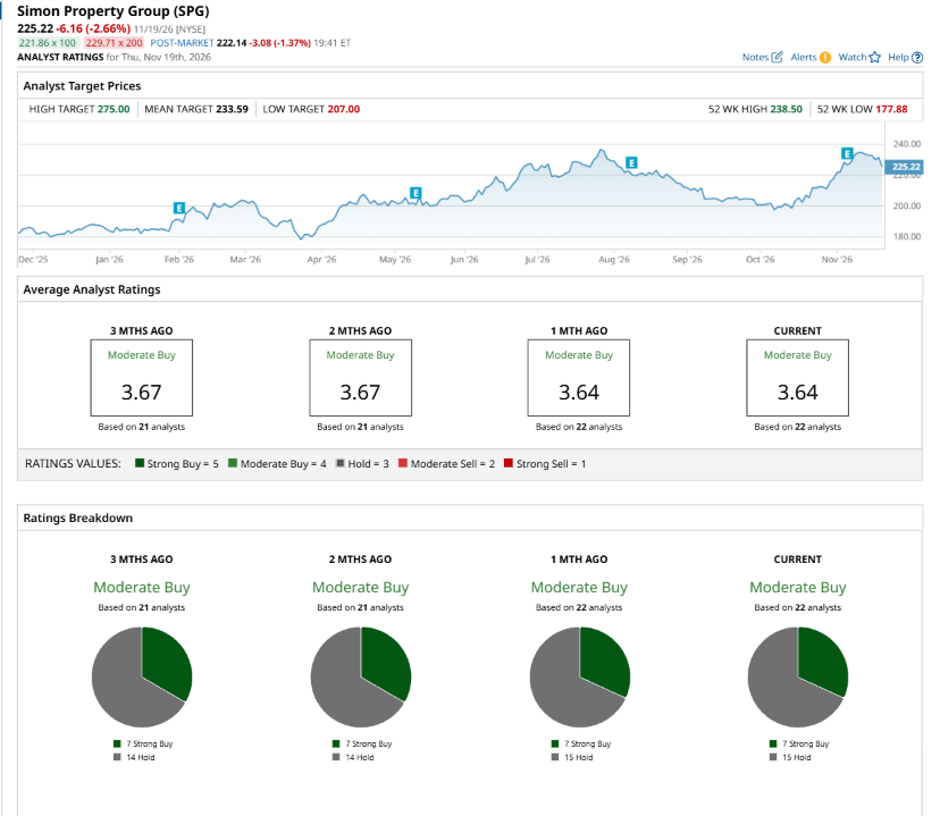
The configuration has been relatively stable over the past three months.
On Nov. 17, Citigroup Inc. (C) kept a “Neutral” rating on SPG and raised the price target to $237, implying a potential upside of 5.2% from current levels.
The mean price target of $233.59 represents a 3.7% premium to SPG’s current price levels. The Street-high price target of $275 suggests an upside potential of 22.1%.
On the date of publication, Neha Panjwani did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.