


EN
Anthropic Stock Record IPO Has The Bull Case Changed?
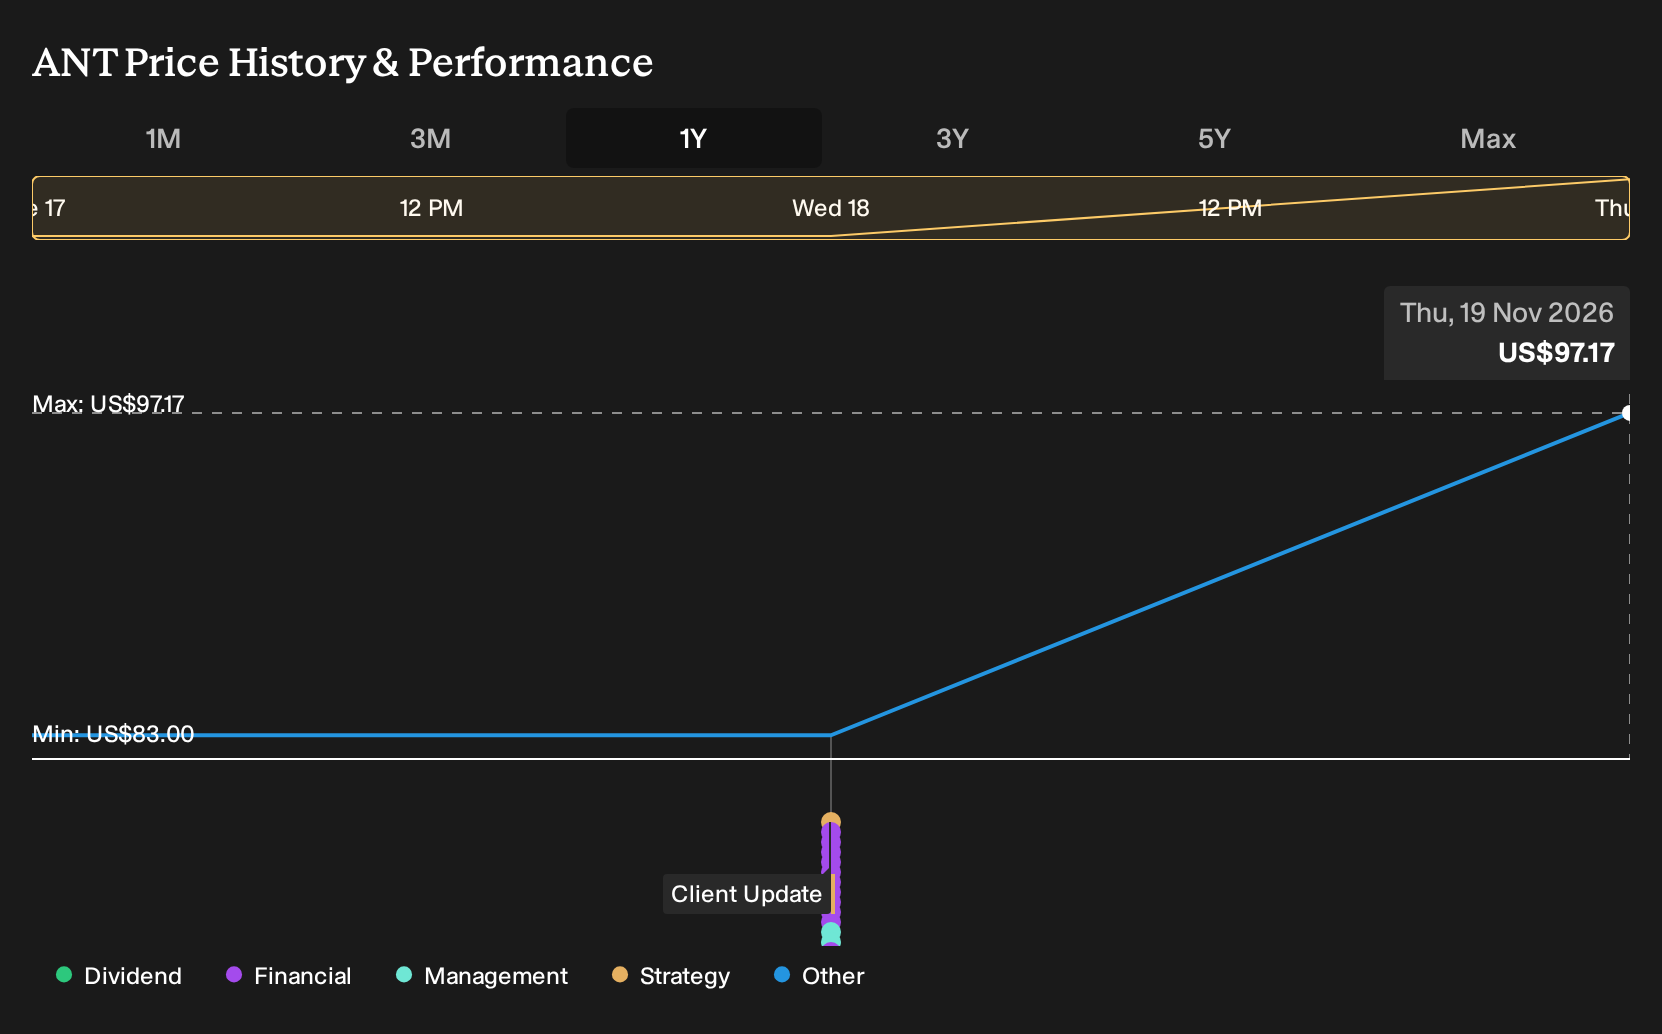
- Anthropic PBC completed a record Nasdaq IPO, raising about US$81.3b through Class A common stock and briefly lifting its valuation near US$1.5t.
- The flotation coincided with sizeable shelf registrations and a large prior private placement. This highlighted how heavily Anthropic is leaning on equity to fund compute hungry AI operations.
- We will now look at how this record Anthropic IPO, and its equity heavy funding mix, reshapes the earlier investment narrative.
Scan how Anthropic’s record IPO fits into the broader AI trade and spot other potential breakouts across the sector with a curated list of 53 AI infrastructure stocks.
Anthropic PBC Investment Narrative Recap
To own Anthropic PBC, a shareholder needs to believe Claude can keep converting heavy AI usage into much higher spend per client, as Michael_Jay, an investor in the Simply Wall St Community, argues with Anthropic’s consumption based model and very high revenue retention. The key near term swing factor is whether that usage continues to justify Anthropic’s very large compute commitments while the business remains loss making.
The biggest risk in the short run sits in that mismatch. Anthropic reported sizeable net losses alongside large infrastructure obligations, so any slowdown in Claude consumption or pricing power could leave the business with fixed commitments and pressure on cash. The recent record IPO and equity heavy funding mix help fund those commitments but do not remove that execution risk.
The clearest news item that ties back to this funding question is the pair of huge shelf registrations for Class A stock on 19 November 2026, totaling more than US$460b. Those filings give Anthropic the flexibility to issue new equity or register employee holdings, which matters for a company that is still unprofitable and carries large AI infrastructure commitments.
For you as a prospective shareholder, those shelves sit right beside the IPO and private placement as part of one funding story. They signal that management is leaning on stock issuance to support Anthropic’s Claude compute needs and ecosystem investments. That can support product rollout and customer wins like those highlighted by partners, but it also introduces ongoing dilution risk that sits alongside the core operating catalyst of sustaining heavy Claude usage.
In Michael_Jay’s view, Anthropic reaches a fair value of US$80.00 per share if revenue expands by 36.3% a year and the business eventually settles at a 12.1% profit margin, which together support a large earnings base on today’s equity footprint.
Uncover why Anthropic PBC's fair value indicates an 18% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
Six fair value estimates from the Simply Wall St Community span Anthropic from about US$7.62 to roughly US$118.93 per share, a huge spread that flags how far opinions can stretch. You now have a record IPO, a shifting underwriter line up, and massive shelf capacity to weigh. Use that mix to test several contrasting views.
Explore 5 other Anthropic PBC fair value estimates, including one that suggests as much as 22% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Anthropic PBC research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Anthropic PBC. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Anthropic PBC's overall financial health at a glance.
Looking for more investment ideas beyond Anthropic PBC?
Anthropic PBC may be front of mind after this IPO, but you can widen your watchlist by scanning other companies with different return and risk profiles using the Simply Wall St Screener.
- If you want to focus on quality at a reasonable entry point, start with a curated set of 36 high quality undervalued stocks that combine fundamentals with a potentially attractive price.
- For investors who care most about balance sheet strength and resilience, filter for a list of solid balance sheet and fundamentals (25 results) that can help you stress test your portfolio against tougher conditions.
- To surface less crowded ideas that still rest on financial substance, review a 19 high quality undiscovered gems that highlight companies with solid metrics but lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com