


EN
Aradel Holdings (NGSE:ARADEL) Stock Looks Undervalued Against Its Earnings
Aradel Holdings has delivered a strong 71.6% return over the past year, which naturally raises a sharper question for investors who care about valuation. With that kind of move on the table, the issue now is whether the current share price lines up with what the business is earning.
- The 71.6% gain over 12 months puts recent buyers in a very different position to those who owned Aradel Holdings a year ago. The key issue is whether earnings now support this higher entry point.
- The way Aradel converts its operations into profit, and how consistently those earnings flow through to the bottom line, can shape what investors are really paying for at today's multiple.
- Your read on Aradel Holdings is one view; the desks covering it have another. See what analysts think Aradel Holdings's shares could be worth.
For investors, the debate is whether Aradel Holdings' current market price is justified by its earnings compared with the industry average.
If you want another starting point for research alongside Aradel Holdings, run the same earnings test across a curated list of 210 high quality undervalued stocks.
Is Aradel Holdings a Bargain on Earnings?
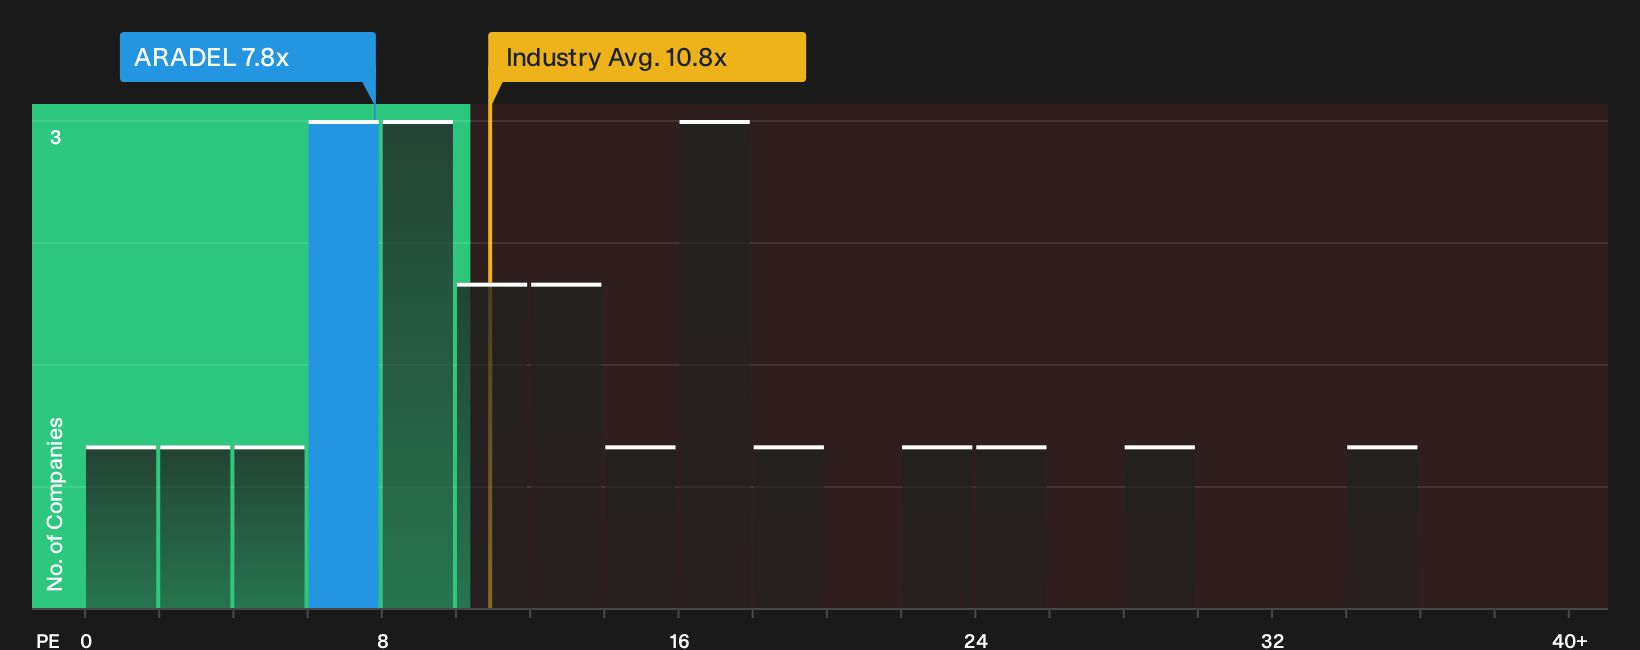
The P/E ratio works well for Aradel Holdings because earnings are a key reference point for this kind of business. On that yardstick, the shares trade on roughly 7.8x earnings, which is lower than the Oil and Gas industry average of about 10.8x. Compared with a broader peer group on roughly 39.0x, the stock changes hands at a much lower earnings multiple.
For you as a shareholder, that gap suggests the market is pricing Aradel Holdings at a discount relative to sector norms on this measure. The key judgement is whether the quality, durability and risk profile of its profits justify that lower P/E, or whether the pricing is too cautious for what the company is currently earning. Explore the numbers behind Aradel Holdings's P/E valuation.
The Aradel Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle leaves off for Aradel Holdings by explaining what kind of future earnings path, margins and reinvestment outcomes would need to hold for the stock to be worth materially more or less than today's price on the Community page. Each scenario links a fair value estimate to a clear story about Aradel Holdings' potential catalysts and key risks, so you can track over time which version appears to be unfolding.
A clear, number-driven narrative on Aradel Holdings gives you a single place to spell out what you expect for its growth, margins and execution, then measure those assumptions against the actual results as they land.
Instead of reacting to headlines, you can track how the business lines up with the original thesis over time and adjust your view as new data either confirms or challenges that roadmap.
Share your own Narrative for Aradel Holdings and set out the assumptions behind your valuation.
Aradel Holdings' price tag is only one piece of the decision
Before you lean too much on the earnings multiple, it helps to know that Simply Wall St's checks have picked up specific risk factors that deserve a closer look beside the valuation story. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com