


EN
Australian Bank Stocks That Could Hold Up Better If Inflation Stays Sticky
Inflation is back in the spotlight for Australian banks, with fuel costs, power bills and a higher CPI print colliding with a softer jobs market to create a tricky backdrop for rate expectations and earnings. That mix can reshuffle which financial stocks look more resilient and which appear exposed, so sitting on the sidelines risks missing key shifts. This article walks through three Australian bank stocks from our screener that appear better placed in this tug of war between sticky prices, policy uncertainty and slower hiring, and explains what the latest data could mean for their risk and return profiles.
The three stocks covered below are just a sample set, and the full screen surfaced 7 more Australian bank and lender companies with similarly interesting quality and income stories that are not unpacked here. If you want to go straight to the source, use the Australian Bank Stocks screener to identify, compare, and analyze the bank stocks that best fit your own risk and dividend preferences.
ANZ Group Holdings (ASX:ANZ)
ANZ Group Holdings sits near the centre of the Australian Bank Stocks theme, with its broad retail, business and institutional lending book giving it heavy exposure to how longer lasting interest rates shape margins, capital strength and income for shareholders, according to Jamesiskindacool, a Simply Wall St Community investor who wrote a detailed Narrative on the stock.
"Importantly, this assessment is based primarily on the company’s existing earnings, capital position and dividend payments and does not assign significant value to further Suncorp Bank integration benefits, additional cost reductions, loan growth or future changes in net interest margins."
What happens if that single uncounted earnings lever moves even modestly in ANZ Group Holdings’ favour could matter a lot for income-focused investors.
ANZ Group Holdings is a big four bank offering everyday banking, loans, wealth and institutional services across Australia, New Zealand and offshore markets, with A$6.3b from Institutional, A$5.4b from Australia Retail and A$4.3b from Business & Private Bank anchoring revenue, and a market value around A$117.5b.
That unpriced earnings gear is only the start, and the full narrative for ANZ Group Holdings explains how ANZ Group Holdings’ income story could shift if those levers start moving.

Westpac Banking (ASX:WBC)
Westpac Banking is a cornerstone of the Australian Bank Stocks theme, with its large retail deposit pool and lending franchise tying earnings closely to domestic interest rates, according to the analyst consensus Narrative on Simply Wall St.
Westpac Banking runs consumer, business and institutional banking across Australia and New Zealand, with A$8.1b from Consumer, A$6.2b from Business & Wealth and A$3.9b from Institutional, plus A$2.6b from Westpac New Zealand and A$1.1b from Group Businesses, and a market value around A$125.5b.
"Continuation of the multi year UNITE systems simplification program, with an unchanged scope, timeline and around A$3.5b budget, along with green progress on most initiatives, is expected to support lower structural costs and a smaller cost to income gap, which would influence earnings resilience."
What happens if one unresolved pressure in its domestic interest margins shifts even slightly will be crucial for how that resilience shows up.
If that margin pressure eases faster than expected, the full narrative for Westpac Banking shows how Westpac Banking’s earnings mix, cost base and shareholder returns story could be quietly shifting.

National Australia Bank (ASX:NAB)
National Australia Bank plays a central role in the Australian Bank Stocks theme, tying higher cash rate settings directly to net interest margins across its broad home loan, SME and institutional book. The analyst consensus Narrative on Simply Wall St argues the next phase turns on how its digital and business banking push translates into earnings strength.
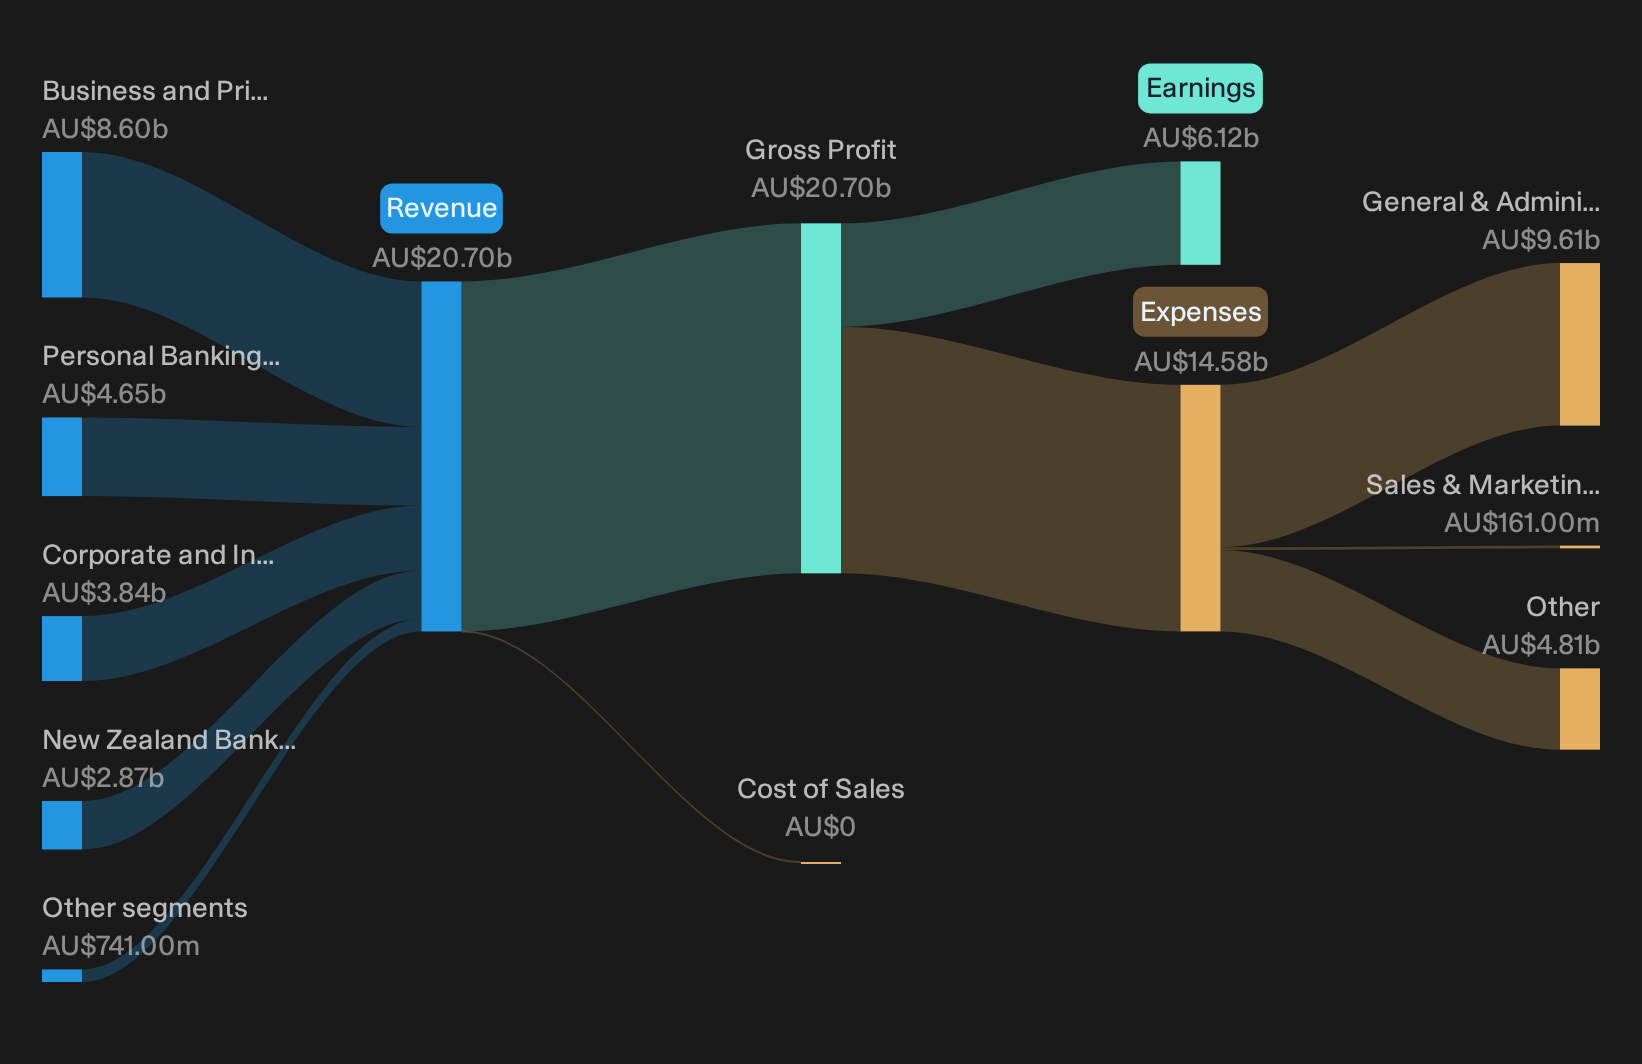
National Australia Bank runs a wide banking and financial services network across Australia, New Zealand and offshore markets, generating A$8.6b from Business and Private Banking, A$4.6b from Personal Banking and A$3.8b from Corporate and Institutional Banking, with a market value around A$114.2b.
"Accelerating shift toward digital payments and banking is driving substantial investment in National Australia Bank’s real-time payments engine and cloud-based transaction switch, including migration of all payments to the new platform and planned migration of all card transactions by FY 2027. This could support fee income and payments-related revenue as volumes move across these systems."
What happens if one unseen pressure in its cost base moves just as those higher rate linked earnings levers start to bite will be crucial.
If that cost shift is what interests you, the full narrative for National Australia Bank explains how those moving parts may be masking upside and risk in plain sight.
Seeking Alternatives Before Everyone Else?
Fresh opportunities move fast. Some stock themes gather momentum quietly, then fly once the crowd finally catches on. Scan these curated ideas while it matters and get in early.
- Spot fast-moving income ideas and stress test your watchlist against a 3 dividend fortresses so you are not caught chasing yields after they have already popped.
- Track where real earnings power meets AI momentum by reviewing the 43 profitable AI stocks that aren't just burning cash before those stories stop looking under the radar for now.
- Position ahead of the grid upgrade rush and scan the 42 power grid technology and infrastructure stocks while these infrastructure plays are still priced like yesterday’s utilities and not like tomorrow’s backbone.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com