


EN
The Worst Might Be Over for Somnigroup as Credit Metrics Improve
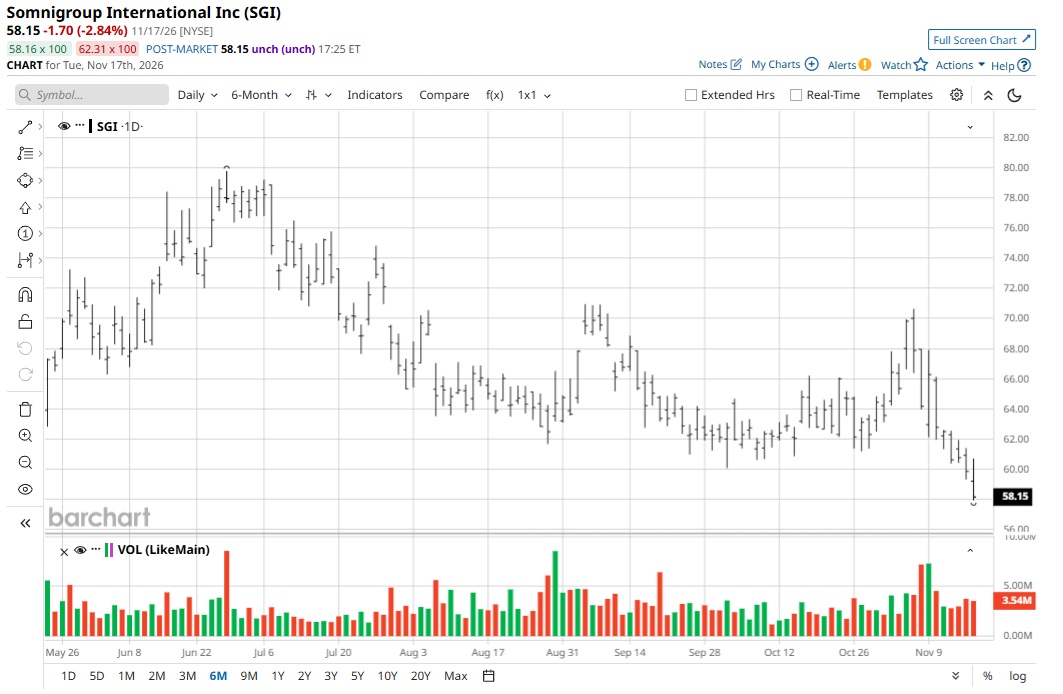
With weak industry demand impacting sales, Somnigroup International (SGI) stock has corrected by 30% in the last 52 weeks. To put things into perspective, the company’s third-quarter growth was entirely driven by acquisitions. Further, management has continued to lower its EPS guidance. These factors have translated into valuation compression.
However, as SGI stock remains depressed, there seems to be some buying interest at lower levels. Stanley Druckenmiller's Duquesne Family Office recently took a new stake in Somnigroup, adding 993,600 shares valued at $61.7 million.
Amidst the weakness in sales, it’s important to note that the company’s credit metrics have improved meaningfully. In September 2025, the company reported a net debt-to-adjusted EBITDA ratio of 3.28 times. However, leverage declined to 2.69 times as of Q3 fiscal 2026. At the same time, the company ended Q3 with a total liquidity buffer of $1.1 billion.
Another point to note is that the company’s operating cash flow for the first nine months of fiscal 2026 was $831.9 million. This implies an annualized OCF potential of $1.1 billion. With healthy cash flows, credit metrics will likely continue to improve. Therefore, the correction seems like an attractive buying opportunity.
About Somnigroup Stock
Headquartered in Dallas, Texas, Somnigroup is the world's largest bedding company. The company designs, manufactures, distributes, and retails bedding products both in the United States as well as across some 100 other countries.
The company’s portfolio includes brands like Tempur-Pedic and Sealy. As of December 2025, Somnigroup's combined global footprint included more than 2,800 retail stores, 30 e-commerce platforms, and more than 70 manufacturing facilities.
For Q3, Somnigroup reported sales growth of 11% on a year-over-year (YOY) basis to $2.4 billion. For the same period, operating income declined by almost 6% to $297.4 million. The decline in operating income was primarily due to costs incurred during the quarter related to the Leggett & Platt acquisition.
With margin contraction being a concern, SGI stock has declined by 3% in the last six months. However, at a forward price-to-earnings (P/E) ratio of 20 times, the stock seems attractive.
Growth Initiatives Likely to Deliver Results
Between 2020 and 2025, Somnigroup has invested $1 billion in plants and processes to drive operations. During the same period, the company has also invested $5.6 billion in M&A activities. This phase of investment is likely to deliver returns in the coming years.
To put things into perspective, Somnigroup guided for 2026 adjusted EPS of $2.90 at the midpoint. Further, the company expects 2028 EPS to swell to $5.15. If this holds true, SGI stock is currently trading at 11.5 times fiscal 2028 EPS. Its forward valuations therefore look attractive.
It’s also worth noting that, in 2009, mattress units produced in the United States came to 18.1 million. In comparison, mattress production in 2025 was 15.9 million units. With mattresses being a replacement-cycle purchase, the industry could be poised for a reversal. Additionally, Somnigroup has a strong presence in both Europe and the Asia-Pacific region, implying a large addressable market.
The Leggett & Platt acquisition has also helped the company in enhancing its supply chain and “accelerating product development.” With new launches, growth is likely to be supported. At the same time, merger synergies will translate into potential margin expansion in the coming years. Accordingly, the worst might be over for Somnigroup, with current valuations making it an attractive bet.
What Do Analysts Say About Somnigroup Stock?
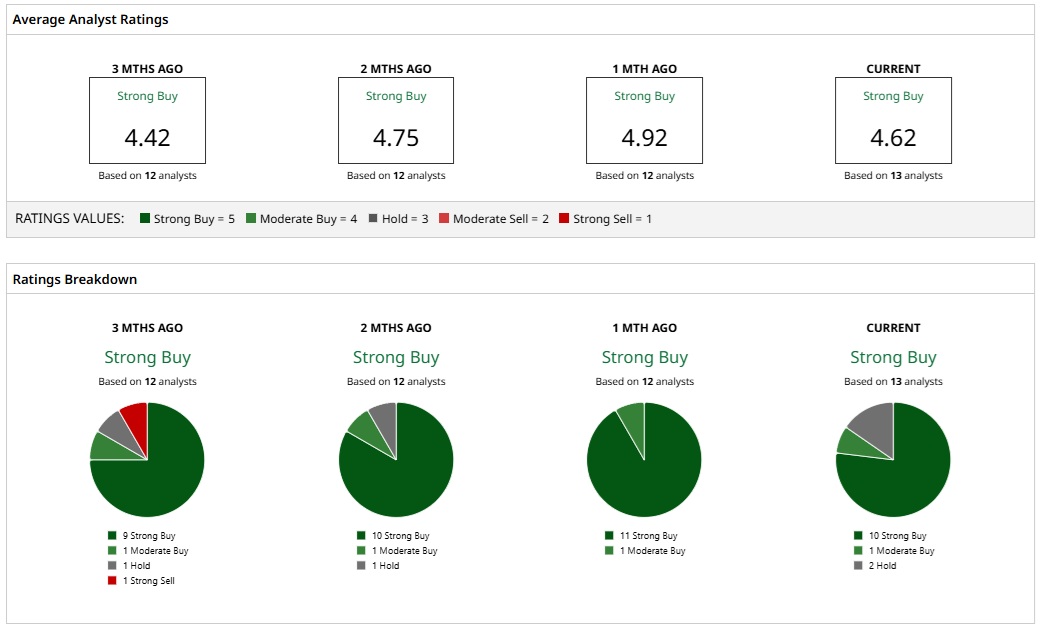
Based on 13 analysts with coverage, SGI stock has a consensus “Strong Buy” rating on Wall Street. While 10 analysts have a “Strong Buy” rating for the stock, one has a “Moderate Buy,” and two have a “Hold” rating.
The mean price target of $85.42 represents potential upside of 44% from current levels. Further, the most bullish price target of $100 suggests that SGI stock could climb as much as 68% from here.
On the date of publication, Faisal Humayun Khan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.