


EN
Freehold Royalties (TSX:FRU) Stock Looks Priced Below Fair Value
Freehold Royalties has delivered a 5 year share price return that would have caught the eye of many income focused investors, which raises a simple question for anyone looking at the stock today. Is the current price still in step with what the business earns.
- The stock has doubled over 5 years, which increases the importance of whether today’s valuation can be supported by its earnings power.
- Recent expansion into Alberta’s Duvernay play and higher funds from operations can influence how durable Freehold Royalties’ future earnings and cash generation may be.
- The analysts covering Freehold Royalties have run their own numbers. See what analysts think Freehold Royalties's shares could be worth.
The issue now is whether the current share price is justified by Freehold Royalties’ earnings when judged against the Fair Ratio benchmark.
If you want a quick comparison point while you assess Freehold Royalties on its earnings, it can help to line it up against 2 high quality undervalued stocks.
Does Freehold Royalties Look Undervalued on Earnings?
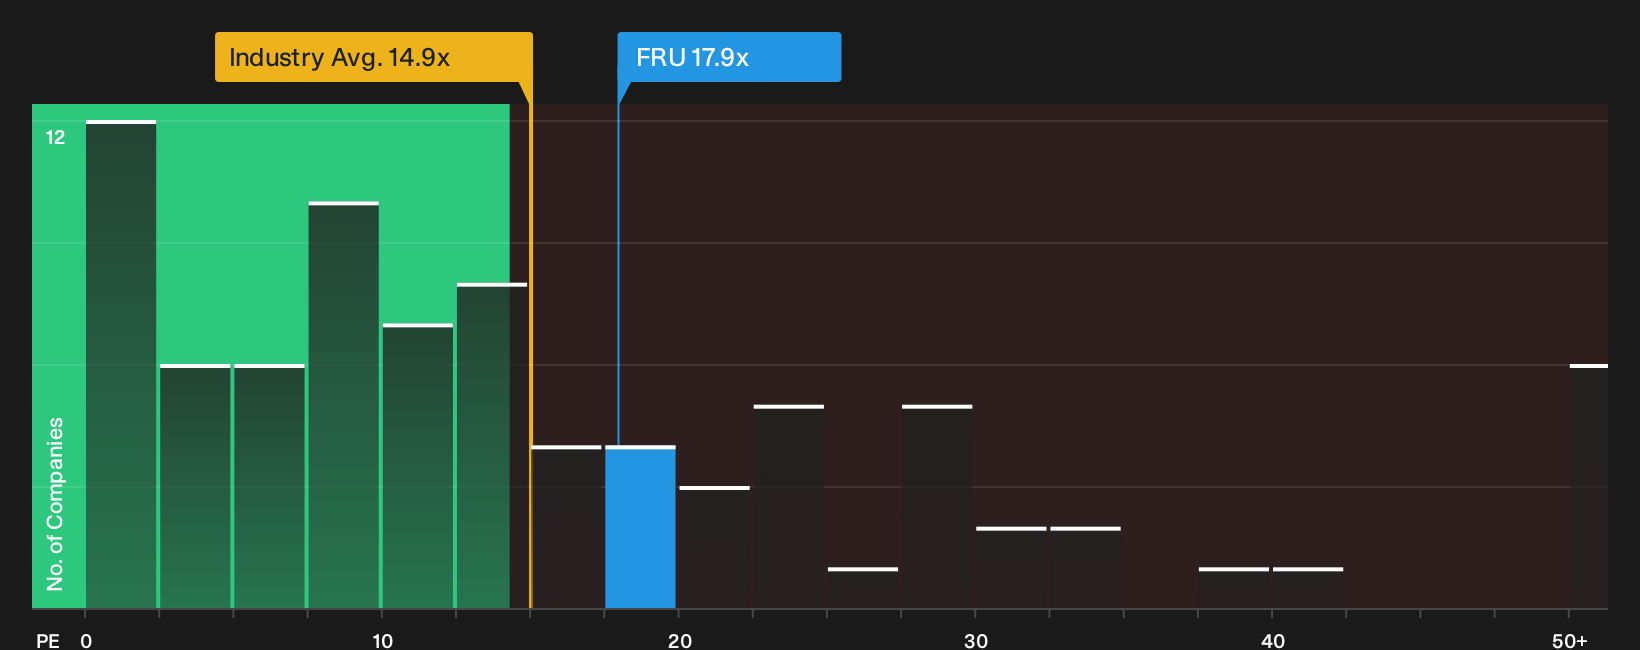
The P/E ratio fits Freehold Royalties because earnings power and capital intensity matter a lot for a royalty model. On this yardstick, the stock trades on about 17.9x earnings, which is higher than the Oil and Gas sector average of roughly 14.9x. That puts the shares on a richer multiple than the broader industry even though the business does not carry operating costs in the same way as a producer.
Because the Fair Ratio benchmark blends factors such as growth profile, profitability, size and risk, Freehold Royalties’ current P/E screens below where that model would place it. As a result, the shares come through as undervalued on this framework. The multiple also sits modestly below the peer group average of about 20.0x, which keeps the current pricing from looking stretched against closer comparables. Despite strong Q3 2026 numbers and fresh attention around the Duvernay expansion, the market P/E still leaves room for investors to argue that the share price does not fully reflect the earnings implied by that benchmark. Explore the numbers behind Freehold Royalties's P/E valuation.
The Freehold Royalties Narrative: What Would Justify Today's Price?
Freehold Royalties' current P/E creates a valuation puzzle, and Simply Wall St Narratives pick up from that point by spelling out what would need to happen to growth, margins and earnings for the shares to be worth materially more or less than today’s price on the Community page. Rather than rely on a single multiple or model output, each narrative lays out the assumptions behind its fair value so you can compare those expectations with the actual results as they come through.
One of the top community narratives on Freehold Royalties: 6% undervalued
According to Composite_Research, a Simply Wall St Community investor who wrote the Narrative, Freehold Royalties looks interesting for its royalty economics and portfolio mix.
"Freehold Royalties' business model differs from traditional Exploration and Production companies with a fundamental structural advantage, the company does not bear any of the costs of drilling, completion, operation, or environmental rehabilitation on its land..."
Discover why this Narrative puts Freehold Royalties at 6% undervalued.
Freehold Royalties' price is only one decision point
Before you settle on any view of Freehold Royalties, it pays to look at who is steering the business and how their pay packets line up with your interests. See who runs Freehold Royalties and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com