


EN
Matthews’s Q3 CY2026 sales top estimates
Diversified solutions provider Matthews International (NASDAQ:MATW) reported calendar Q3 2026 [fiscal Q4 2026] results topping the market’s revenue expectations, but revenue fell by 19.5% year on year to $256.7 million. Its non-GAAP profit of $0.39 per share was 46.2% above analysts’ consensus estimates.
For more on Matthews, read our free full research report.
Matthews Q3 CY2026 highlights:
- Revenue $256.7 million vs S&P analysts’ consensus of $252.7 million (19.5% year-on-year decline, 1.6% beat)
- Adjusted EPS $0.39 vs S&P analysts’ consensus of $0.27 (46.2% beat)
- Adjusted EBITDA $46.53 million vs analysts’ consensus estimates of $44.52 million (18.1% margin, 4.5% beat)
- Operating margin -3.3%, down from 2.1% in the same quarter last year
- Free cash flow margin 2.6%, up from 0.3% in the same quarter last year
- Market capitalization $609.9 million
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can report a good quarter or two, but many enduring ones grow for years. Matthews struggled to consistently generate demand over the last five years as its revenue dropped at an 8.9% annual rate, falling short of our standards and signaling poor business quality.
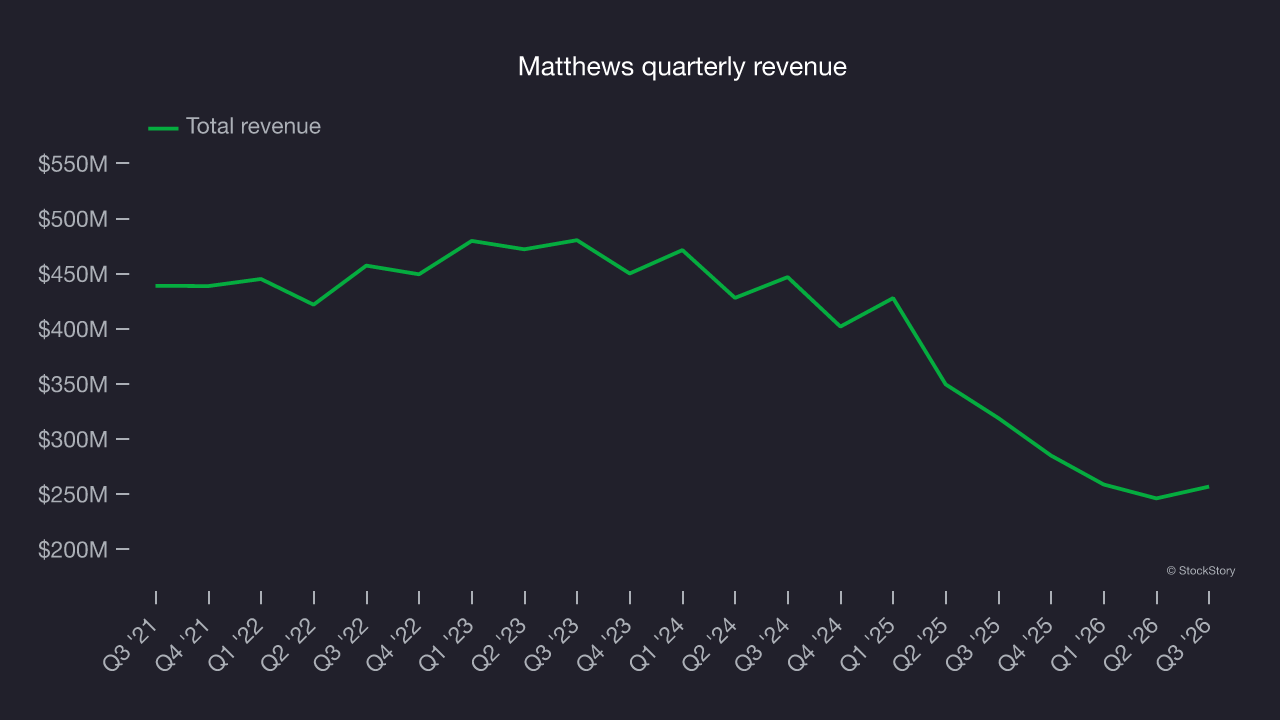
Long-term growth is the most important, but within consumer discretionary, product cycles are short and revenue can be hit-driven due to rapidly changing trends and consumer preferences. Matthews’s recent performance shows its demand remained suppressed as its revenue has declined by 23.7% annually over the last two years. 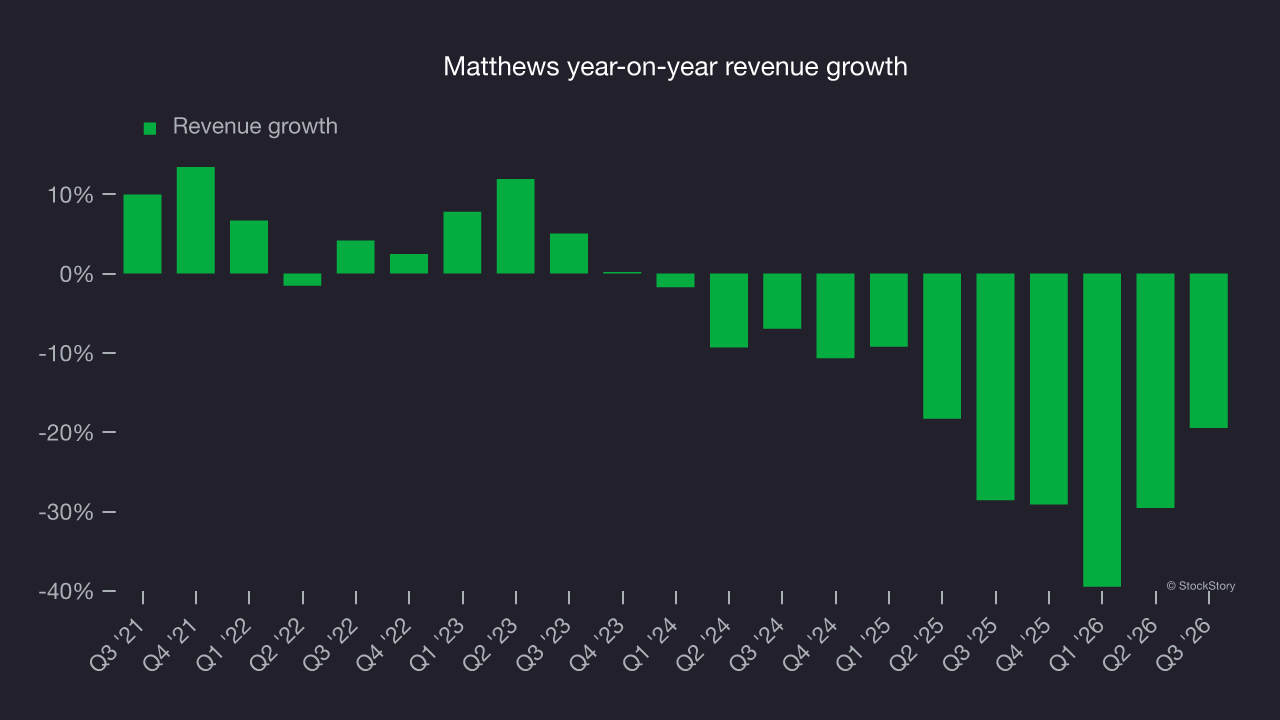
This quarter, Matthews’s revenue fell by 19.5% year on year to $256.7 million but beat Wall Street’s consensus estimates by 1.6%.
Looking ahead, sell-side analysts expect revenue to decline by 1.9% over the next 12 months, according to S&P. This projection is better than its two-year trend, but the outlook remains challenging given the company’s demand difficulties.
Operating margin
Matthews’s operating margin has shrunk over the last 12 months, and it ended up breaking even over the last two years. The company’s performance was weak, showing its operating expenses were rising and it couldn’t pass those costs on to its customers.
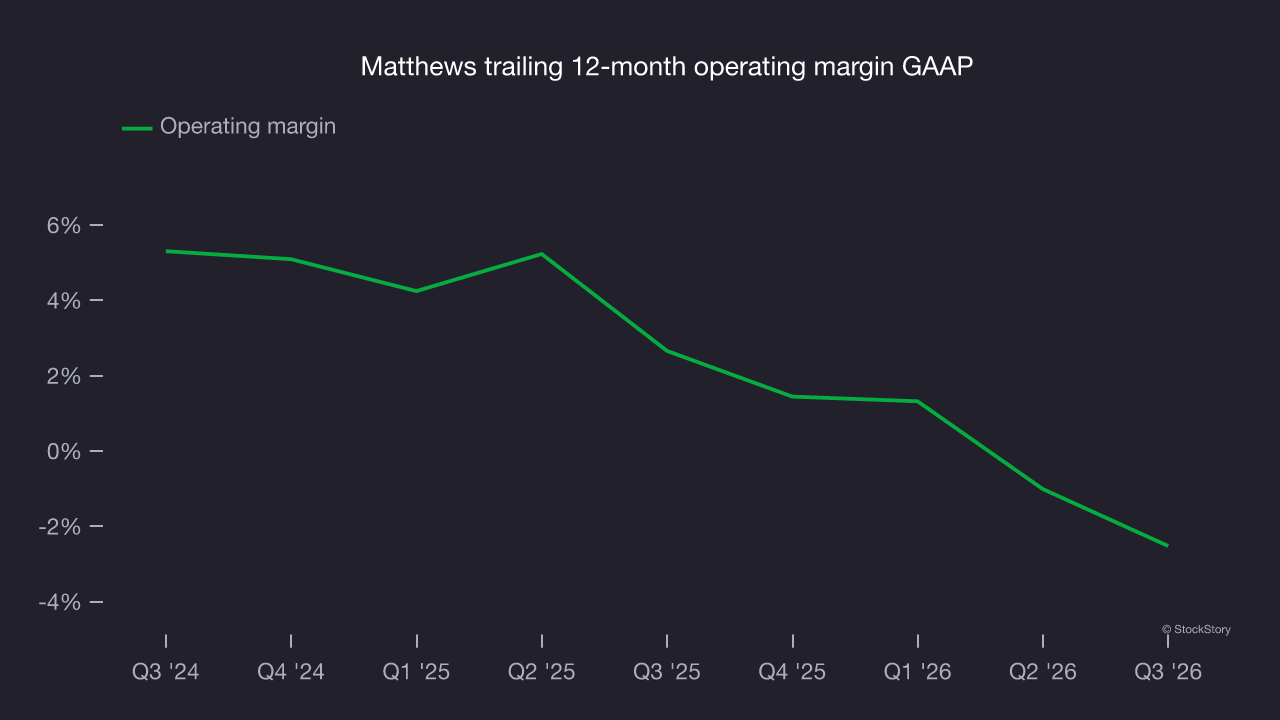
In Q3, Matthews generated an operating profit margin of negative 3.3%, down 5.4 percentage points year on year. This contraction shows it was less efficient because its expenses increased relative to its revenue.
Earnings per share
We track the long-term change in earnings per share, or EPS, for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Matthews’s EPS declined by 28.1% annually over the last five years, more than its revenue. This indicates the company struggled because its fixed cost base made it difficult to adjust to shrinking demand.
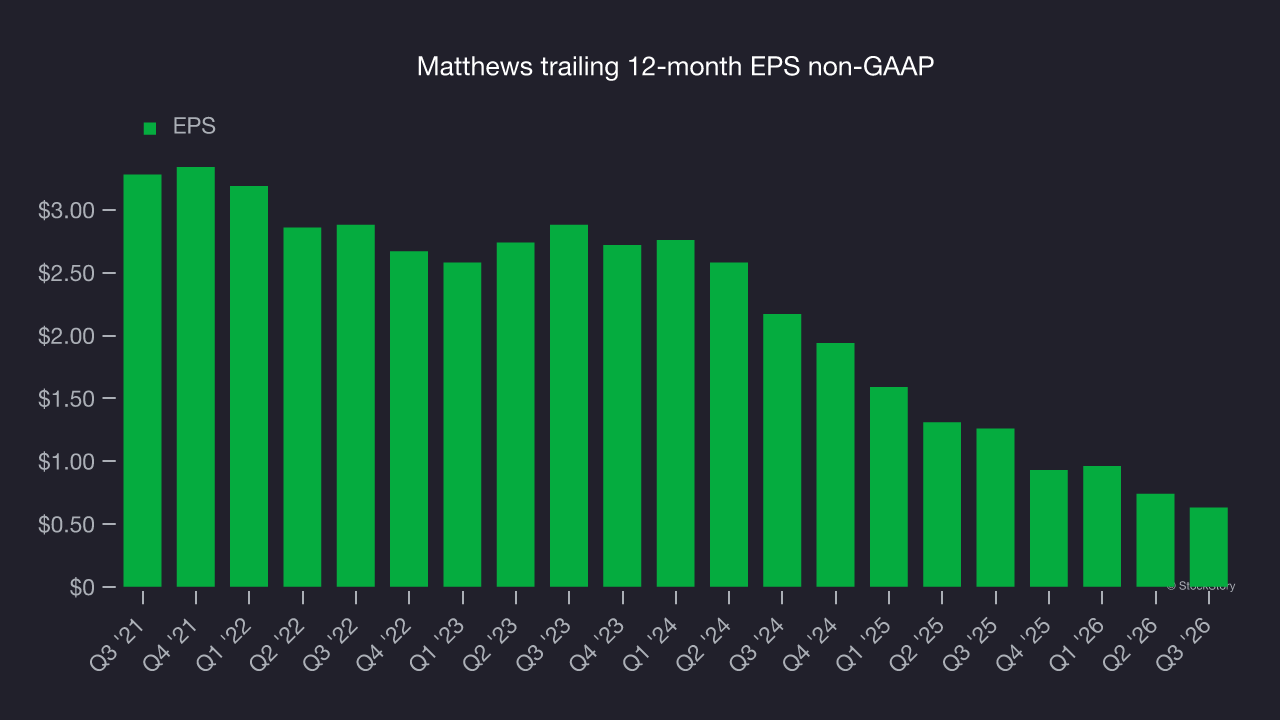
In Q3, Matthews reported adjusted EPS of $0.39, down from $0.50 in the same quarter last year. Despite falling year on year, EPS came in well above analysts’ consensus estimates. Over the next 12 months, Wall Street expects Matthews’s full-year EPS to grow 29.4% from $0.63 to $0.82, according to S&P.
Key takeaways from Matthews’s Q3 results
Matthews delivered a solid Q3, topping analysts’ consensus estimates for both EPS and revenue. Those beats were the quarter’s key positives. Shares remained flat at $19.42 immediately after the results.
For Matthews, the latest quarter is only one piece of the longer-term business quality picture. Quality, combined with valuation, can help determine whether the stock is a buy. For more, read our full research report here (it’s free).