


EN
NVDA Stock Alert: What to Know as Moody's Cuts Nvidia's Outlook Rating
Nvidia's (NVDA) credit outlook was lowered to stable from positive by Moody's on Thursday, citing the abrupt departure of long-time CEO Jensen Huang and the absence of a formal succession plan.
Although Nvidia retains its Aa1 senior unsecured debt rating, the outlook change puts a potential “credit update” further out of reach just as it begins shipping its next-gen AI systems under interim CEO Colette Kress.
At the time of writing, Nvidia stock is down nearly 40% from its year-to-date high set in early October.
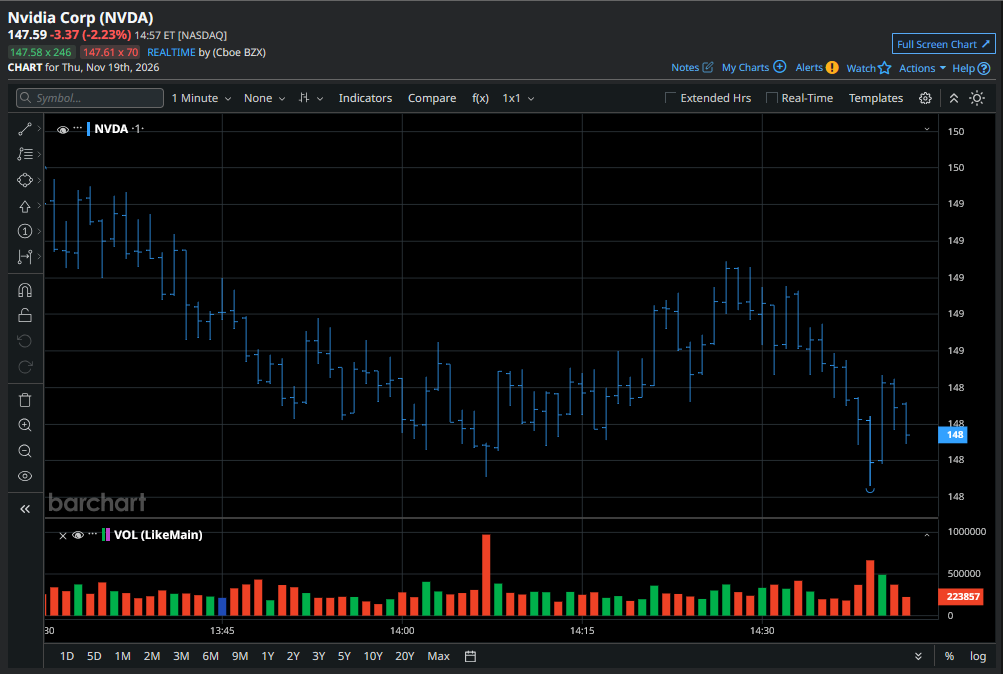
Why Moody’s Cut Nvidia's Outlook Rating
Moody’s said an upgrade is now unlikely over the next 12 to 18 months. Its concern is how Huang’s departure could affect Nvidia’s strategy, financial policies, and relationships across the AI industry.
Those relationships matter because cloud providers deploying Nvidia systems help determine how quickly a new chip platform translates into sales.
Moody’s also flagged the potential for government scrutiny to divert management’s attention and for tighter rules on remote access to cloud computing to weigh on sales.
That said, Nvidia retained its Prime-1 short-term commercial paper rating alongside its Aa1 debt rating, reflecting a financial position Moody’s still views as exceptionally strong.
What NVDA Investors Should Watch Next
Nvidia saw its third-quarter revenue more than double from a year earlier to nearly $116 billion, and it expects that metric to hit $130 billion in the current quarter, which includes an extra week.
Even with that sales growth, the company expects gross margin to contract sequentially from 74.8% to as low as 71% in the final quarter of 2026.
That gives shareholders a concrete measure to watch during the CEO search.
As Nvidia ramps up shipments of its Vera Rubin systems, the next earnings release will show how much of the additional revenue flows through to gross profit.
Sustained margin pressure would temper the benefit of higher sales, potentially making it difficult for NVDA shares to meaningfully recover.
Wall Street Remains Bullish on Nvidia
Investors should note, however, that Wall Street hasn’t thrown in the towel on Nvidia shares.
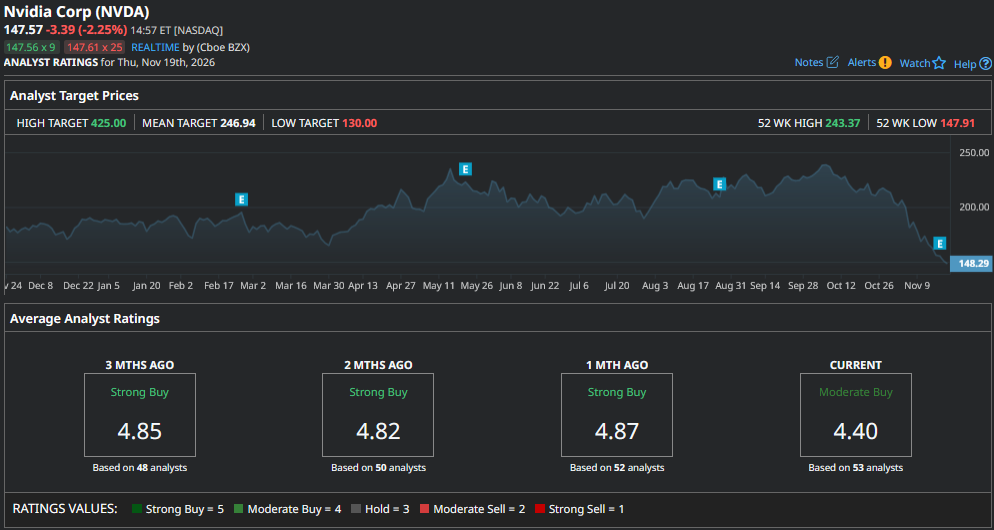
The consensus rating on the AI darling remains Moderate Buy, with a mean price objective of about $247, signaling potential upside of about 40% from here.
On the date of publication, Wajeeh Khan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.