


EN
Bank Branch Costs Hinge More on Market Than Management, JLL Finds
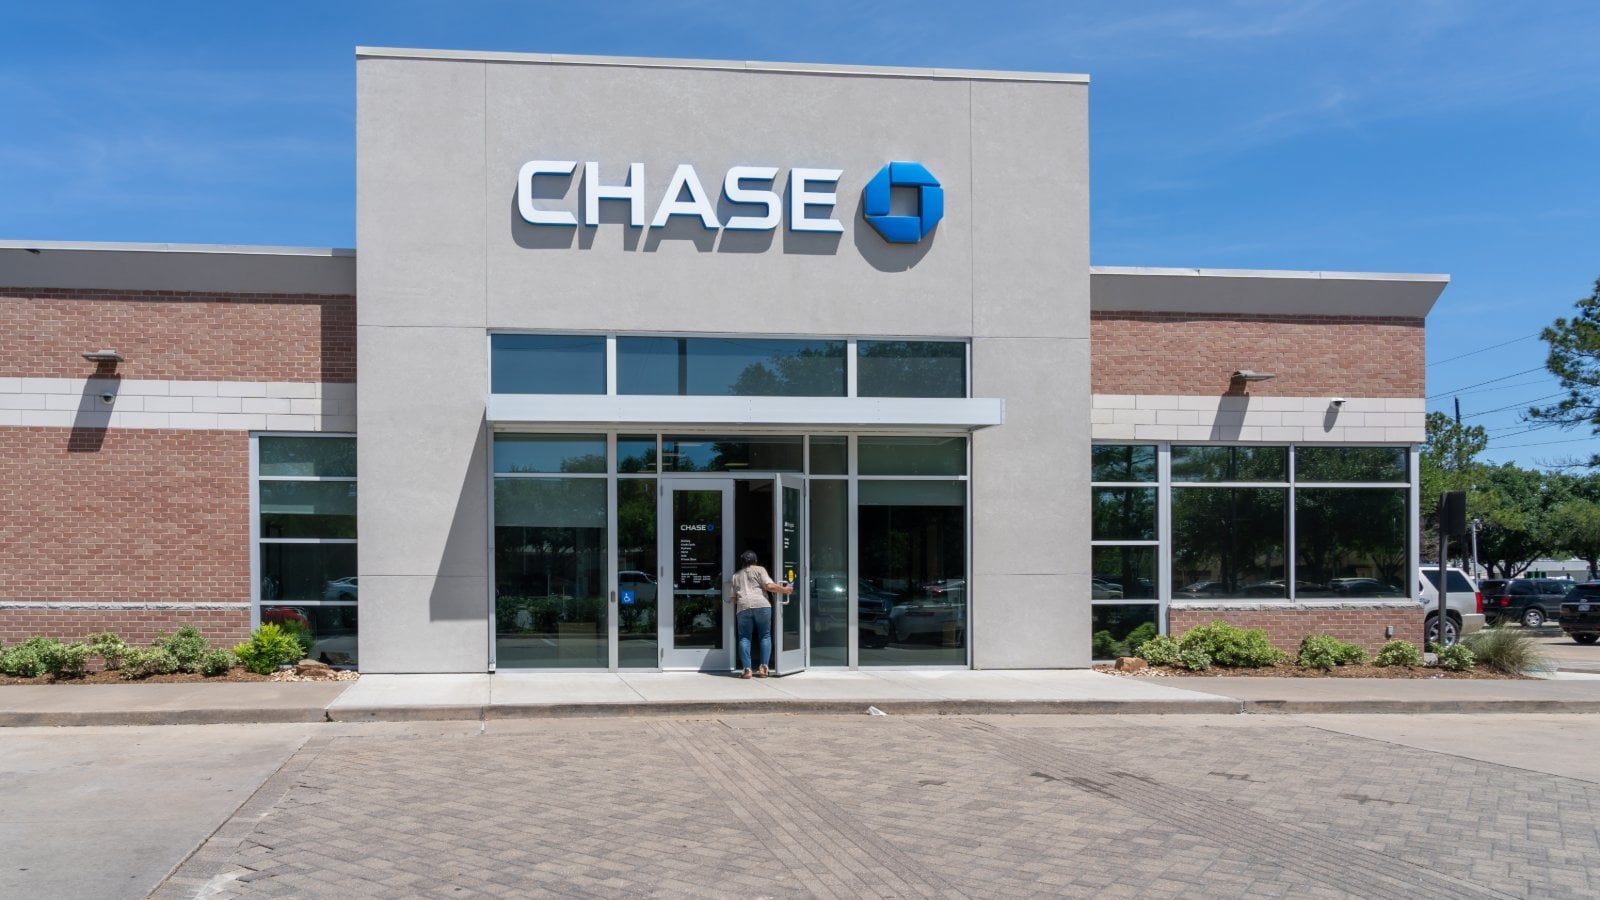
In early 2026, a Wall Street Journal article said that bank branches were closing at a rapid rate, due to the continued rise of digital banking. Between 2019 and 2024, over 6,000 branches nationwide closed.
However, U.S. banks opened more branches in the first half of 2026 than they closed, “reflecting the first sustained expansion since the financial crisis and a historic shift after more than a decade of post-crisis consolidation,” according to JLL’s just-released “The Cost of Running a Retail Bank Branch Network” report.
“Digital banking has fundamentally changed how customers transact, but it hasn’t eliminated the need for personal interaction,” Erin Haglund, managing director, financial services at JLL, told Connect CRE.
“In many ways, it has made the purpose of the physical branch more important and more specialized.”
While this might be good news for customers who prefer their banking to be up close and personal rather than online, it can also mean higher operating costs for the banks in question.
Location Determines Costs
Many of the expenses boil down to a branch’s locale.
“What stood out most was just how much of a branch’s operating cost is determined by the market itself, rather than the decisions a bank makes about managing its facilities,” Haglund said.
The JLL report explained that across 12 U.S. markets, facilities operating cost per square foot is 2.6 times higher at the top than at the bottom. The expenses include repair and maintenance, cleaning, snow clearance and grounds maintenance, while excluding rent, pass-through charges from landlords and capital spending.
Annual costs per square foot by market are:
- New York City: $24.35
- Chicago: $15.18
- New Jersey: $14.94
- Long Island, NY: $14.83
- Houston: $12.76
- Dallas-Fort Worth: $12.24
- Philadelphia: $12.12
- Hartford, CT: $12.10
- Seattle/Puget Sound: $11.40
- Baltimore, MD: $10.50
- Washington, DC metro: $10.36
- Orange County, CA: $9.23
The gap results from wage levels, climate and building format versus portfolio management.
“Banks have historically relied on national benchmarks, standardized contracts, and broad cost-reduction targets to drive efficiency,” Haglund said.
“But our research reinforces that a lower-cost branch isn’t necessarily a better-managed branch, and a higher-cost branch isn’t necessarily inefficient.”
Cost Negotiation: A Non-Starter
The problem faced by branches and banks is that less than one-third of operating budgets can be divided into categories in which vendor negotiation can lead to lower prices. Here’s why:
- Landlords set service charges, which are the largest single line in the budget
- Maintenance costs are the result of vendor availability, rather than contracted rates
For example, negotiating cleaning service costs doesn’t yield much in savings due to rising wages, benefit costs and turnover. The report said that interior cleaning costs 48% more in heavy-union markets than in right-to-work markets, while fire and life safety costs 83% more.
Furthermore, a cleaning line that includes supplies, waste handling, pest control and exterior work averages $4.78 per square foot, compared with $3.19 for general interior cleaning alone. That’s roughly a 50% difference for the same physical work.
Haglund said that focusing on structural market costs rather than operating costs can help. “That allows banks to focus resources where they can actually influence outcomes rather than chasing savings that may not be achievable,” she said.
Another issue is the growing shortage of skilled trades professionals to maintain the physical branches. JLL research reported that approximately 2.1 million skilled trades positions could go unfilled by 2030. Banks compete for such workers with data centers, life sciences and advanced manufacturing, especially in Sun Belt metros where both are expanding.
When equipment fails, and no technician is available, the cost goes beyond the repair bill.
“From a financial perspective, labor shortages can increase emergency service premiums, extend repair timelines and drive higher costs for temporary solutions,” Haglund said.
“Deferred maintenance can also accelerate equipment deterioration and create more significant capital expenditures down the road.”
JLL recommended that banks secure technician capacity and response times before negotiating price. Haglund added that banks should pool maintenance demand across networks, so vendor partners could better plan staffing. Meanwhile, landlords should focus on coordinating building maintenance, replacing equipment before it wears out, and keeping an eye on building systems.
“Ultimately, we need to shift from a reactive maintenance model to one that is more predictive, coordinated and focused on protecting operational continuity,” Haglund said.
Then, There’s the Weather
It’s no secret that climate change is impacting commercial real estate, including physical branches.
Citing Climate Central, the JLL report said that billion-dollar weather disasters have struck the U.S. about every 16 days on average over the past decade, compared with every 82 days in the 1980s. A single regional event (think a hurricane or snowstorm) can impact every branch in a market at once. The bank that relies on a few vendors could find it needs them all at once.
One solution is for bank branch budgets to incorporate expected weather-related variances.
“The objective isn’t necessarily to avoid higher-risk markets; it’s to understand the exposure, evaluate the economics, and design the appropriate level of resilience into the network,” Haglund explained.
Getting Rid of Branches Won’t Work
While getting back to closing branches might look good on paper, the report said it is a poor strategy in practice. Existing a location can be costly, due to remaining lease terms. Then there is the erosion of customer trust.
“Customers increasingly use digital channels for routine transactions, but when they’re making significant financial decisions like buying a first home, starting a business, managing investments, or navigating a major life transition, they often want access to someone they trust,” Haglund noted.
In addition, brick-and-mortar branches support business growth and digital adoption, according to the report.
In one situation, a regional bank reported that digital sales per capital are approximately six times higher in markets with branches. In another case, a national bank added 141 branches over the past year, but its active digital customer base grew by only 5%.
Those branches are becoming increasingly important to younger customers, as well. Haglund explained that younger adults are digitally savvy and prefer convenience and the speed of technology. They also want accessibility, personal advice and authentic experiences.
“That’s especially important as banks compete for the next generation of customers and prepare for the significant transfer of wealth between generations. A well-positioned branch can establish relationships early and create opportunities to deepen them over time,” she added.
Things to Think About
The report doesn’t suggest that branch owners and bank leadership throw up their collective hands and do nothing. Rather, targets should be set by market and lever. Additionally, each cost target should be paired with an availability measure and purchase capacity, rather than rate (such as committed technician numbers and guaranteed response windows).
Haglund suggested that banks need to connect market intelligence, portfolio strategy and facilities operation into an integrated decision-making model. Doing so can enable standardization where it makes sense, while potentially improving time-to-market and cost management.
“If I could recommend one change, it would be to stop managing branch real estate as a series of independent transactions and operating functions and start managing it as an integrated business capability,” she added
“That means connecting the decisions about where to locate, what to build, how to deliver it, and how to operate it throughout its lifecycle.”
Photo: JHVEPhoto/Shutterstock
The post Bank Branch Costs Hinge More on Market Than Management, JLL Finds appeared first on Connect CRE.