


EN
ANT Stock Is Down Nearly 17% from Its Quick Post-IPO Pop. The Dip in Anthropic Doesn’t Mean It’s Cheap.
Anthropic’s Class A shares began trading today on the Nasdaq under the ticker (ANT), marking the public debut of one of the most closely watched AI companies after demand for the offering far outpaced the shares available.
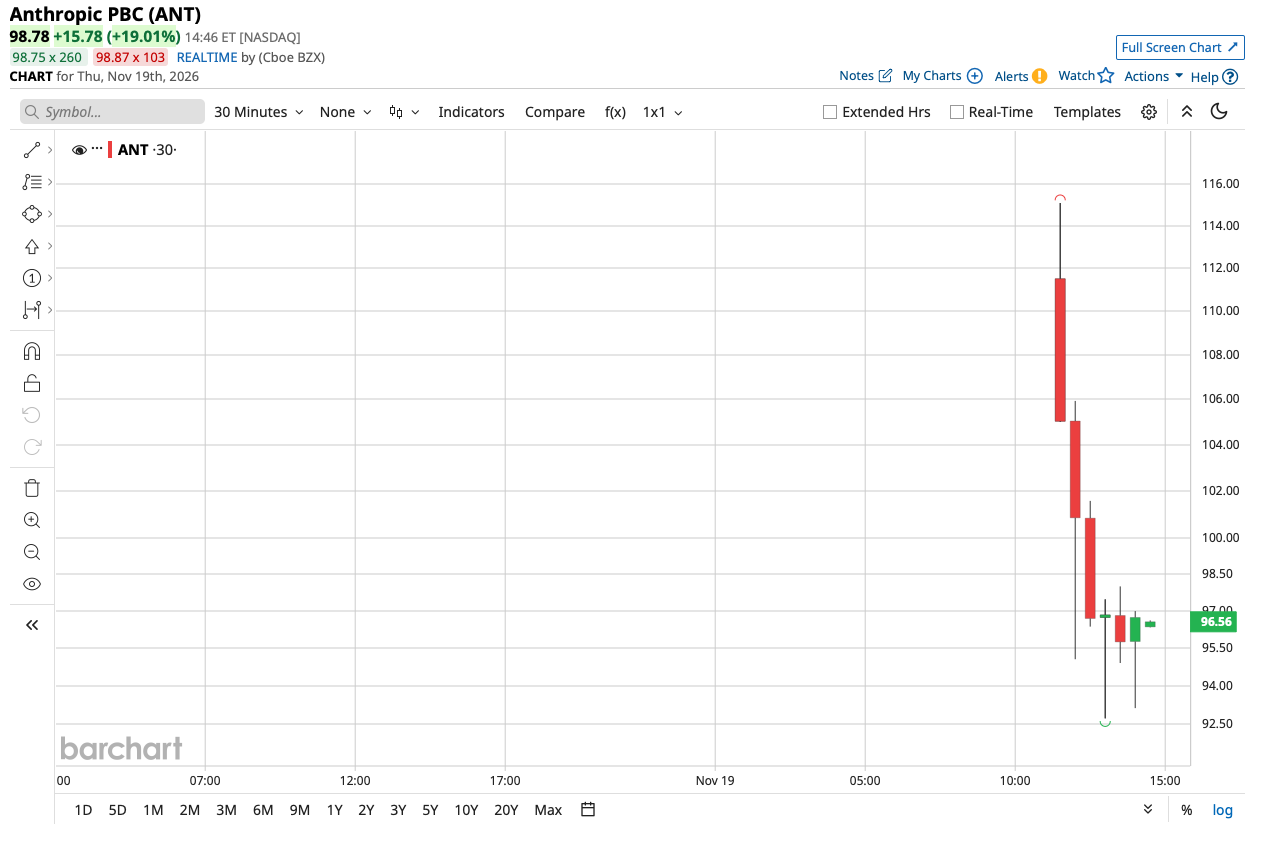
But the opening session quickly showed the risks of chasing that demand. Shares opened at $111.50, about 34% above the $83 offer price, before climbing past $115. But the rally lost some steam, with ANT trading around $96.33, still 12.64% above its IPO price.
That heavy interest arrived as the broader AI trade showed fresh signs of life. Nasdaq futures climbed following upbeat Nvidia (NVDA) earnings that helped revive momentum across related names, even while individual AI-linked stocks continued to swing day to day.
Retail investors now face the first real chance to buy ANT in the open market. With interest this high and the first session still unfolding, what is the smarter way for everyday investors to approach ANT right after the open? Let’s take a closer look.
The Numbers Behind the IPO
Anthropic (ANT) sold more shares at a higher price than it had first planned. The IPO priced 980 million shares at $83 each, up from 825 million shares at a range of $70 to $78. The offering brought in about $81.3 billion, topping the roughly $75 billion SpaceX (SPCX) raised in June. Anthropic’s share was about $79.4 billion before fees and expenses. Existing shareholders received about $2 billion for the shares they sold, before costs.
Anthropic’s third-quarter revenue rose to $16.96 billion from $1.38 billion a year earlier and was up 47% from the previous quarter. But even with higher sales, the company went from a $974 million operating profit in the second quarter to a $567 million operating loss in the third.
Anthropic reported a $104 billion net loss for the first nine months of 2026, but about $94.3 billion came from accounting changes tied to convertible debt and similar instruments. That wasn’t cash going out the door.
What did rise was spending on computing and infrastructure, which reached $18.8 billion over those nine months, up from $4.4 billion a year earlier. For investors, the concern is whether sales can grow fast enough to cover those rising costs and turn a steady profit.
How Retail Can Play ANT Now
Anthropic was founded in 2021 by former OpenAI researchers. Today, its business goes beyond the Claude chatbot. Developers use Claude Code to write and review software. If more teams make it part of their daily work, Anthropic has a chance to sell more to companies that already use Claude.
The risk is that Anthropic has agreed to pay for computing power before it knows how much customers will need. Its IPO filing disclosed $447.5 billion in computing and infrastructure commitments expected by the end of 2030.
Some contracts require Anthropic to pay even if it doesn’t use the capacity. When the company reports its first earnings as a public company, look for whether it’s keeping more of each sales dollar after covering its operating costs.
For most retail investors, the best bet would be to sit out day one. If ANT finishes well above its $83 offer price, don’t chase it. And if it drops, don’t buy just because it’s cheaper than it was at the open.
Ask what Anthropic would need to earn to justify the price. If the numbers work without assuming years of rapid growth or a big jump in profit margins, buy a small stake with a limit order at a price you’re comfortable paying. Otherwise, wait for the first earnings report.
The Analyst Debate Over Anthropic’s Premium
Anthropic computing deals are good news for its suppliers, but they’re also a big expense for Anthropic. Yorkville Ives analyst Dan Ives called the IPO an “important step” because those deals point to years of demand for chipmakers, cloud providers, and data centers. He also thinks that if Anthropic holds its valuation after the debut, it could help make the case for a future OpenAI IPO. That’s good news for the industry, but it doesn’t tell you what to pay for ANT.
Research firm New Constructs sees a risk in those same deals. Anthropic has agreed to pay suppliers for years, but its customers haven’t made the same kind of commitment. Investor Michael Burry points to the “take-or-pay” terms. If customers use less computing power than Anthropic expects, the company can still be stuck with the bill.
Morningstar senior equity analyst Malik Ahmed Khan sees room for growth, especially in coding and cybersecurity. But he says Anthropic needs to keep growing fast without letting the cost of building and running its models get out of hand. It’s still unclear how tough competition will get or how profitable the business can be.
Conclusion
I’d keep ANT on the watchlist and sit out day one. If shares jump out of the gate, I bet that they give back some of those gains over the next few sessions as the rush for shares cools. But a dip doesn’t automatically make ANT cheap. I’d wait for a price that makes sense without assuming everything goes right, or for Anthropic’s first earnings report to show it can grow sales and improve margins at the same time. If the price gets there first, start small. If it doesn’t, there’s no need to force the trade.
On the date of publication, Ebube Jones did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.