


EN
Helmerich & Payne’s Q3 CY2026: Beats on revenue
Land drilling contractor Helmerich & Payne (NYSE:HP) reported calendar Q3 2026 [fiscal Q4 2026] results topping the market’s revenue expectations, with revenue up 7.9% year on year to $1.09 billion. Its non-GAAP profit of $0.36 per share was 52.4% above analysts’ consensus estimates.
For more on Helmerich & Payne, read our full research report for free.
Helmerich & Payne Q3 CY2026 highlights:
- Revenue $1.09 billion vs analysts' consensus estimates of $1.07 billion, according to S&P (7.9% year-on-year growth, 2.1% beat)
- Adjusted EPS $0.36 vs analysts' consensus estimates of $0.24, according to S&P (52.4% beat)
- Adjusted EBITDA $268.6 million vs analysts' consensus estimates of $260.2 million (24.6% margin, 3.3% beat)
- Operating margin -48.6%, down from -0.1% in the same quarter last year
- Free cash flow margin 3%, down from 14.1% in the same quarter last year
- Market capitalization $3.51 billion
“I am proud of H&P’s fiscal 2026 performance and the strong finish we delivered,” said President and CEO Trey Adams. “In the fourth quarter, direct margins were at or above the high end of our guidance ranges across all segments.
Revenue growth
Cyclical sectors like energy often flatter weaker operators during favorable price environments, but a longer-term lens separates those from businesses that can consistently perform across market cycles. Helmerich & Payne’s 27.4% annualized revenue growth over the last five years was strong. Its growth beat the average energy upstream and integrated energy company and shows its offerings resonate with customers.
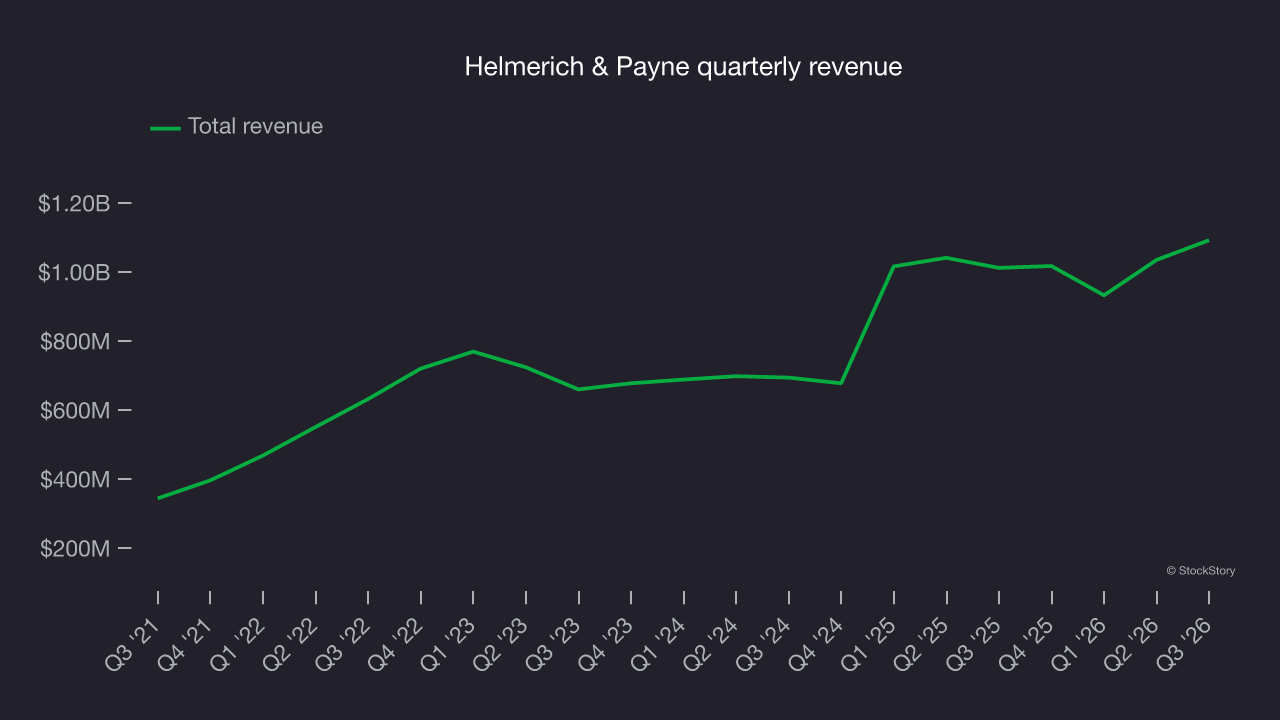
Within energy, a single time frame, even a long one, only sheds light on how well a company rode the last commodity cycle. An even longer, ten-year view helps assess whether a company compounds through cycles. Helmerich & Payne’s annualized revenue growth of 11.3% over the last ten years is below its five-year trend, but the results still suggest decent demand.
This quarter, Helmerich & Payne reported year-on-year revenue growth of 7.9%, and its $1.09 billion of revenue exceeded Wall Street’s consensus estimates by 2.1%.
Adjusted EBITDA margin
Adjusted EBITDA margin strips out accounting distortions tied to depletion and historical drilling spend, providing a clearer view of the cash-generating power of the underlying asset base before financing and reinvestment decisions.
Helmerich & Payne was profitable over the last five years but held back by its large cost base. Its average EBITDA margin of 26% was weak for an upstream and integrated energy business.
On the positive side, Helmerich & Payne’s EBITDA margin rose by 1.9 percentage points over the last year, as its revenue growth gave it operating leverage.
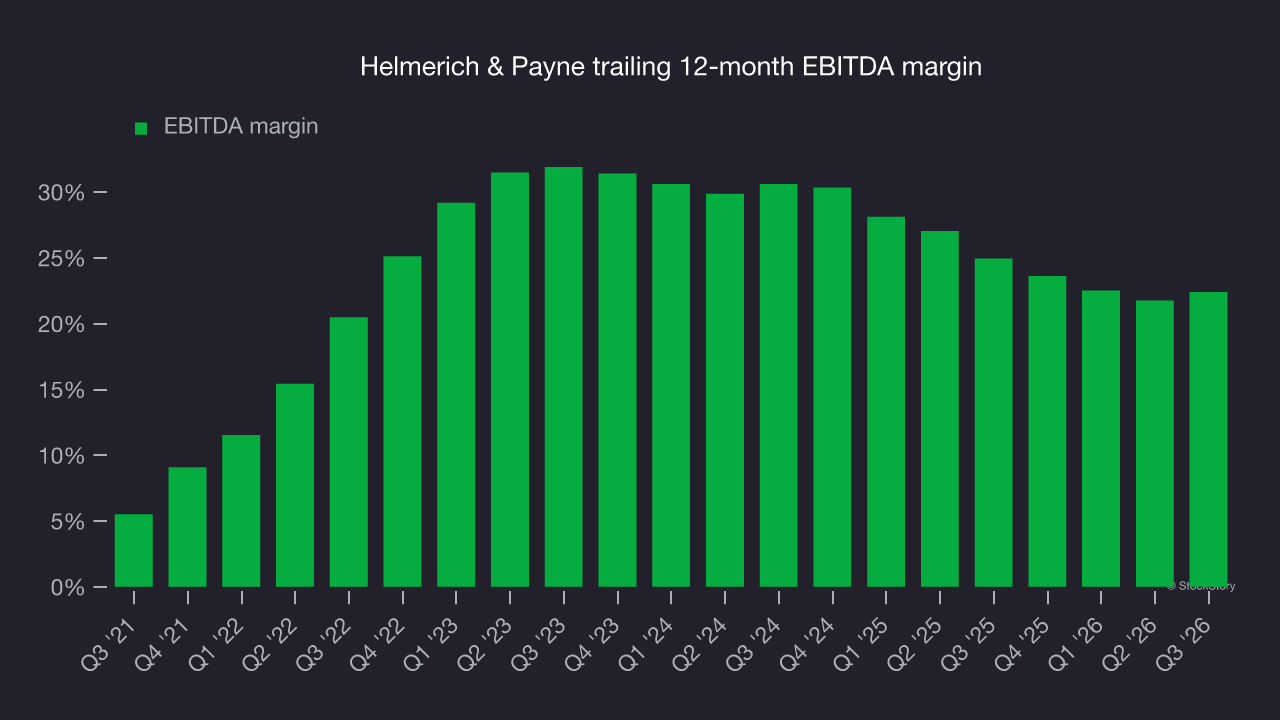
In Q3, Helmerich & Payne generated an EBITDA profit margin of 24.6%, up 2.4 percentage points year on year. The increase was a positive sign, showing improved efficiency. Adjusted EBITDA beat Wall Street’s consensus estimates by 3.3%.
Free cash flow
Adjusted EBITDA shows how profitable a company’s existing wells are before financing and reinvestment decisions, but free cash flow shows how much value remains after paying the cost of replacing those wells. In upstream energy, production naturally declines over time, so companies must continuously reinvest just to stand still. A producer can report strong EBITDA margins yet generate little or no free cash flow if its wells decline quickly or if new drilling is expensive. Free cash flow therefore captures not only how efficiently a company produces hydrocarbons today, but also how costly it is to sustain that production into the future.
Helmerich & Payne has shown mediocre cash profitability relative to peers over the last five years, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 5.9%, below expectations for an upstream and integrated energy business.
The level of free cash flow is important, but its durability across cycles is just as critical. Consistent margins are far more valuable than volatile swings driven by commodity prices.
Helmerich & Payne’s ratio of quarterly free cash flow volatility to WTI crude price volatility over the past five years was 10 (lower is better), indicating reasonable insulation from commodity swings.
This stability analysis compares free cash flow rather than revenue or EBITDA with WTI crude prices. What ultimately matters is not how much revenue or profit a company earns when prices are high but how much cash it can generate when prices are low. Free cash flow is the superior metric because it includes everything from hedging effectiveness to growth and maintenance capex to management behavior during good times and bad.
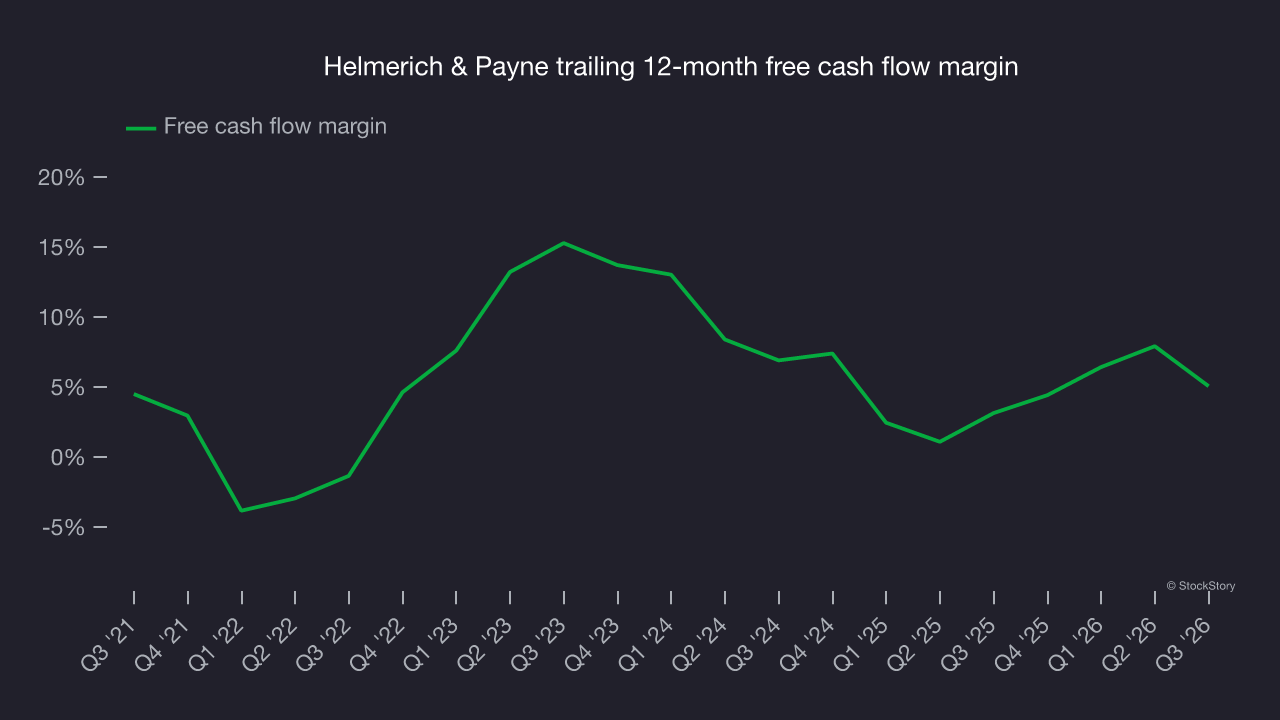
Helmerich & Payne’s free cash flow totaled $32.74 million in Q3, equivalent to a 3% margin. The company’s cash profitability deteriorated, with its margin 11.1 percentage points lower than in the same quarter last year, a decline that warrants closer attention. Short-term fluctuations typically aren’t a major concern because investment needs can be seasonal, but whether the decline continues in future quarters bears watching.
Key takeaways from Helmerich & Payne’s Q3 results
Helmerich & Payne delivered a solid quarter, topping analysts’ consensus estimates for both EPS and revenue. The results had some clear positives, but investors were likely hoping for more: Shares fell 3.2% to $34.04 immediately after the report.
Assessing Helmerich & Payne at its current price requires considering its valuation, business quality and latest quarterly results. Read the full research report here (it’s free).