


EN
The Stock Market Is About to Do Something It Has Never Done: Absorb 2 Trillion-Dollar IPOs in 6 Months. Prediction: SpaceX Stock, Not Anthropic, Is the One That Benefits.
Key Points
Anthropic has huge spending commitments for SpaceX's services.
A successful initial public offering for Anthropic would validate SpaceX's business model and derisk SpaceX in different ways.
The Anthropic (NASDAQ:ANT) initial public offering (IPO) follows the Space Exploration Technologies (NASDAQ:SPCX) IPO earlier this year, and there could be yet another IPO of a trillion-dollar-valued AI-related company next year if OpenAI comes to market in 2027. Despite the recent market turbulence centered on Nvidia and Jensen Huang, there are no signs yet of a slowdown in AI spending, which means AI infrastructure companies like SpaceX are ideally placed to benefit from Anthropic’s IPO. Here's why.
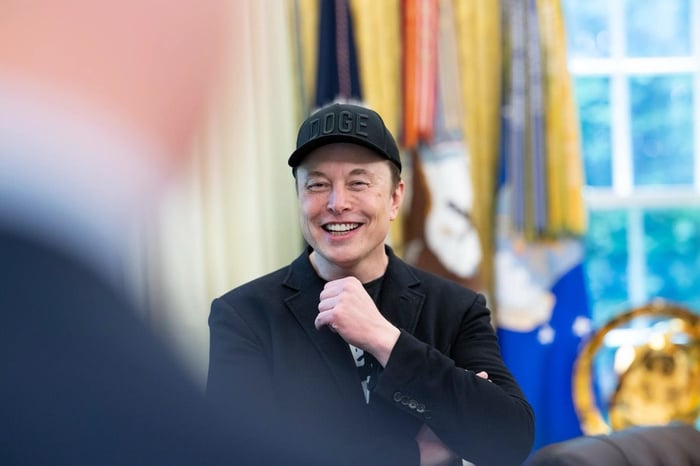
Image source: The White House.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
The Anthropic IPO is good news for AI infrastructure companies
As outlined in its Securities and Exchange Commission (SEC) filings, Anthropic has long-term spending commitments totaling $900.9 billion, with $451.6 billion expected to occur before the end of 2030.
Under its "infrastructure service arrangements," Anthropic has significant commitments to buy AI compute and infrastructure services (including graphics processing unit, or GPU, compute demand) from Microsoft ($47.2 billion to $49.2 billion), Alphabet's Google (at least $121.3 billion), Amazon.com (at least $110 billion), and SpaceX for up to $120.5 billion "to access compute powered by NVIDIA GPUs."
The SpaceX deals are the most interesting and, by some distance, the most important for the company's AI strategy.
Why the Anthropic/SpaceX deal matters
SpaceX CEO Elon Musk recently caused a stir by arguing that many neoclouds (cloud computing providers built solely for AI) would face extinction due to a lack of funding availability for companies that don't have revenue independent of AI. In the same X post, he noted that "SpaceX closed $40B of debt for GPUs, but we're investment grade and have Starlink & launch revenue."
In other words, SpaceX is in a financial position to build out the infrastructure to meet demand from Anthropic and others, while many potential rivals are not. That financial strength partly relies on the expectation of future revenue from Anthropic. The Wall Street analyst consensus, according to S&P Global Market Intelligence, expects SpaceX to spend $770 billion on capital over the next three years. However, SpaceX needs AI enterprises, such as Anthropic, to commit to demand to justify this sort of AI infrastructure build-out.
Here’s why the Anthropic IPO is good news for SpaceX
As such, the Anthropic IPO is positive for SpaceX for the following reasons:
- It strengthens Anthropic's financial position and, in doing so, the ability to pay for one of SpaceX's key customers, helping derisk SpaceX's business.
- As touched on above, part of the reason SpaceX can secure funding is that it's seen as a key "picks and shovels" play on the need for Anthropic and others to invest in AI infrastructure services. The Anthropic IPO helps SpaceX raise the cash to invest.
- The IPO will encourage Anthropic to invest more in developing AI models, thereby increasing demand for GPU capacity.

Image source: Getty Images.
Can SpaceX leverage compute scarcity?
An additional reason needs circumspection, as it cuts both ways. While Anthropic has agreements committing $120.5 billion to SpaceX, each party can cancel agreements in "periods ending in January 2027 and March 2027 under the respective agreement; each agreement may be canceled" given 90 days' notice.
If you are bullish on AI-driven demand for GPU compute, you might think SpaceX could cancel the agreement and sell to other customers at higher prices. If you take a more bearish view on AI demand, you would be concerned that SpaceX is first in line if Anthropic needs to pare back spending or it develops its own data centers. The other agreements discussed above with Microsoft, Alphabet, and Amazon are not cancelable unless there is a breach of contract.
A successful Anthropic IPO strengthens the more optimistic case and, ultimately, the case for buying SpaceX stock.
Lee Samaha has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Alphabet, Amazon, Microsoft, Nvidia, S&P Global, and Space Exploration Technologies. The Motley Fool has a disclosure policy.