


EN
Do Wall Street Analysts Like International Flavors & Fragrances Stock?
International Flavors & Fragrances Inc. (IFF), headquartered in New York, produces and markets cosmetic active and natural health ingredients for use in various consumer products. Valued at $20.1 billion by market cap, the company flavors and fragrances are individual ingredients and compounds of a large number of ingredients that are blended, mixed, and reacted together to produce proprietary formulas.
Shares of this leading global creator of flavors and fragrances have outperformed the broader market over the past year. IFF has gained 21.3% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 10.7%. In 2026, IFF stock is up 18.8%, surpassing the SPX’s 7% rise on a YTD basis.
Zooming in further, IFF’s outperformance is also apparent compared to the State Street Materials Select Sector SPDR ETF (XLB). The exchange-traded fund has gained about 18% over the past year. Moreover, IFF’s gains on a YTD basis outshine the ETF’s 11.3% returnsover the same time frame.
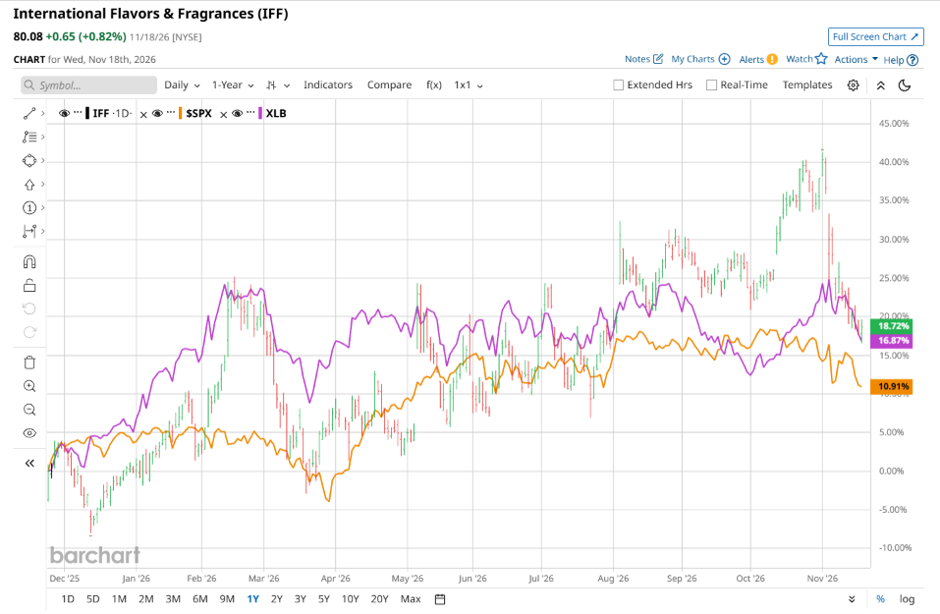
IFF has largely outperformed on the back of a portfolio simplification and deleveraging story, most notably progress on divesting non-core units, including the planned Food Ingredients separation expected around mid-2027, and applying proceeds toward debt reduction, paired with steadier organic volume growth in core Taste, Scent, and Health & Biosciences operations, stronger free cash flow conversion, and capital returns like its completed $500 million share repurchase program and expanded buyback authorization. That re-rating has helped IFF run well ahead of broader market benchmarks over the year, even as recent pullbacks reflect raw-material inflation, a lag between input costs and customer pricing, and debates over how much near-term upside remains after a sharp rally.
On Nov. 3, IFF shares closed down by 2.6% after reporting its Q3 results. Its adjusted EPS of $0.83 surpassed Wall Street expectations of $0.81. The company’s revenue was $1.94 billion, beating Wall Street forecasts of $1.92 billion. IFF expects full-year revenue in the range of $7.5 billion to $7.6 billion.
For the current fiscal year, ending in December, analysts expect IFF’s EPS to decline 25.2% to $3.14 on a diluted basis. The company’s earnings surprise history is mixed. It beat the consensus estimate in two of the last four quarters while missing the forecast on two other occasions.
Among the 22 analysts covering IFF stock, the consensus is a “Moderate Buy.” That’s based on 13 “Strong Buy” ratings, two “Moderate Buys,” six “Holds,” and one “Moderate Sell.”
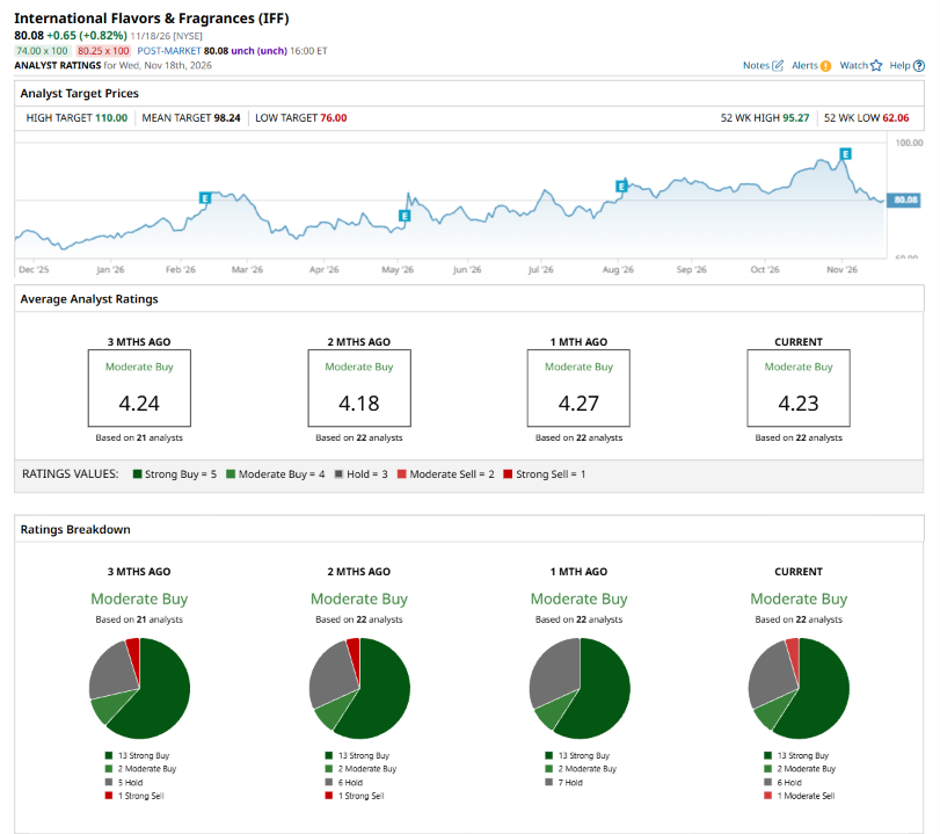
The configuration has been relatively stable over the past three months.
On Nov. 6, Bank of America Corporation (BAC) downgraded IFF to an “Underperform” rating with a price target of $91, implying a potential upside of 13.6% from current levels.
The mean price target of $98.24 represents a 22.7% premium to IFF’s current price levels. The Street-high price target of $110 suggests an ambitious upside potential of 37.4%.
On the date of publication, Neha Panjwani did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.