


EN
Why Is United Parcel Service (UPS) Drawing Fresh Attention Today?
United Parcel Service (UPS) is back in focus after the company agreed to acquire Smartways Logistics, a healthcare courier specialist in Australia and New Zealand, in a move that aims to deepen its presence in Asia Pacific.
For investors watching the bigger picture, United Parcel Service sits at a share price of US$111.03, with a 30-day share price return of 13.92% and a year-to-date gain of 9.91%. The 1-year total shareholder return of 27.72% contrasts with declines over the 3- and 5-year total return periods, hinting at improving momentum after a tougher multi year stretch.
Scan how United Parcel Service compares with other logistics and transport plays showing strong momentum and fundamentals using our curated list of solid balance sheet and fundamentals (24 results)
United Parcel Service is clearly pushing to widen its healthcare reach with Smartways, yet strong operations do not automatically mean a fair entry price. So how does the current valuation stack up against that ambition?
Most Popular Narrative: 3.8% Undervalued
On the analyst consensus Narrative on Simply Wall St, United Parcel Service screens as modestly undervalued, with a fair value of about $115.46 against the latest close at $111.03, which frames the recent Smartways deal against a stock already close to those estimates.
United Parcel Service is moving further away from low-yield Amazon volumes after completing the Amazon glide down that removed about 2 million low-quality pieces per day and reduced related expenses by about US$4.5b. This directly supports higher net margins and operating profit.
See why 226 investors see United Parcel Service as 4% undervalued.
Result: Fair Value of $115.46 (UNDERVALUED)
Still, the United Parcel Service story depends on execution. Planned building closures and future labor negotiations are both capable of squeezing margins if they do not go smoothly.
Find out about the key risks to this United Parcel Service narrative.
Another View: Multiples Paint A Tougher Picture For United Parcel Service
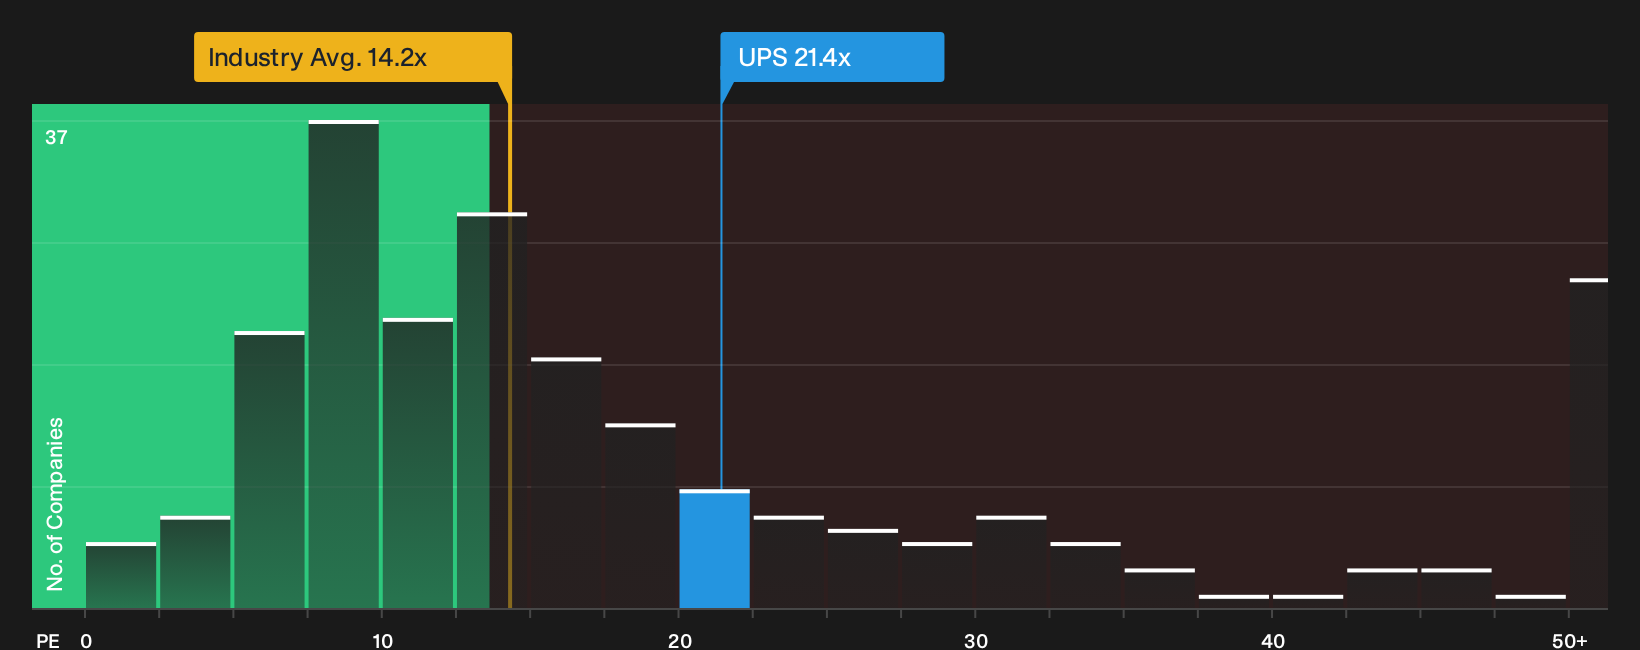
The analyst narrative tags United Parcel Service as about 3.8% undervalued, yet the market pricing tells a different story. UPS trades on a P/E of 21.4x, which is higher than the US logistics peer average of 18.5x and above the global logistics group at 14.2x, even though its own fair ratio is estimated at 26x. That mix of richer current pricing versus peers but a higher fair ratio target points to real valuation risk if sentiment cools, as well as potential upside if earnings deliver against expectations. Which side of that trade off are you more comfortable leaning toward?
To see how this pricing gap could resolve, including where the ratio might move relative to the fair ratio, take a closer look at the detailed valuation workup in our breakdown, starting with See what the numbers say about this price — find out in our valuation breakdown.
For a visual sense of how United Parcel Service compares against its sector on this metric, review the latest relative chart here
Next Steps
Momentum, valuation tension and mixed sentiment are clear around United Parcel Service at this point. Act while the data is fresh and form your own view by weighing 2 key rewards and 3 important warning signs
Looking for more investment ideas beyond United Parcel Service?
If United Parcel Service has your attention, do not stop with a single ticker. Widen your opportunity set across quality, income, and lower risk profiles.
- Target resilient balance sheets and steady fundamentals by scanning our focused list of solid balance sheet and fundamentals (24 results) for companies that keep financial risk in check.
- Hunt for potential value opportunities by reviewing the 35 high quality undervalued stocks that combine quality metrics with pricing that may not yet reflect them.
- Build a payment-focused watchlist by zeroing in on 8 dividend fortresses that aim to match strong yields with durable business models.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com