


EN
Marriott International Stock: Analyst Estimates & Ratings
Bethesda, Maryland-based Marriott International, Inc. (MAR) is one of the world's largest hotel and hospitality companies, operating, franchising, and licensing a global portfolio of hotels, resorts, residential properties, and vacation ownership offerings. With a market capitalization of around $108.9 billion, the company serves business and leisure travelers across a wide range of price points and accommodation categories.
Marriott stock has been checking in far ahead of the competition. MAR stock has returned 55.6% over the past 52 weeks, beating the broader S&P 500 Index ($SPX), which has gained 10.7% over the same period. Moreover, over the past six months, the stock climbed 16% versus the index’s 1.1% drop.
MAR has also left its hotel-focused benchmark in the rearview mirror, outpacing the State Street Consumer Discretionary Select Sector SPDR Fund’s (XLY) 6.2% uptick over the past 52 weeks and 2.5% rise over the past six months.
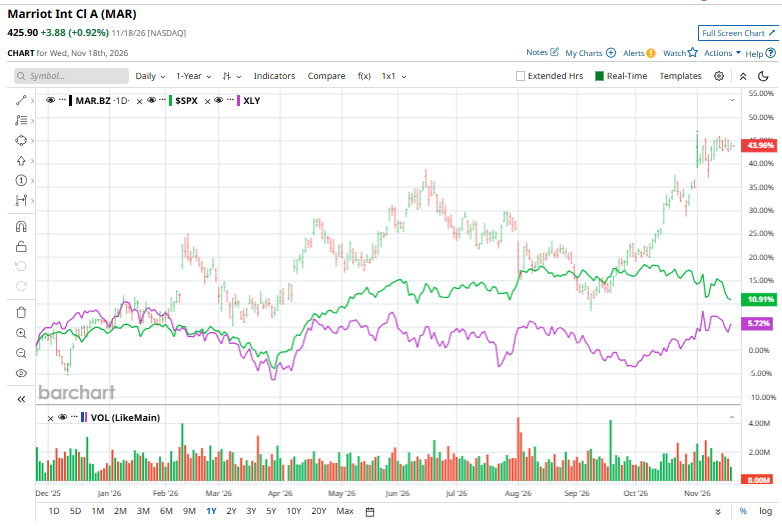
On Nov. 2, Marriott International shares jumped 4.3% after the company reported better-than-expected fiscal 2026 third-quarter results, driven by resilient global travel demand, higher room rates, and improved hotel occupancy. Revenue increased 8% year-over-year to $7.01 billion, surpassing analyst expectations of approximately $6.91 billion, while adjusted diluted EPS surged 22.3% to $3.02, beating estimates of $2.83. A key growth driver was the 6.5% increase in worldwide comparable systemwide revenue per available room (RevPAR), supported by a 4.8% improvement in average daily rates (ADR) and a 1.1-percentage-point increase in occupancy to 72.5%.
The company added approximately 20,100 net rooms during the quarter, while its development pipeline reached a record of more than 4,200 properties and 634,000 rooms, supporting its longer-term expansion prospects. Following the strong quarterly performance, management raised its full-year FY2026 outlook, now expecting worldwide RevPAR growth of 4.5% to 5%, compared with its previous forecast of 3% to 3.5%. Adjusted EPS guidance was raised to $12.07–$12.14, while adjusted EBITDA is projected at $6.08–$6.10 billion.
For the fiscal year ending in December 2026, analysts expect Marriott’s adjusted EPS to grow 20.7% year over year to $12.09. The company’s earnings surprise history is mixed. It beat the consensus estimates in three of the last four quarters while missing on one other occasion.
The overall consensus rating on the stock stands at a “Moderate Buy” based on coverage from 29 analysts. That includes 11 “Strong Buy” ratings, two “Moderate Buys,” 15 “Holds,” and one “Strong Sell.”
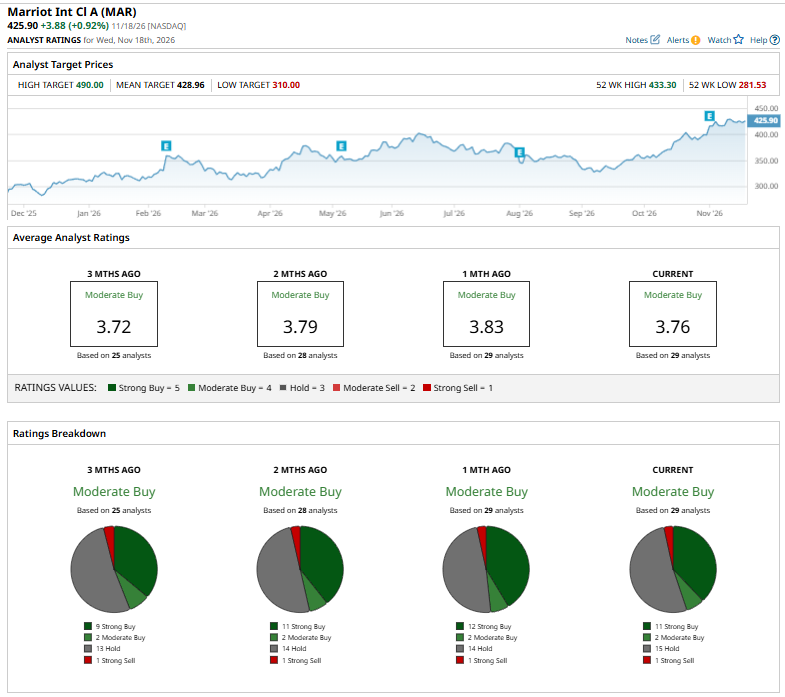
The configuration is bearish than a month ago, when the stock had 12 “Strong Buy” suggestions.
On Nov. 4, Jefferies lowered its price target on Marriott International to $141 from $147 while maintaining a “Buy” rating, signaling a modest reduction in its valuation expectations despite remaining bullish on the stock.
MAR stock’s mean price target of $428.96 represents a marginal premium from the current market price. The Street-high price target of $490 implies an upside potential of 15.1%.
On the date of publication, Kritika Sarmah did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.