


EN
Maximus posts Q3 CY2026 sales in line with estimates, full-year sales guidance is solid
Government services provider Maximus (NYSE:MMS) met Wall Street’s revenue expectations in calendar Q3 2026 [fiscal Q4 2026], but revenue edged lower by 1.3% year on year to $1.3 billion. The company’s full-year revenue guidance of $5.55 billion at the midpoint came in 3.2% above analysts’ consensus estimates. Its non-GAAP profit of $2.11 per share was 14.1% above analysts’ consensus estimates.
For more on Maximus, read the full research report for free.
Maximus Q3 CY2026 highlights:
- Revenue $1.3 billion vs S&P analyst consensus of $1.3 billion (1.3% year-on-year decline, in line)
- Adjusted EPS $2.11 vs S&P analyst consensus of $1.85 (14.1% beat)
- Adjusted EBITDA $190.2 million vs analysts’ consensus estimates of $162.1 million (14.6% margin, 17.4% beat)
- Adjusted EPS guidance $7.75 at the midpoint for fiscal 2027, missing analysts’ consensus estimates by 7.3%
- EBITDA guidance $707.5 million at the midpoint for fiscal 2027, in line with analysts’ consensus estimates
- Operating margin 12.1%, up from 6.3% in the same quarter last year
- Free cash flow margin 21.3%, down from 48.7% in the same quarter last year
- Market capitalization $3.42 billion
"Fiscal year 2026 reflected the benefits of disciplined execution, technology-enabled productivity enhancements, and thoughtful capital allocation," said Bruce Caswell, President and Chief Executive Officer. "Throughout the year, we continued deploying automation and AI-enabled solutions across our operations, improving efficiency, strengthening profitability, and delivering meaningful outcomes for customers. These efforts contributed to adjusted diluted earnings per share of $8.24, representing 12.0% growth over the prior year and performance above the top end of our most recently updated guidance range."
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Even a poor business can perform well for one or two quarters, but a high-quality one grows for years. Maximus’s revenue grew at a mediocre 4.2% compounded annual growth rate over the last five years, falling short of the business services sector standard.
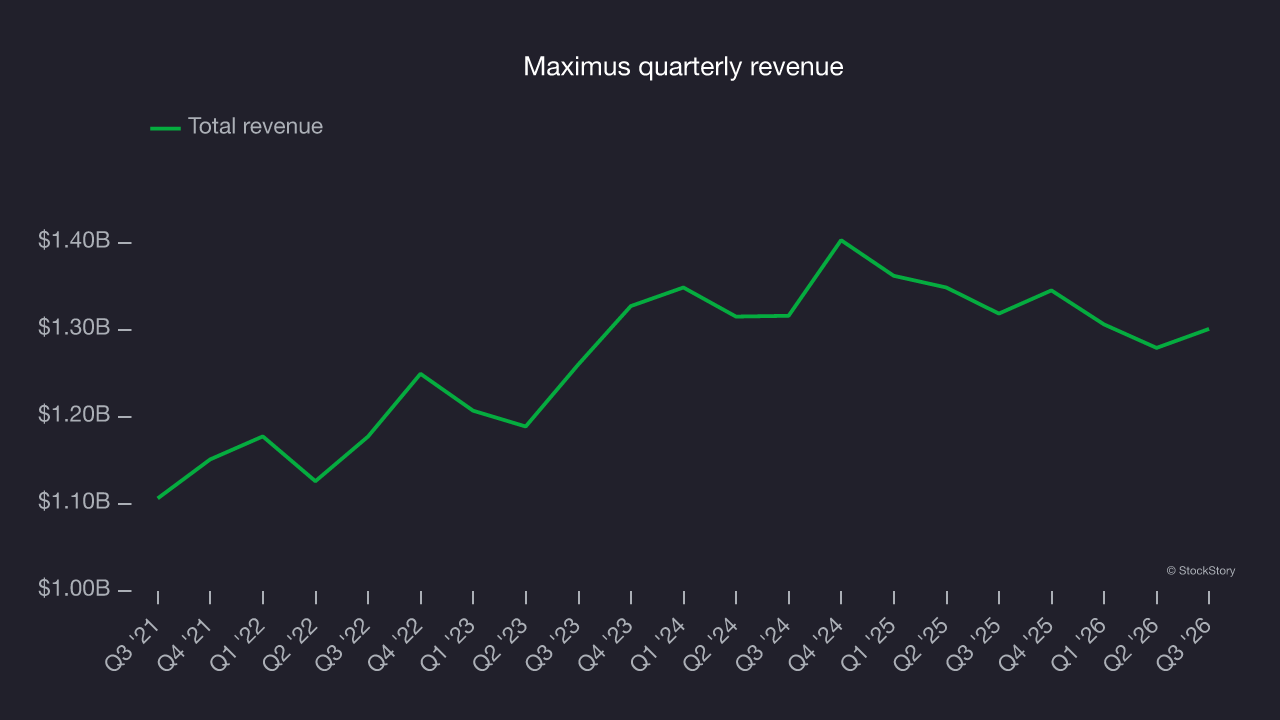
Long-term growth matters most, but within business services, a half-decade historical view may miss recent innovations or disruptive industry trends. Maximus’s recent performance shows its demand has slowed as its revenue was flat over the last two years. 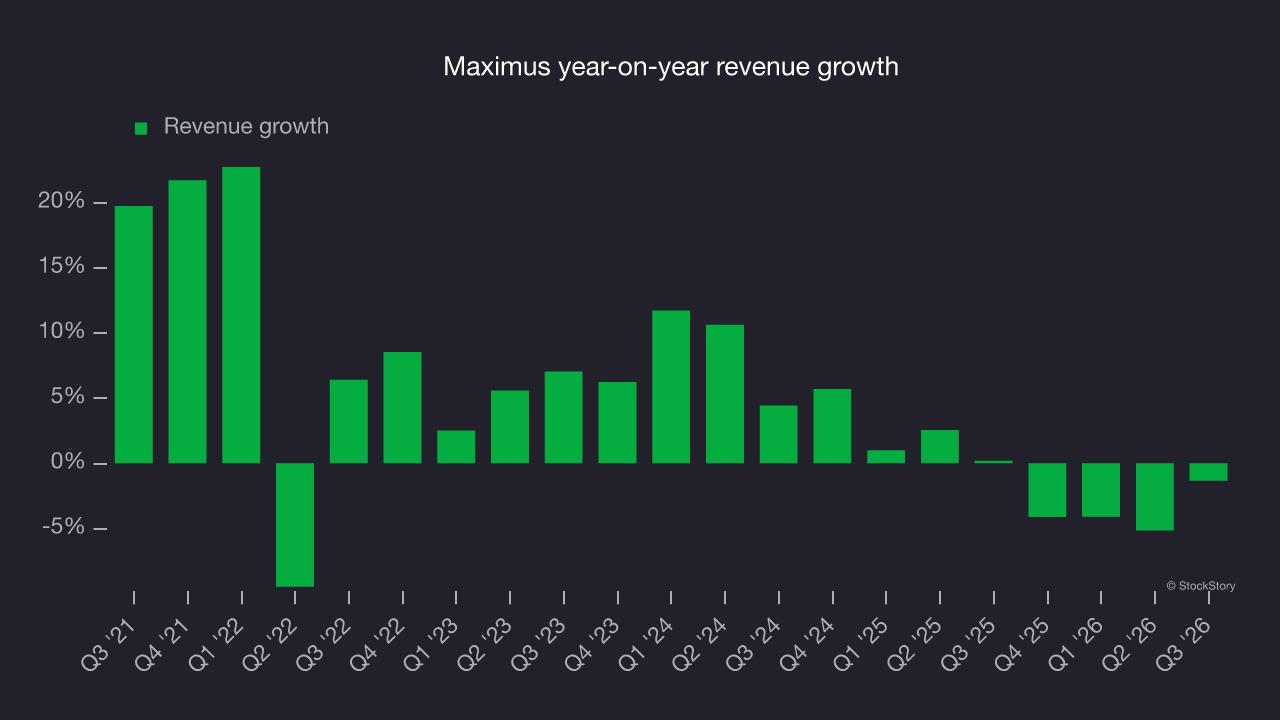
This quarter, Maximus reported an uninspiring 1.3% year-on-year revenue decline to $1.3 billion, in line with Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 5.7% over the next 12 months, according to S&P, an improvement versus the last two years. This projection is above the sector average and suggests its newer products and services will spur better top-line performance.
Adjusted operating margin
Maximus was profitable over the last five years but held back by its large cost base. Its average adjusted operating margin of 9.2% was weak for a business services company.
On the positive side, Maximus’s adjusted operating margin rose by 5.2 percentage points over the last five years, as its revenue growth provided operating leverage.
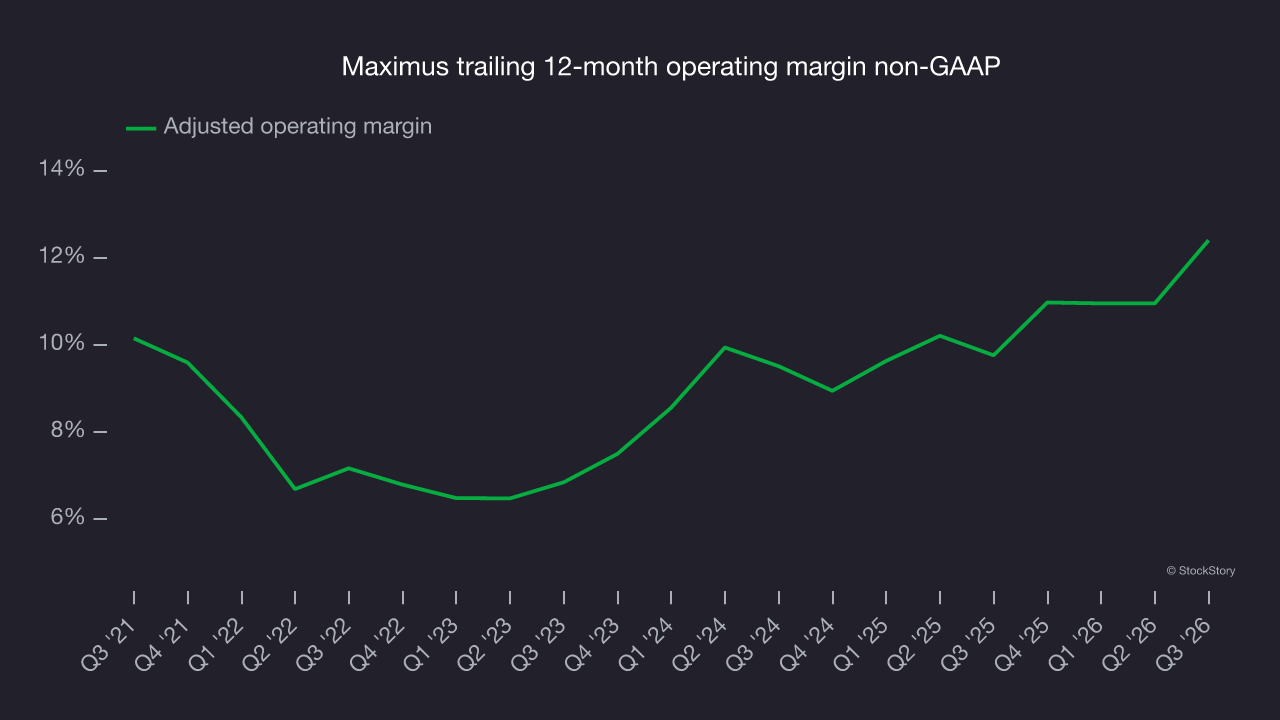
This quarter, Maximus generated an adjusted operating profit margin of 12.9%, up 5.8 percentage points year on year. The increase was a positive development, especially since revenue fell, showing that expense reductions improved efficiency.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share, or EPS, points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Maximus’s EPS grew at a 12.1% compounded annual growth rate over the last five years, higher than its 4.2% annualized revenue growth. This indicates the company became more profitable on a per-share basis as it expanded.
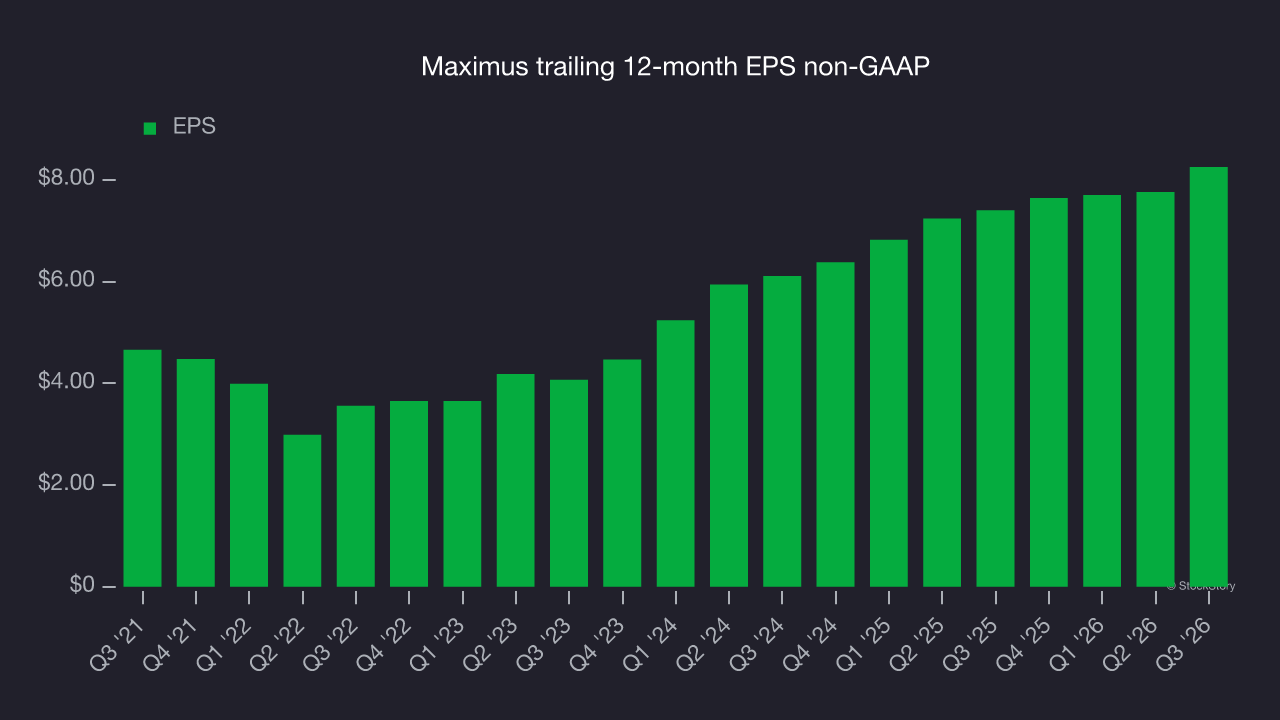
A closer look at Maximus’s earnings helps explain its performance. As mentioned earlier, Maximus’s adjusted operating margin expanded by 5.2 percentage points over the last five years. In addition, its share count shrank by 15.1%. These are positive signs for shareholders because improving profitability and share buybacks boost EPS growth relative to revenue growth. 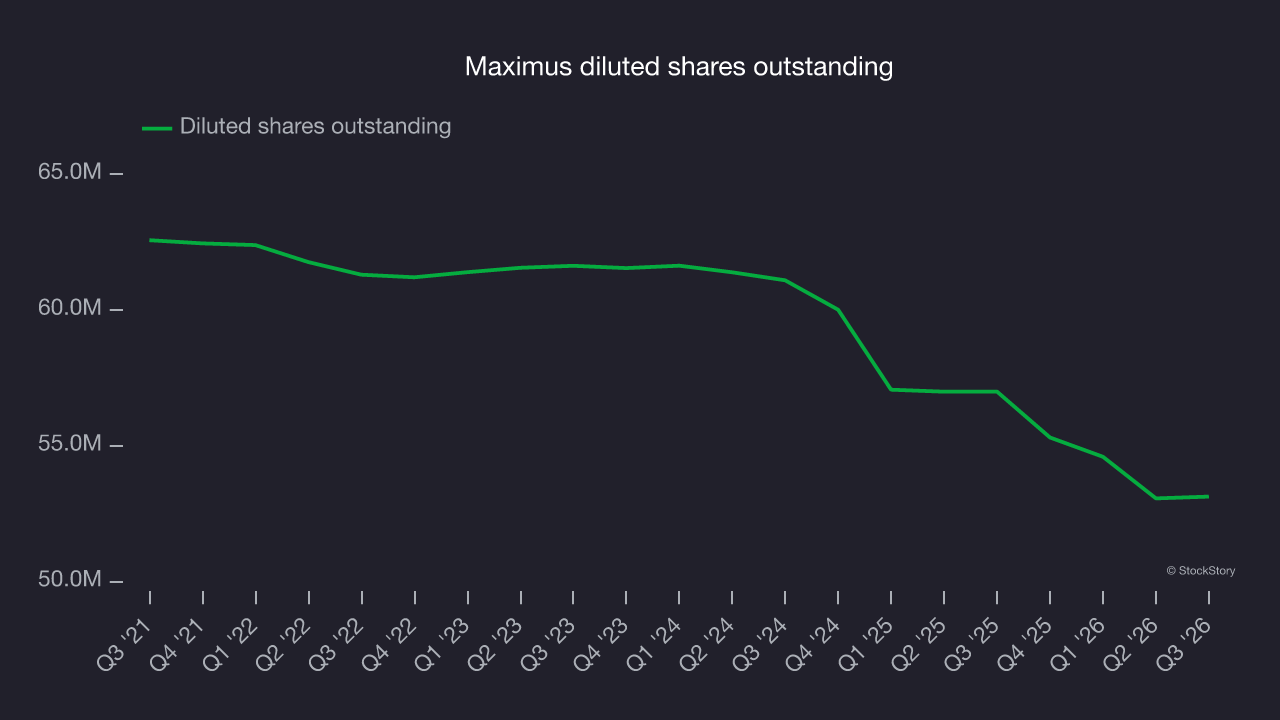
As with revenue, examining EPS over a shorter period can reveal changes in the business.
Maximus’s two-year annual EPS growth of 16.2% was higher than its five-year trend. That acceleration is a positive sign, particularly given the already high base.
In Q3, Maximus reported adjusted EPS of $2.11, up from $1.62 in the same quarter last year. Adjusted EPS comfortably beat analysts’ consensus estimates, a positive result for shareholders. Over the next 12 months, Wall Street expects Maximus’s full-year EPS to grow 6.3% from $8.25 to $8.77, according to S&P.
Key takeaways from Maximus’s Q3 results
An EPS beat and full-year revenue guidance above Wall Street’s consensus gave Maximus’s quarter some key positives, but its full-year EPS outlook fell short of consensus estimates. The market seemed to be hoping for more: shares fell 2.2% to $63.86 immediately after the report.
To assess Maximus at its current price, consider the broader picture of valuation and business quality, as well as the latest earnings. For more on Maximus, read our full research report here (it’s free).