


EN
Is Tasmea (ASX:TEA) Fully Valued After Record Earnings And Upgraded Guidance?
Tasmea has more than doubled year to date, yet recent share price volatility and fresh earnings news now put a simple question in front of you: Is the current market value of the business still in step with what its profits justify?
- The stock is up about 101% year to date, which makes the link between Tasmea’s earnings power and today’s price far more important for anyone thinking about the next move.
- Management has reported record earnings and lifted expectations for future profit, which can support a case that investors are paying for a higher and more durable earnings base.
- Your read on Tasmea is one view; the desks covering it have another. See what analysts think Tasmea's shares could be worth.
The issue now is whether Tasmea’s current share price is reasonably aligned with what its earnings suggest the business is worth.
If you want a reference point for whether Tasmea’s earnings driven rerating still feels reasonable, compare it with companies in the 2 high quality undervalued stocks.
Does Tasmea Look Pricey on Earnings?
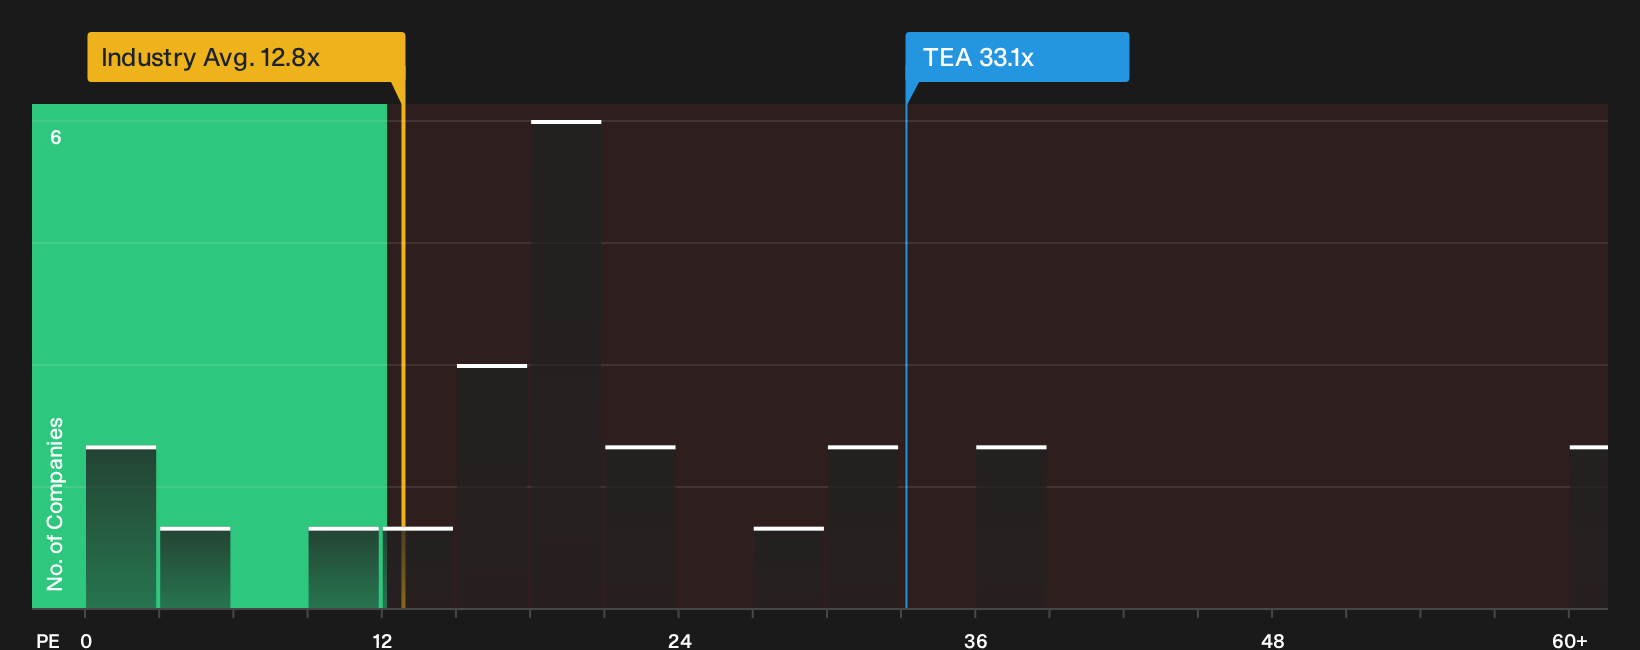
Tasmea is well suited to a P/E lens because profit is front and center in the recent results and in how the market seems to be judging the story. The stock trades on a P/E of 33.1x, compared with a construction sector average of 12.8x and a peer group near 26.6x, so buyers today are accepting a clear premium for each dollar of earnings.
The tailored fair P/E that reflects Tasmea’s economics and risk profile sits below the current 33.1x level, which points to the shares screening overvalued on this metric even after adjusting for factors such as growth and returns. Because management has reported record FY26 earnings and upgraded FY27 guidance, the rating implies that a lot of this strong execution is already reflected in the price rather than offering a simple catch up story. Investors need to judge whether Tasmea’s quality and outlook justify paying meaningfully more than both peers and what the model suggests as a fairer P/E anchor. Explore the numbers behind Tasmea's P/E valuation.
The Tasmea Narrative: What Would Justify Today's Price?
Narratives on Tasmea give you a direct link between the valuation puzzle above and the specific assumptions on growth, margins and earnings the current share price seems to be baking in. They sit on Simply Wall St's Community page. Each scenario ties its numbers to a clear view on where Tasmea's expansion, profitability and risk profile could head next, so you can revisit those views as fresh results or guidance come through.
Bulls and bears are reading the same Tasmea story yet landing on sharply different conclusions about what the current price already assumes.
Bull case: 9% undervalued
The analyst consensus Narrative on Simply Wall St frames Tasmea as a steady compounder built on contracted work and internal funding capacity.
"Tasmea’s compounding model that targets specialist acquisitions at set earnings multiples, combined with a balance sheet carrying low leverage and strong operating cash flow conversion, provides internal funding capacity that can affect future earnings per share and return on capital employed…"
Discover why this Narrative puts Tasmea at 9% undervalued.
Bear case: 91% overvalued
The bearish analyst Narrative on Simply Wall St focuses on whether Tasmea can keep converting its large opportunity set without stretching execution.
"The main requirement for success is that Tasmea converts its A$1.31b pipeline and more than 125 Master Service Agreements into ongoing cash-generative work without over-stretching its labour base…"
Explore why this Narrative puts Tasmea at 91% overvalued.
One more Tasmea check that belongs beside the earnings story
Tasmea’s valuation only tells part of the picture, because Simply Wall St’s broader review has also flagged specific risks that deserve a closer look before you rely on the headline multiples. Take a closer look at 2 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com