


EN
What Woodside Energy Group (ASX:WDS)'s Oil Supply Glut Means For Shareholders
- Recent commentary on Woodside Energy Group flags a projected global oil supply surplus lasting at least through 2027, raising questions about the durability of its oil linked revenue mix and future operating cash flows.
- The key issue is how a prolonged crude glut could pressure Woodside Energy Group’s oil exposure, while its LNG focused cash generation and cost control remain central to the business story.
- We will now look at how Woodside Energy Group's investment narrative compares with the prospect of a prolonged global oil surplus.
Scan how Woodside Energy Group’s oil and LNG mix compares with peers facing the same supply overhang by reviewing our hand picked 2 high quality undervalued stocks that is shaping the next leg of the energy trade.
Woodside Energy Group Investment Narrative Recap
To own Woodside Energy Group, you need to be comfortable with a LNG heavy story that still carries meaningful oil exposure. According to Jamesiskindacool, an investor in the Simply Wall St Community, the investment case leans on existing assets and near term production growth from projects already under construction. A prolonged oil surplus mainly tests how resilient that mix is in the next few years.
The near term swing factor remains execution at Scarborough and Pluto Train 2, which are described as 96% complete and targeting first LNG in late 2026. The biggest current pressure point is rising net debt, now about US$9.3b, combined with a dividend that is reported as not well covered by free cash flows.
With no fresh company announcements directly tied to the global supply commentary, the most relevant reference point is still Woodside Energy Group’s prior update on project progress and debt. Jamesiskindacool highlights that the valuation already assumes Scarborough and Pluto Train 2 start up as planned, while not including full success from every future LNG concept.
That framing matters more now. Earnings are forecast to edge lower over the next three years, revenue growth is expected to be modest at 3.8% a year, and return on equity is projected to stay relatively low. In this context, execution on currently funded LNG projects and discipline around higher risk borrowings appear to be the key operational catalysts and stress points.
On those figures, the A$36.60 fair value that Jamesiskindacool puts forward rests on revenue climbing 9.8% a year and the business holding a 20.9% profit margin. Together, these support an earnings profile that lines up with an 18x P/E on Woodside Energy Group’s assessed per share profits.
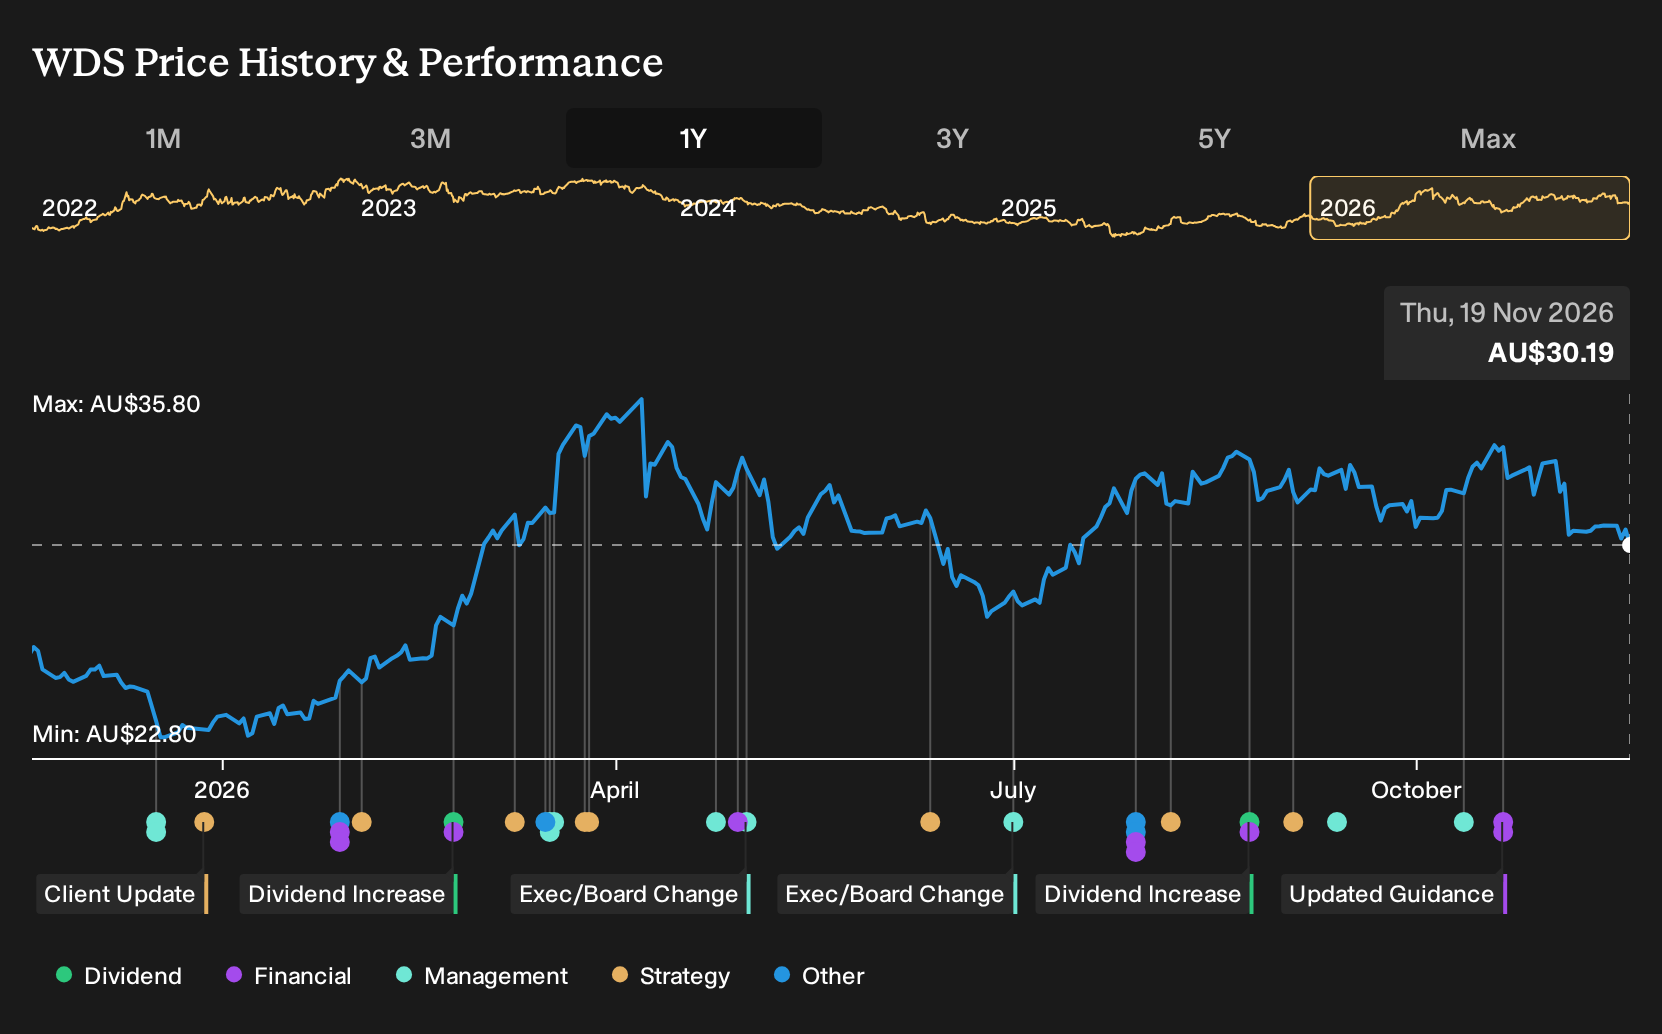
Uncover why Woodside Energy Group's fair value indicates a 21% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on Woodside Energy Group puts far more weight on long term demand transition risk. The most bearish analysts were already modelling revenue slipping about 1.7% a year and earnings easing from about US$3.1b to US$2.3b by 2029. Their forecasts pre date the oil surplus news, so their story may shift again.
Explore 5 other Woodside Energy Group fair value estimates, including one that suggests it could be worth just A$34.43.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Woodside Energy Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Woodside Energy Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Woodside Energy Group's overall financial health at a glance.
Looking for more investment ideas beyond Woodside Energy Group?
Once you have formed a view on Woodside Energy Group, it can help to compare that thesis with other opportunities using the Simply Wall St Screener. That way you can stress test your risk tolerance, income needs, and return expectations against a wider universe of businesses.
- If you want to focus on durability and lower volatility, start with a curated group of 5 resilient stocks with low risk scores that may better suit a more cautious approach.
- For investors who care most about balance sheet strength and underlying fundamentals, scan the list of solid balance sheet and fundamentals (12 results) as a filter for financial resilience.
- If you are hunting for potential mispriced ideas with solid quality markers, check out our hand picked 14 high quality undiscovered gems that could broaden your watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com