


EN
Is Wall Street Bullish or Bearish on Paychex Stock?
Paychex, Inc. (PAYX), headquartered in Rochester, New York, provides integrated human capital management solutions (HCM) for payroll, benefits, human resources (HR), and insurance services for small to medium-sized businesses. With a market cap of $40.6 billion, the company's services range from calculating payroll and filing tax payments to administering retirement plans and workers' compensation.
Shares of this industry-leading HCM company have underperformed the broader market over the past year. PAYX has gained 3.4% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 10.7%. In 2026, PAYX stock is up 1.3%, compared to the SPX’s 7% rise on a YTD basis.
Narrowing the focus, PAYX’s underperformance is also apparent compared to the State Street Industrial Select Sector SPDR ETF (XLI). The exchange-traded fund has gained about 9.9% over the past year. Moreover, the ETF’s 6.2% returns on a YTD basis outshine PAYX’s gains over the same time frame.
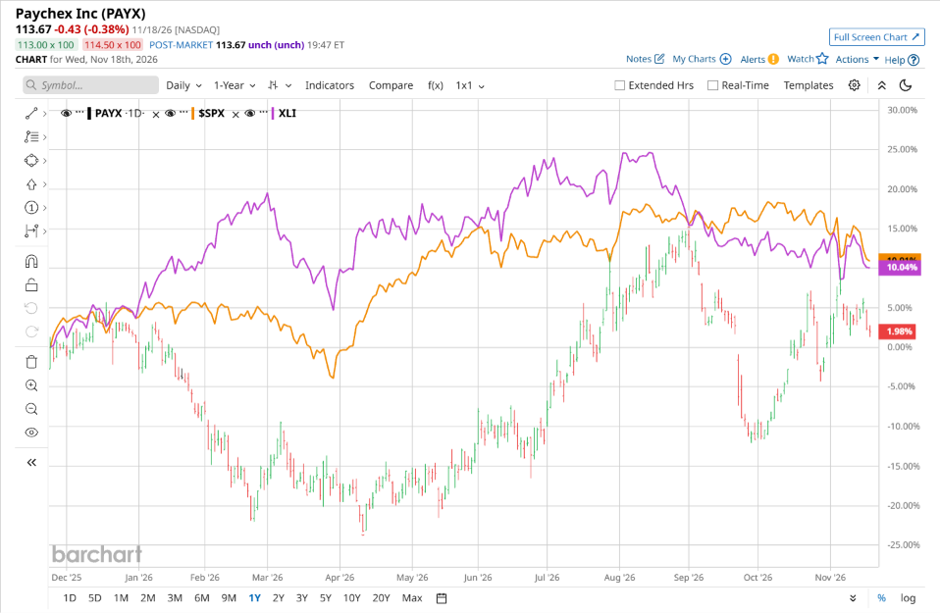
Paychex’s sluggish stock performance comes down to a tug-of-war between consistent profit growth and a cooling core market. Even as earnings remain steady, investors have pulled back due to sluggish small-business hiring and slower new company creation, both of which directly limit payroll volume expansion. Combined with escalating expenses and fears of narrowing profit margins, these headwinds have kept the market on edge.
For the current fiscal year, ending in May 2027, analysts expect PAYX’s EPS to grow 8.2% to $5.96 on a diluted basis. The company’s earnings surprise history is impressive. It beat the consensus estimate in each of the last four quarters.
Among the 20 analysts covering PAYX stock, the consensus is a “Hold.” That’s based on two “Strong Buy” ratings, 16 “Holds,” and two “Strong Sells.”
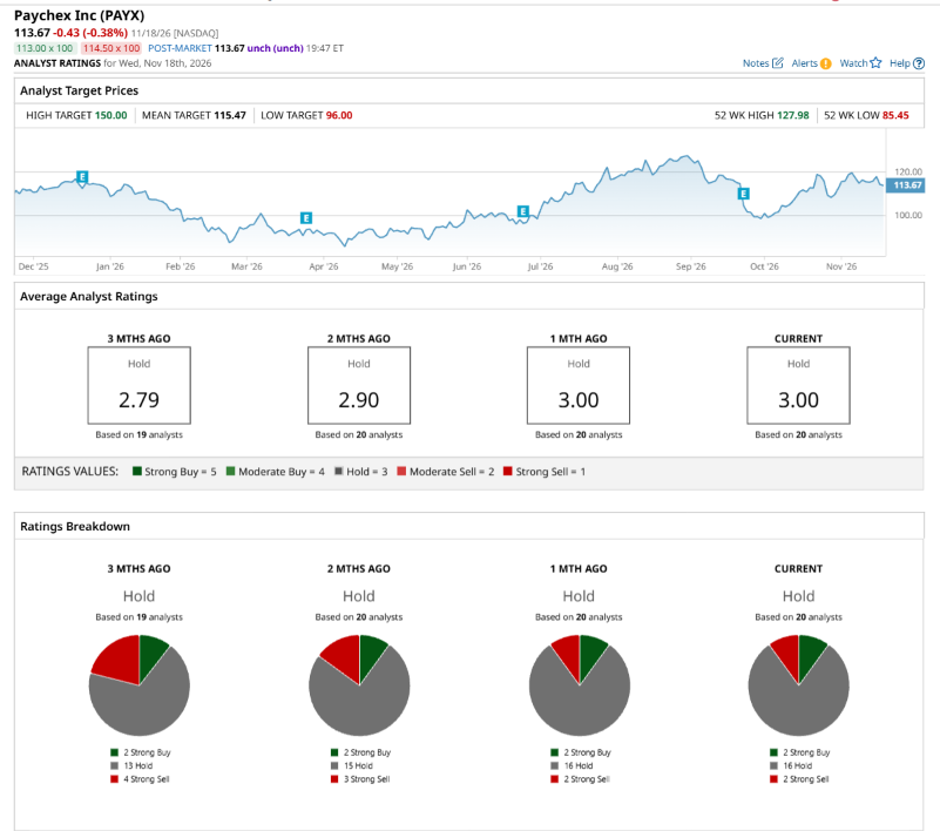
This configuration is less bearish than two months ago, with three analysts suggesting a “Strong Sell.”
On Nov. 13, Ashish Sabadra from RBC Capital maintained a “Hold” rating on PAYX, with a price target of $130, implying a potential upside of 14.4% from current levels.
The mean price target of $115.47 represents a 1.6% premium to PAYX’s current price levels. The Street-high price target of $150 suggests a notable upside potential of 32%.
On the date of publication, Neha Panjwani did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.